Home Blog Page 162

SEC Scores Victory in $18M Green United Crypto Mining Fraud: What It Means for Investors
SEC crypto-mining case against Green United moves forward, exposing a $18M fraud and its implications for investors and future crypto regulation.

The U.S. Securities and Exchange Commission (SEC) successfully advanced its legal battle against Green United LLC. The SEC accused the company of defrauding investors in an elaborate crypto-mining scheme raising $18 million. This marks a significant regulatory win for the SEC as it continues its push to clamp down on fraudulent activities in the cryptocurrency industry. The case, involving the sale of so-called “Green Boxes” that allegedly mined a non-existent token, “GREEN,” will now proceed to trial. This follows a court decision to deny the defendants’ motion to dismiss.

Alleged Fraud: How the Scheme Worked

According to the SEC’s March 2023 complaint, Green United, led by founder Wright Thurston and promoter Kristoffer Krohn, convinced investors to purchase “Green Boxes” and “Green Nodes”. They claimed these devices would mine the GREEN token on a supposed “Green Blockchain”. Investors believed that the blockchain would support a global decentralized power grid, and the value of the GREEN token would rise alongside the project’s success. The devices were marketed as highly profitable, with investors being promised returns as high as 40-50% per month.

However, the SEC alleges that there was no such blockchain, and GREEN was not a mineable token. Instead, Green United distributed GREEN tokens created months after they sold the hardware, merely to maintain the illusion of a mining operation. The devices were in fact Bitcoin mining rigs, and they never transferred the mined Bitcoin to investors. The fraudulent nature of the operation only became clear when investors realized that the returns promised in GREEN tokens had no real value.

Legal Ruling: A Precedent for Crypto Enforcement

In a ruling issued on September 23, 2024, U.S. District Judge Ann Marie McIff Allen denied the defendants’ motion to dismiss. The judge established that the SEC had sufficiently demonstrated that the sale of Green Boxes could qualify as securities under U.S. law. The defendants argued that the SEC had overreached and lacked jurisdiction over digital assets, but the court rejected these arguments. The judge underscored that the SEC’s enforcement action was well within the regulatory framework that Congress established nearly a century ago.

This ruling is significant. It confirms that the SEC can regulate the sale of crypto-mining hardware as security if linked to an investment contract promising returns. The court’s decision adds to the growing legal precedent reinforcing the SEC’s authority over digital assets and the crypto industry.

Broader Implications for Investors and the Crypto Industry

The SEC’s victory in this case highlights the risks that crypto investors face when participating in opaque or overly complex investment schemes. Promises of high returns and vague technical claims can often mask fraudulent activities. Investors should be wary of schemes that promise unrealistic profits, particularly in a rapidly evolving market like cryptocurrency.

For the crypto industry, this case sets a legal precedent that could influence future regulatory actions. By classifying Green Boxes as securities, the court reinforces the SEC’s ability to regulate crypto-related investments under existing securities laws. This decision may also have implications for other firms operating in the crypto-mining space. It signals that they too could face regulatory scrutiny if they structure their offerings as investment contracts.

As the case goes to trial, the SEC’s victory against Green United is a milestone in its broader efforts to combat fraud within the cryptocurrency industry. For investors, this ruling underscores the importance of due diligence. For the crypto industry, it signals that greater regulatory oversight is becoming the norm. The Green United case is a clear example of how regulators are stepping up to protect investors from fraudulent schemes.

Readers’ frequently asked questions

Why did the SEC classify Green United’s Green Boxes as securities?

The SEC classified Green United’s Green Boxes as securities based on the Howey Test. This is a legal standard used to determine if an investment qualifies as a security. The key elements of the test are: (1) an investment of money, (2) in a common enterprise, (3) with an expectation of profits, (4) derived from the efforts of others. In this case, investors purchased the Green Boxes with the expectation of significant returns. They were promised up to 50% per month based on the company’s efforts to develop the so-called Green Blockchain and its associated GREEN token. These factors satisfied the criteria for an investment contract under U.S. securities law. That allowed the SEC to regulate the offering and pursue legal action against Green United. The court’s ruling upheld this interpretation. It affirmed that the SEC had sufficiently demonstrated that Green United’s crypto-mining scheme met the necessary criteria​.

What are the implications of this ruling for legitimate cryptocurrency mining operations?

The court’s decision in the Green United case affirms that the sale of the company’s Green Boxes constituted a securities offering. However, it is important to note that this ruling in favor of the SEC does not classify all crypto-mining operations as securities. The fraudulent nature of Green United’s scheme was central to the court’s decision. They promised returns from a non-existent token and blockchain. Legitimate crypto-mining companies selling hardware without making deceptive claims about token value or guaranteed profits are unlikely to face the same regulatory scrutiny. This ruling primarily reinforces the notion that the sale of mining equipment can be regulated as a security if it is marketed as part of an investment contract​.

What should investors watch out for when evaluating cryptocurrency investment opportunities?

Investors should be cautious when evaluating cryptocurrency investment opportunities, particularly those that promise high returns with little explanation or transparency. In the Green United case, investors were drawn in by promises of large, predictable profits through mining a token that didn’t even exist at the time of the hardware sales. To avoid similar scams, investors should look for key red flags such as vague or exaggerated claims about returns. They should also be cautious of a lack of transparency regarding the project’s technology and an absence of verifiable information about the company or token. Additionally, investors should ensure that the offerings comply with regulatory standards. Companies dealing in securities are required to register with regulatory bodies like the SEC.

What Is In It For You? Action Items You Might Want to Consider

Vet Investment Opportunities with Thorough Due Diligence

Given the fraudulent nature of Green United’s promises of high returns, it’s crucial to conduct thorough research before engaging in any cryptocurrency investment. Look for red flags such as vague explanations about how profits are generated or overly optimistic return projections. Verify that the project or company is transparent about its operations, tokenomics, and regulatory compliance. Use resources like regulatory filings and third-party audits to confirm the legitimacy of the project.

Understand How Securities Laws Apply to Crypto Investments

The SEC’s ruling in the Green United case highlights how crypto-related products can be classified as securities if they involve investment contracts. Traders should familiarize themselves with securities regulations and understand how they might apply to different digital assets or projects. When considering investments in tokens, mining equipment, or staking services, ensure the offering complies with securities laws to avoid legal risks and potential losses due to regulatory actions.

Diversify Your Portfolio to Manage Risk

The Green United case serves as a reminder of the risks associated with high-return promises in cryptocurrency. As a trader, it’s important to diversify your investments across different asset classes and risk profiles. Avoid overexposure to any single project or type of asset. By spreading your investments across more stable cryptocurrencies and blockchain-related projects with a solid track record, you can better manage risk and protect your portfolio from the impact of fraudulent schemes.
PayPal Expands Crypto Integration: A Strategic Move to Dominate the Blockchain Landscape

PayPal expands crypto services for U.S. merchants, enabling them to buy, hold, sell, and transfer digital assets.

PayPal’s latest crypto expansion signals the payment giant’s growing ambition in the blockchain space. By enabling U.S. business accounts to buy, hold, sell, and transfer cryptocurrencies, PayPal is positioning itself as a pivotal player in the digital currency ecosystem. This move follows the launch of its stablecoin, PayPal USD (PYUSD), and ongoing integration with multiple blockchain networks, underscoring the company’s broader strategy to lead the fintech revolution. But will this shift be enough to maintain PayPal’s dominance in an increasingly competitive crypto landscape?

Expanding Utility for U.S. Merchants

On September 25, 2024, PayPal announced that U.S. merchants can now manage cryptocurrencies directly from their business accounts. This new functionality allows business owners to buy, hold, and sell digital currencies like Bitcoin and Ethereum. They will also be able to transfer crypto externally to third-party wallets. This expansion mirrors services already available to individual users on PayPal since 2020. It’s a critical step toward enhancing the utility of cryptocurrencies for businesses.

By offering crypto services to business accounts, PayPal seeks to meet increasing demand from merchants looking to participate in the growing crypto economy. U.S. merchants, except those in New York due to regulatory restrictions, can now seamlessly integrate digital assets into their operations. They can manage cryptocurrency alongside traditional payment methods.

Building on a Strong Foundation

This move aligns with PayPal’s broader blockchain strategy, which began in 2020 when the company first allowed consumers to engage with cryptocurrencies on its platform. In 2023, PayPal took another leap forward by launching its own U.S. dollar-pegged stablecoin, PayPal USD (PYUSD), issued by Paxos Trust Company. The stablecoin is fully backed by U.S. dollar deposits and is now supported on multiple blockchains, including Solana. PYUSD’s integration with PayPal’s Xoom service also enables fee-free international money transfers when using the stablecoin. It showcases the company’s commitment to advancing financial inclusion.

The ability for businesses to use PYUSD and other cryptocurrencies opens up new opportunities for cost-effective cross-border transactions, especially for small and medium-sized enterprises (SMEs). Furthermore, PayPal integration with multiple blockchains gives merchants flexibility and control over how they manage their crypto assets, signaling PayPal’s ambition to leverage the best of decentralized finance (DeFi).

A Strategic Gamble in a Competitive Landscape

While PayPal’s move into business crypto accounts is significant, it is not without challenges. The company faces stiff competition from established crypto exchanges such as Coinbase, Kraken, and Binance. These exchanges offer more comprehensive crypto services and are deeply integrated into the blockchain ecosystem. They give businesses and consumers greater control over their digital assets through decentralized wallets and smart contracts.

Moreover, traditional financial institutions, sensing the growing interest in digital currencies, are increasingly offering their own blockchain solutions. For instance, Mastercard and Visa have developed crypto-related services catering to businesses. That is a highly competitive market for PayPal to navigate.

Despite this, PayPal’s unique position as a globally trusted payment platform offers it a distinct advantage. It integrated cryptocurrency services into its familiar and widely used interface, lowering the entry barriers for merchants who may be hesitant to engage with newer, less established platforms. Additionally, it can provide both centralized services and decentralized financial tools, such as on-chain crypto transfers. That allows PayPal to cater to a diverse range of business needs.

What Lies Ahead for PayPal

PayPal venturing into crypto for businesses could solidify its leadership in the fintech space, especially as more merchants look to adopt cryptocurrencies and businesses seek to integrate crypto as a payment method. Maintaining a competitive edge will require further innovation from PayPal. In particular, the company must focus on providing more DeFi-related services that give merchants greater autonomy over their digital assets.

PayPal’s continuous investments in the blockchain space are evident through initiatives like integrating PYUSD into the Solana network. Adding Ethereum Name Service (ENS) for easier crypto transactions further highlights the company’s commitment to expanding its crypto footprint. Whether this will be enough to fend off competition from crypto-native platforms remains to be seen. However, PayPal’s efforts to blend the worlds of traditional finance and blockchain technology are undoubtedly reshaping the payments landscape.

PayPal’s latest crypto expansion for business accounts is a strategic step toward consolidating its role in the rapidly evolving digital currency ecosystem. By offering centralized and decentralized features, PayPal positions itself as a versatile platform, capable of meeting the needs of businesses looking to engage with crypto. Yet, in a fiercely competitive market, PayPal must keep innovating to retain its edge and become a dominant force in the blockchain space.

Readers’ frequently asked questions

Why did PayPal extend crypto services to business accounts, and how does this benefit merchants?

PayPal’s extension of crypto services to business accounts responds to increasing demand from merchants for digital currency capabilities. Since its initial crypto offering for consumers in 2020, businesses have sought similar tools to manage and transact with cryptocurrencies. This move benefits merchants by streamlining crypto transactions within the familiar PayPal ecosystem. It makes it easier for businesses to integrate digital currencies into their payment flows. Merchants can use cryptocurrencies for various purposes. They can accept payments from crypto-savvy customers, diversify their payment options, or engage in cross-border transactions more efficiently. Additionally, PayPal’s integration with multiple blockchains, such as Solana, allows businesses to benefit from faster, cost-effective transactions, particularly when using PayPal USD (PYUSD) for international transfers.

What specific features make PayPal’s crypto offering appealing to merchants?

Beyond the ability to buy, hold, and sell cryptocurrencies, PayPal offers features designed to make crypto management straightforward for businesses. For instance, U.S. merchants can now transfer cryptocurrencies to third-party wallets, making it easier to move assets into decentralized environments. This flexibility allows merchants to interact with both centralized and decentralized finance (DeFi) ecosystems, opening up new use cases. E.g. they can access liquidity in decentralized exchanges or participate in blockchain-based finance solutions. Moreover, PayPal’s integration of stablecoins like PYUSD enables businesses to use digital currencies for international transfers without the volatility risk typically associated with crypto assets. This feature is especially advantageous for small and medium-sized enterprises (SMEs) that frequently deal with international transactions but want to avoid traditional currency conversion fees​.

How does PayPal plan to evolve its crypto services to remain competitive in the blockchain space?

While PayPal has established itself as a trusted platform for crypto transactions, it must continue innovating to stay competitive in the fast-evolving blockchain space. The company’s current offerings cater to merchants looking for convenience and a smooth transition into digital currencies. However, competitors like Coinbase and Binance offer more advanced tools for managing crypto assets, such as decentralized wallets, staking, and broader token support. To bridge this gap, PayPal may need to expand its DeFi capabilities or explore deeper integrations with decentralized applications (dApps). Furthermore, as regulation around cryptocurrencies continues to develop, PayPal’s ability to navigate these challenges while offering secure, innovative features will be crucial for maintaining its foothold. Ongoing enhancements in blockchain interoperability, such as PYUSD’s availability on multiple chains, suggest that PayPal is positioning itself for greater flexibility and user control over digital assets​.

What Is In It For You? Action Items You Might Want to Consider

Consider Diversifying into Stablecoins Like PYUSD for Cross-Border Transactions

With PayPal’s integration of its stablecoin, PayPal USD (PYUSD), businesses can now leverage a U.S. dollar-pegged crypto asset for international transactions. If you’re trading across borders, using PYUSD could help minimize conversion fees and volatility risks associated with other cryptocurrencies. PayPal’s support for multi-blockchain operations, such as Solana, offers faster and more cost-effective transfers. This makes it a compelling tool for efficient trading. Start exploring how PYUSD might fit into your global strategy for reducing costs and maintaining stable liquidity.

Leverage PayPal’s New On-Chain Transfer Capabilities for Enhanced Flexibility

PayPal now allows merchants to transfer cryptocurrencies to external wallets. This feature could benefit traders by offering more control over their assets. If you’re using DeFi platforms or prefer managing your digital currencies in external wallets, this new capability opens up more possibilities for trading strategies. Consider taking advantage of this on-chain transfer feature to diversify how you store and manage your crypto holdings, especially if you trade across multiple wallets or exchanges.

Monitor Regulatory Updates, Especially if Trading in New York

While PayPal’s new crypto services are accessible to U.S. merchants, they are currently unavailable in New York due to state regulations. If you’re a trader operating in multiple states, it’s essential to stay informed about potential regulatory changes that might impact your ability to use PayPal’s services in New York or other regions with stringent crypto laws. Keep an eye on developments to ensure that you’re positioned to take advantage of new tools as they become available.

SEC Crackdown on Stablecoin Fraud: TrustToken and TrueCoin’s $500M Deception Unveiled

TrustToken and TrueCoin settle with SEC over fraud allegations.

The U.S. Securities and Exchange Commission (SEC) has taken significant enforcement action against the crypto firms TrustToken and TrueCoin. Both companies, once seen as pioneers in the stablecoin market, agreed to settle fraud charges related to misleading claims about the financial backing of TrueUSD (TUSD), their flagship stablecoin. This development is part of the SEC’s growing focus on regulating the cryptocurrency industry, particularly stablecoins, which are increasingly seen as critical to the market’s infrastructure.

The Allegations: Misleading Investors About TUSD Backing

Essentially, the SEC alleged that TrustToken and TrueCoin misled investors. They asserted that TUSD was fully backed by U.S. dollars in a 1:1 ratio, reassuring users of the coin’s stability. After all, stablecoins like TUSD are designed to maintain parity with traditional currencies such as the U.S. dollar. However, the SEC’s investigation revealed a starkly different reality. By 2024, they had funneled nearly 99% of the reserves backing TUSD into a speculative offshore fund.

Despite being aware of these risky investments and potential liquidity issues as early as the fall of 2022, TrustToken and TrueCoin continued to market TUSD as fully backed. They assured investors that the stablecoin remained safe, despite growing internal concerns. Their actions exposed investors to significant risks, contradicting their core marketing claims. That cast doubt on the transparency and security of stablecoin reserves in the broader crypto market as well.

Redemption Issues and Investor Impact

The SEC further disclosed that TUSD operations had been transferred to an offshore entity by March 2022. The funds meant to back the stablecoin were no longer held in U.S. dollars or equivalent assets. Instead, most of these funds were directed into a high-risk offshore investment fund, jeopardizing the ability to redeem TUSD for its advertised value.

In 2023, these issues began to surface publicly when TUSD experienced several de-pegging events. During these events, its value dipped below the $1 mark. The incidents were linked to the underlying instability of the reserves, raising alarms within the crypto community and among regulators. At the time, TrueCoin and TrustToken claimed to be addressing these problems. However, the SEC’s findings show that both companies continued to make false assurances to investors, further worsening the situation.

Settlement with the SEC

As part of the settlement, TrustToken and TrueCoin have agreed to pay civil penalties of $163,766 each. TrueCoin is also required to disgorge $340,930 along with prejudgment interest. The companies settled the case without admitting or denying the charges, a common outcome in SEC enforcement actions. They have also agreed to injunctive relief to prevent future violations of federal securities laws.

This case is notable not just for the financial penalties but also for the legal precedent it sets. The SEC classified the sale of TUSD as involving unregistered securities, pointing to the profit-making opportunities tied to the stablecoin. This aligns with the SEC’s broader strategy of applying securities regulations to certain crypto assets. This strategy has sparked debate in the cryptocurrency industry.

Broader Regulatory Implications

This case highlights the challenges regulators face in maintaining transparency and protecting investors in the rapidly evolving cryptocurrency landscape. Stablecoins have become a fundamental part of the crypto ecosystem. They facilitate trading, lending, and other financial services but are now under increased scrutiny. The SEC’s actions signal that even well-established projects like TUSD are not immune to enforcement if they fail to maintain transparency and adhere to regulatory requirements.

For the crypto industry, this case emphasizes again the importance of clear regulatory guidelines and the need for companies to comply with securities laws when offering digital assets. As the SEC continues to define its regulatory framework for cryptocurrencies, more enforcement actions against stablecoins and other crypto assets are likely on the horizon.

The settlement between the SEC, TrustToken, and TrueCoin sends a strong message to the crypto industry about the importance of transparency, investor protection, and regulatory compliance. While TUSD’s fall from grace highlights the risks associated with stablecoins, the broader market will be watching closely to see how this case impacts future regulatory decisions and the evolving landscape of digital assets.

As stablecoins remain integral to the functioning of the crypto market, ensuring they are backed by transparent and secure reserves is crucial to maintaining investor trust and market stability.

Readers’ frequently asked questions

What specific role did the speculative offshore fund play in the SEC’s case against TrustToken and TrueCoin?

The speculative offshore fund is central to the SEC’s fraud charges against TrustToken and TrueCoin. These companies misled investors by claiming that TrueUSD (TUSD) was fully backed by U.S. dollars or equivalent assets, which would ensure that each TUSD could be redeemed for one dollar. However, the SEC found that by 2024, nearly 99% of the reserves supposedly backing TUSD were placed in a risky offshore investment fund rather than in safe, liquid assets like cash or equivalents. This fund was intended to generate higher returns but ultimately exposed TUSD holders to substantial risk without their knowledge. The companies continued promoting TUSD as fully backed, even though they knew about the internal problems with liquidity and redemption by late 2022.

What does this case imply for the classification of stablecoins like TrueUSD as securities?

The SEC’s case against TrustToken and TrueCoin reinforces its position that certain digital assets, including stablecoins, may be classified as securities. According to the SEC’s findings, TUSD was sold with profit-making opportunities. Hence, the companies’ activities met the criteria outlined in the Howey Test – a legal framework used to determine whether a transaction qualifies as an “investment contract” and therefore a security. Specifically, investors were led to believe that they were participating in a common enterprise (TUSD) with the expectation of profit (from the stability and backing of the coin). This classification of TUSD as a security underlines the growing scope of the SEC’s oversight in crypto markets. It also suggests that other stablecoins with similar structures could be subjected to securities laws, too​.

How will this settlement affect the broader stablecoin market?

The settlement between the SEC, TrustToken, and TrueCoin has broader implications for the stablecoin market. The case highlights the need for transparency on the backing of stablecoins. They must comply with existing securities laws. Stablecoins play a crucial role in the cryptocurrency ecosystem, facilitating trading, lending, and financial transactions. However, discovering that TUSD reserves were improperly managed may lead to greater regulatory oversight of other stablecoins, especially regarding reserve transparency and stability assurances. This could prompt stablecoin issuers to adopt more stringent practices to avoid regulatory actions. Ultimately, this can make the market safer for investors but potentially limits the issuers’ flexibility in managing their reserves.

What Is In It For You? Action Items You Might Want to Consider

Evaluate the Stability and Transparency of Stablecoins Before Trading

Given the SEC’s findings on TUSD’s misleading claims about its backing, it’s crucial to scrutinize any stablecoin’s reserve practices before incorporating them into your portfolio. Look for assets with clear, independently audited reserves, and avoid stablecoins tied to offshore funds or speculative assets. This will help minimize your exposure to sudden de-pegging events and liquidity issues, which can severely impact your capital.

Stay Updated on Regulatory Changes Affecting Stablecoins

The SEC’s actions against TrustToken and TrueCoin could lead to tighter regulatory oversight of the stablecoin market. As a trader, keep an eye on new rules or enforcement actions targeting stablecoins and other crypto assets. Regulatory shifts can significantly affect liquidity, trading pairs, and market perception of specific coins. That influences their short-term and long-term performance.

Diversify Stablecoin Holdings to Mitigate Risk

Given the risks highlighted in this case, including the possibility of misleading claims about backing, it may be wise to diversify your stablecoin holdings across multiple issuers. While stablecoins are designed to maintain parity with traditional currencies, issues with reserves can lead to temporary or prolonged losses in value. Spread your holdings across multiple stablecoins with verified backing. It will reduce the risk of a single issuer’s failure affecting your entire portfolio.

Binance Distances Itself as WazirX Faces Crypto Hack Fallout and Court-Ordered Restructuring

WazirX faces recovery challenges after a $235M hack, while Binance distances itself from involvement in the ongoing crisis.

In the wake of a $235 million cyberattack, the Singapore high court granted Indian crypto exchange WazirX a four-month moratorium, providing temporary legal protection as it scrambles to address the crisis. The hack targeted WazirX’s multi-signature wallet in July 2024. It was the second-largest crypto breach this year and left thousands of users in financial uncertainty. The court’s decision allows WazirX time to implement a restructuring plan and disclose its financial records while fending off creditors.

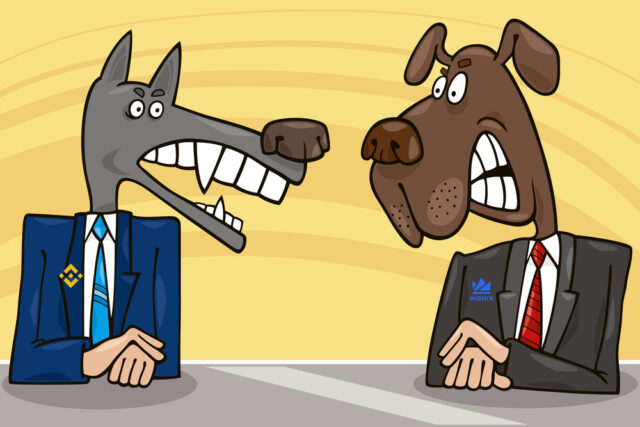
At the heart of the situation is the ongoing dispute between WazirX and Binance, the world’s largest cryptocurrency exchange by trading volume. Binance, previously linked to WazirX through a 2019 acquisition announcement, has forcefully denied any involvement or responsibility for the breach.

Binance’s Response to the Hack

In response to claims that Binance should bear some responsibility, Binance CEO Changpeng Zhao (CZ) has consistently maintained that Binance never actually owned or operated WazirX. Despite earlier suggestions of an acquisition, Binance clarified that the parties never fully completed the deal because WazirX failed to meet certain contractual obligations. “Binance has not owned, controlled, or operated WazirX at any time, including before, during, or after the July 2024 attack,” Binance stated in a public release.

Binance emphasized that its relationship with WazirX was limited to providing wallet infrastructure. They ceased offering the service in early 2023. Zhao criticized WazirX for misleading its users by implying that Binance had operational control. Tensions now escalated as WazirX founder Nischal Shetty suggests Binance’s involvement hindered efforts to compensate users.

https://twitter.com/cz_binance/status/1555578415901802507
https://twitter.com/NischalShetty/status/1828057627240305112

WazirX’s Defense and Legal Strategy

WazirX’s management, however, paints a different picture. According to Shetty, Binance’s technical integration played a significant role in managing WazirX’s funds before the hack. He suggested that Binance holds partial responsibility for user losses. He pointed out that Binance controlled the bulk of WazirX’s assets up until 2023. In his view, this complicated WazirX’s ability to compensate users following the cyberattack.

In response to the hack, WazirX sought protection from the Singapore High Court under Section 64 of the Insolvency, Restructuring, and Dissolution Act (IRDA). The court granted WazirX a four-month moratorium. During this period it must reveal its financial details, including wallet addresses, and establish a transparent restructuring plan. This should allow WazirX to develop a recovery proposal with input from its creditors, ensuring any voting is conducted through independent third parties.

The Broader Implications for the Crypto Space

The dispute between Binance and WazirX brings to the fore questions about transparency and accountability within the crypto sector. Binance’s decision to distance itself from WazirX is a critical development. It underscores the challenges of operational clarity in decentralized financial ecosystems. Users and creditors are now caught in the crossfire of this corporate battle, uncertain about the future of their funds.

While WazirX focuses on recovering from the breach, Binance’s firm denials left WazirX with fewer avenues for relief. Currently, trading remains suspended, but INR withdrawals have resumed in phases. However, users can withdraw only up to 66% of their balances. Cryptocurrency withdrawals are still on hold until a court-approved restructuring scheme is finalized. This uncertainty leaves users waiting for further resolution. In the meantime, the hacker has reportedly laundered most of the stolen funds using privacy tools like Tornado Cash.

Looking Forward

The coming months will be pivotal for WazirX as it seeks to regain stability and compensate affected users. The court-mandated restructuring plan offers a glimmer of hope, but much depends on whether WazirX can successfully navigate its financial challenges and the growing legal complexities of its dispute with Binance. For now, users are left waiting, with their trust in the platform — and the broader crypto ecosystem — severely tested.

As the crypto industry matures, these types of conflicts will likely shape the regulatory landscape, with increasing calls for transparency in partnerships, ownership structures, and user agreements. For WazirX, the court ruling offers temporary relief, but the path to recovery remains fraught with challenges.

Readers’ frequently asked questions

What is the status of the stolen funds from the WazirX hack, and is there any chance of recovery?

As of now, a significant portion of the stolen $235 million in crypto assets has been laundered through privacy tools, such as Tornado Cash. These platforms are designed to obscure the origin and movement of digital assets, complicating efforts to trace and recover stolen funds. WazirX expressed doubts about whether they will be able to recover all the lost assets. Estimates suggest that only 55-57% of the funds might be potentially recoverable. The legal advisors working with WazirX have pointed out that the stolen assets have been rapidly dispersed. That makes it difficult to regain them through traditional legal channels. Although WazirX has committed to a restructuring plan that could involve compensating users, the extent of that compensation remains uncertain as the platform seeks legal and financial resolutions through the courts.

Why is Binance distancing itself from WazirX, and how does it impact users?

Binance’s public distancing from WazirX stems from an unresolved acquisition dispute. In 2019, Binance announced its intent to acquire WazirX. However, in 2022, Binance’s CEO Changpeng Zhao (CZ) clarified that the acquisition was never completed because WazirX failed to meet certain contractual obligations. Since then, Binance has been firm in stating that it does not own or control WazirX. This counters claims from WazirX’s founder, Nischal Shetty, who suggested that Binance still played a role in handling WazirX’s funds before the hack. Binance’s stance has significant implications for WazirX users. It absolved itself of any responsibility for compensating users affected by the hack. This leaves WazirX solely responsible for managing the aftermath, adding to user uncertainty. Binance’s decision to distance itself further complicates WazirX’s efforts to recover and stabilize. Binance had previously provided technical services, including wallet infrastructure, but these ceased in early 2023.

What will happen during WazirX’s court-mandated restructuring, and what does it mean for users?

WazirX’s four-month moratorium granted by the Singapore High Court should provide the exchange with temporary relief from legal actions and creditor claims, giving it time to develop a recovery plan. During this period, WazirX must take several key steps, including disclosing its wallet addresses and full financial accounts. It will also need to present a transparent plan for how it intends to compensate users and manage its outstanding liabilities. The restructuring plan, which will involve voting by creditors, must be approved by the court before any funds can be disbursed to users. While this court protection gives WazirX some breathing room to organize a fair resolution, it also means users will have to wait before any asset recovery. This process will likely take several months. Trading on the platform remains suspended, which increases uncertainty for users. It is unclear when or how they will regain access to their funds.

What Is In It For You? Action Items You Might Want to Consider

Monitor WazirX’s restructuring developments closely before making any major trading decisions

With the Singapore court granting a four-month moratorium to WazirX, it’s essential to stay informed about any updates related to their restructuring plan. The outcome of this process will directly affect the platform’s recovery efforts, user compensation, and future trading activity. Keep an eye on official communications from WazirX and the Singapore courts to gauge when trading might resume and whether it’s safe to reinvest or withdraw.

Diversify your holdings across multiple exchanges to mitigate risk

The ongoing dispute between WazirX and Binance highlights the uncertainty that can arise from partnerships and acquisitions within the crypto space. To avoid being caught in similar situations, traders should diversify their funds across multiple reputable exchanges. Doing so reduces exposure to risks such as platform shutdowns, hacks, or unresolved ownership issues that could lock up your assets.

Be cautious of exchanges under financial or legal distress

As WazirX goes through a court-ordered restructuring, it’s wise to be cautious about interacting with platforms facing financial instability. Even if an exchange resumes trading, consider withdrawing or limiting your funds until you’re confident that it has resolved its issues. Keep track of how WazirX handles user compensation post-hack. This can provide insight into its reliability and the broader risks associated with such platforms.

Bank of Canada Shelves Digital Loonie Plans Amid Privacy Concerns and Public Backlash

Bank of Canada Pauses Digital Loonie Plans Over Privacy Concerns

After years of research and public consultations, the Bank of Canada has announced a pause in its plans to introduce a Central Bank Digital Currency (CBDC), commonly referred to as the “digital loonie.” The decision comes after an extensive public consultation revealed significant opposition to the idea. Nearly 90% of respondents expressed concerns primarily about privacy and cybersecurity. While countries like China and Nigeria are forging ahead with their CBDC projects, Canada has opted for a more cautious path. It will prioritize the improvement of its broader payment systems instead of launching a digital currency.

A Shift in Focus: Public Concerns Take Center Stage

The Bank of Canada’s decision to shelve its digital loonie project is largely attributed to the findings of a public consultation conducted in 2022 and 2023. Nearly 90,000 Canadians participated in the survey, and the results were clear: most respondents were wary of a CBDC. Among the primary concerns raised were privacy, cybersecurity, and the need for such a digital currency in a landscape where existing payment methods, like debit cards and mobile banking, already function effectively. A staggering 87% of participants said they would never use a digital Canadian dollar, while 92% indicated they preferred existing payment methods.

This public sentiment has become a key factor in the Bank of Canada’s decision to hit pause on the CBDC initiative. Governor Tiff Macklem emphasized that while the central bank has accumulated valuable research on the subject, there is currently no compelling case to move forward with the retail digital currency. Instead, the bank will redirect its focus to policy development and research surrounding Canada’s broader payment systems. They want to ensure that these systems remain modern and secure in an increasingly digital economy.

The Global Context: A Divergence from International Trends

The decision to step back comes at a time when many central banks around the world are accelerating their own CBDC projects. China’s digital yuan pilot program, for instance, is one of the most advanced. It has processed nearly $1 trillion in transactions as of mid-2024. Smaller nations like the Bahamas and Nigeria have fully launched their digital currencies and are expanding their use. As of September 2024, over 130 countries are either exploring or actively developing CBDCs.

Canada’s choice to hold off on a retail CBDC stands in contrast to these global developments. However, this decision doesn’t mean that the digital loonie is permanently off the table. The Bank of Canada has stated that it will continue to monitor global CBDC initiatives. It will be ready to act if the need arises in the future. The extensive research conducted over the past several years will serve as a foundation should the bank revisit the idea of a digital currency later on.

Privacy vs. Innovation: The Core of the Debate

At the heart of the Canadian public’s opposition to the CBDC lies the issue of privacy. Many Canadians fear that a government-issued digital currency could open the door to increased surveillance, particularly regarding personal financial transactions. This concern is not unique to Canada; debates over privacy have surfaced in many countries considering CBDCs. Critics argue that such currencies could grant governments unprecedented insight into citizens’ spending habits.

On the flip side, proponents of CBDCs argue that digital currencies offer several advantages. They improve financial inclusion, expedite cross-border payments, and reduce reliance on private payment platforms. Moreover, some central banks, including those in the Eurozone, have pointed to the need for sovereign digital currencies to counterbalance the growing influence of private cryptocurrencies and stablecoins. They believe these currencies pose potential risks to monetary sovereignty.

In Canada’s case, the Bank of Canada has chosen to focus on strengthening its payment systems rather than rushing to adopt a digital loonie. The bank will continue its research into the broader payments ecosystem, including cross-border payments and policies related to wholesale financial infrastructure. This pragmatic approach reflects a broader debate about whether digital innovation should prioritize privacy or if the potential benefits of a CBDC outweigh these concerns.

A Pause, Not an End

While the Bank of Canada has paused its CBDC project, this decision represents more of a recalibration than an outright rejection. With privacy concerns front and center, the bank is taking time to reassess the necessity and viability of a digital loonie. In the meantime, it will focus on keeping Canada’s financial infrastructure secure and adaptive to future needs. As CBDC developments continue globally, Canada will keep a close eye on international trends. It remains ready to re-enter the conversation if the landscape – and public sentiment – changes.

This decision underscores the complex trade-offs between privacy and innovation, a balancing act that will define the future of digital currencies worldwide.

Readers’ frequently asked questions

Why are Canadians concerned about privacy with a digital loonie?

Canadians are particularly concerned that a digital loonie could compromise personal privacy by allowing the government to track their financial activities. Unlike cash, which is anonymous, a digital currency would create a traceable record of every transaction. The public worries about how this data could be used and whether it could lead to surveillance of their spending patterns. Additionally, many are skeptical of the Bank of Canada’s ability to safeguard against cyber threats. In the public consultation, 87% of respondents expressed concerns about data security and the risk of hacking. This widespread apprehension reflects not only a desire for privacy but also a lack of trust in digital infrastructure to protect sensitive financial information

What specific benefits could a digital loonie offer that current payment systems do not?

A digital loonie could provide several advantages, especially in areas where current systems fall short. For one, it could promote financial inclusion, providing people without access to traditional banking services a reliable means to participate in the digital economy. This is particularly relevant for remote or underserved communities. Another benefit could be reducing costs and time for cross-border payments, which are often slow and expensive under existing systems. A CBDC would allow faster, cheaper transfers by cutting the need for intermediaries like banks. Additionally, a digital loonie could help Canada retain monetary sovereignty in the face of competition from cryptocurrencies and foreign digital currencies, ensuring that Canadian dollars remain a stable and trusted medium of exchange in the digital age.

However, while these benefits are appealing in theory, the Bank of Canada has deemed that they do not outweigh the concerns or the current effectiveness of Canada’s financial system. The bank’s decision reflects the view that a CBDC may not be essential at this stage.

Will Canada reconsider a CBDC in the future?

Yes, the Bank of Canada’s decision to halt the digital loonie project is not final. The bank has emphasized that the research and development done so far will remain valuable if the need for a digital currency arises in the future. Canada will continue to monitor global developments in CBDCs, particularly as other countries push forward with their digital currency projects. The central bank remains ready to respond if public sentiment shifts or if technological advancements make a stronger case for a digital loonie. For now, the focus is on modernizing and securing the existing payment system, but the door remains open to revisiting the CBDC discussion if conditions change.

What Is In It For You? Action Items You Might Want to Consider

Stay Informed on CBDC Developments Globally

While the Bank of Canada has put the digital loonie on hold, other countries, such as China and Nigeria, are forging ahead with their digital currencies. Keeping an eye on the global adoption of Central Bank Digital Currencies (CBDCs) can offer insights into how these innovations may impact international markets and the future of cryptocurrencies. This could present potential trading opportunities in regions where CBDCs are gaining traction or create new trends for the broader digital currency market​.

Hedge Against Market Volatility with Stablecoins

Given that Canada has paused its digital loonie project, it’s clear the country is taking a more conservative approach to digital currency adoption. Traders might consider balancing their portfolios by incorporating stablecoins, which offer the benefits of digital currencies without the volatility seen in cryptocurrencies like Bitcoin or Ethereum. Stablecoins tied to fiat currencies can provide a hedge against market swings, especially as countries like Canada reassess their CBDC strategies​.

Explore Cross-Border Payment Opportunities

One key area where a CBDC could have made an impact is cross-border payments. With Canada’s delay, traders should explore existing platforms that offer efficient cross-border solutions. Blockchain technologies like Ripple or Stellar, which specialize in fast, low-cost international transactions, can fill the gap left by the digital loonie’s absence. Staying ahead of evolving payment systems could help traders optimize transaction fees and timing.

- Advertisement -

FEATURED