Home Blog Page 97

SEC Flip-Flop on Bitwise Crypto ETF Sparks Market Confusion and Legal Scrutiny
U.S. government official pressing a red pause button labeled “ETF Approval” during SEC meeting, with documents marked “Bitwise,” “Rule 431,” and “Crypto ETFs” on the table.

The U.S. Securities and Exchange Commission (SEC) stunned markets this week with a dramatic about-face. After approving Bitwise’s long-anticipated crypto ETF conversion, the agency abruptly hit pause, just hours later. The move has left investors baffled, analysts frustrated, and legal experts dissecting the SEC’s opaque regulatory process, especially regarding Rule 431. At stake is not only the fate of the Bitwise crypto ETF but also the broader credibility of the SEC’s crypto oversight framework.

A Fast-Track Approval Followed by a Sudden Stall

Bitwise had received accelerated approval to convert its $1.68 billion crypto index fund into a spot ETF. This new ETF would allow investors exposure to a diversified basket of digital assets, including Bitcoin (BTC), Ethereum (ETH), XRP, and a range of altcoins. The market saw the approval as a breakthrough for the crypto ETF sector, especially amid growing institutional interest.

But in a stunning reversal, the SEC halted the approval just hours later. Effectively, it froze the Bitwise crypto ETF conversion before it could proceed. The agency issued no clear public explanation. However, sources close to the matter point to procedural concerns under Rule 431, which governs the review and suspension of prior decisions.

Markets React and XRP Takes a Hit

News of the Bitwise ETF pause reverberated through crypto markets. XRP, one of the core assets in the proposed ETF, saw a steep 6% price drop within hours. Traders scrambled to assess whether the SEC’s action signaled deeper regulatory hostility toward altcoin exposure or merely internal disorganization.

Investor sentiment also took a hit. The move sparked confusion and concern across the market, with analysts questioning the SEC’s transparency and decision-making process. Trading desks and social media platforms echoed similar sentiments.

Rule 431: The Procedural Brake Behind the Pause

At the heart of the confusion is Rule 431 SEC. This internal provision allows the agency to suspend decisions it deems to have been made in error or without full procedural compliance. While Rule 431 is not new, its application in active ETF approvals is rarely invoked in such a public and disruptive way.

Importantly, the Bitwise decision mirrors what occurred earlier this month with Grayscale’s Digital Large Cap Fund (GDLC). The SEC approved the multi-asset crypto ETF conversion on July 1, only to subsequently pause the approval shortly after. These back-to-back reversals suggest a broader procedural shift within the SEC’s handling of multi-asset crypto ETFs.

Transparency on Trial: What’s at Stake

The SEC halting Bitwise’s ETF has reignited criticism of the agency’s regulatory approach to crypto. Critics argue that such erratic behavior not only stifles innovation but also opens the door to perceptions of bias or inconsistency, especially when no detailed rationale accompanies a major decision.

Analysts also worry about the chilling effect this could have on other pending crypto ETF applications. If Bitwise, one of the most compliance-forward asset managers in the space, can be blindsided, what does that mean for others?

Moreover, questions linger about whether this action bears political motivations or if someone contested it internally. Regardless of intent, the optics are poor: the SEC appears divided, opaque, and unreliable in its treatment of crypto assets.

What’s Next for Bitwise?

Bitwise has not issued a formal statement beyond acknowledging the pause. Insiders suggest the firm may appeal or refile, though the lack of public SEC guidance complicates that path.

In the meantime, the paused ETF remains in limbo, and so does investor confidence in SEC crypto regulation. The reversal may also delay broader adoption of altcoin ETF approval efforts, particularly those including tokens like XRP, which already carry regulatory baggage.

Conclusion: Repercussions Far Beyond Bitwise

This isn’t just a procedural hiccup. It’s a growing trend of regulatory whiplash within the SEC. The agency’s decision to greenlight and then immediately halt the Bitwise crypto ETF, just weeks after doing the same with Grayscale’s GDLC, raises serious questions about due process, regulatory transparency, and the future of digital asset exposure in mainstream financial markets.

Until clearer answers emerge, the crypto industry is left grappling with a familiar foe: uncertainty.

Readers’ frequently asked questions

What is Rule 431, and how does it affect ETF approvals?

Rule 431 is an internal SEC procedure that allows the Commission to stay or suspend its own actions if they are later deemed to have been made in error or without full procedural review. In the Bitwise case, it was reportedly used to pause the ETF approval hours after it was granted.

Can the paused Bitwise crypto ETF still launch later?

Yes. A paused approval under Rule 431 does not mean permanent rejection. Bitwise may refile, respond to procedural concerns, or appeal the decision. However, until the SEC issues further clarification on its ETF reversal, the launch is on hold indefinitely.

What makes a crypto ETF “multi-asset,” and how is it different from a Bitcoin-only ETF?

A multi-asset crypto ETF holds a basket of cryptocurrencies, such as Bitcoin, Ethereum, XRP, and others, rather than just Bitcoin. This allows investors to gain broader exposure to the crypto market in a single fund. In contrast, a Bitcoin-only ETF tracks the performance of Bitcoin alone.

What Is In It For You? Action items you might want to consider

Monitor SEC Commission review decisions under Rule 431

Investors and fund managers should track developments around Rule 431 reviews, especially in cases where staff approvals are paused. These actions could delay or derail ETF launches with little notice.

Reassess ETF exposure to multi-asset crypto funds

Given the regulatory volatility, investors considering exposure through multi-asset ETFs like Bitwise or Grayscale GDLC should reevaluate their timelines and risk assumptions.

Follow SEC guidance on delegated authority procedures

Legal and compliance teams at financial institutions should stay updated on SEC guidance regarding staff-level authority and potential for reversals. Internal investment decisions should factor in these regulatory dynamics.

Explainer: What Is Rule 431 and How Does SEC Delegated Authority Work?

Rule 431 of the SEC’s Rules of Practice allows the Commission to review and potentially reverse decisions made by its staff under delegated authority. Specifically, Rule 431(e) enables an automatic stay on a staff-approved action, such as an ETF approval, if a Commissioner requests full Commission review.

This was the basis for the rapid SEC reversal of Bitwise’s and Grayscale’s crypto ETF conversions in July 2025. In both cases, the Division of Trading and Markets initially approved the ETFs, but the Commission stayed those approvals under Rule 431, halting their progress.

The SEC’s Rules of Practice also include a detailed delegation framework (outlined in 17 CFR § 200.30‑1 through § 200.30‑18), which assigns specific powers to various staff roles. These rules streamline decision-making while preserving the Commission’s ability to intervene when necessary, though this dual structure has recently led to abrupt and confusing SEC policy reversals in the crypto ETF space.
Is the Digital Pound Dead? Inside the Bank of England’s Sudden Shift

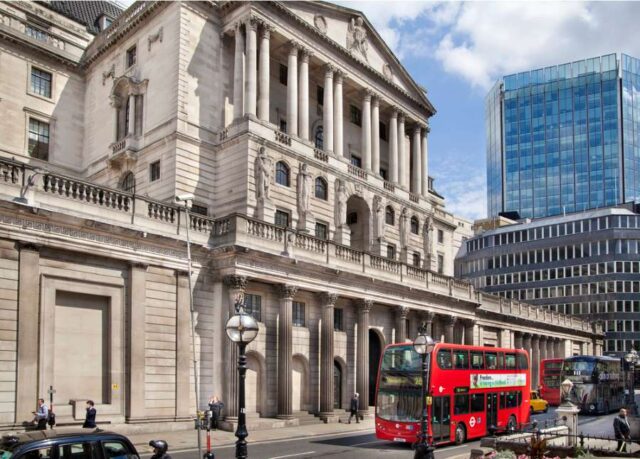
Photograph of the historic Bank of England building in London, with double-decker buses passing by — symbolizing the central bank’s role in shaping UK financial policy and the future of the digital pound.

The digital pound, once hailed as a cornerstone of the UK’s financial modernization, is now facing an uncertain future. The Bank of England CBDC initiative has already cost taxpayers nearly £24 million. But political pressure, public skepticism, and competition from the private sector are pushing the central bank to reconsider. As other central banks begin to slow their digital currency efforts, the UK’s central bank digital currency project risks becoming obsolete.

Mounting Political and Public Resistance

Public support for a digital pound has declined sharply in recent months. Further, lawmakers from multiple parties have concerns over the necessity and implications of the project. One major criticism centers on surveillance and financial privacy. A programmable CBDC could give the government excessive control over how people spend their money. That fear has fueled growing public opposition to CBDCs in the UK.

The BoE has acknowledged that public trust remains a major hurdle. Consultations revealed deep privacy concerns about digital currency in the UK, with respondents questioning the need for a government solution that replicates existing services.

Strategic Pause: Is the £24 Million Justified?

With nearly £24 million already spent, the Bank of England CBDC project is under increasing scrutiny. Critics argue there is still no clear use case for a central bank digital currency in the UK. Building and securing the required infrastructure would also involve considerable investment and time.

Although the Bank of England insists the initiative is only being reassessed, many observers believe it is a step to quietly abandon the CBDC project. The lack of urgency aligns with a broader shift. Central bank digital currency is no longer viewed as inevitable or essential by many policymakers.

Private Sector Leapfrogs Central Banks

One of the most compelling reasons for the Bank of England’s hesitation to advance its own CBDC project is the rise of private sector innovation in payments. Fintech platforms and stablecoins are already delivering fast, low-cost, and borderless solutions. These options often provide better user experience and fewer barriers than central bank alternatives.

The UK fintech scene has evolved rapidly. As a result, stablecoin adoption is a practical substitute for a state-backed system. Analysts argue the BoE risks stifling innovation if it chooses to compete rather than regulate. In that context, the real debate is no longer cash versus CBDC, but stablecoins versus CBDCs.

The Global Pullback: Fading Hype Around CBDCs

The UK is not alone in hitting the brakes on the digital pound. Canada and Australia have already slowed their digital currency efforts. Even the European Central Bank is showing signs of hesitation.

This global cooling trend has reshaped expectations for central bank digital currency in 2025. What once looked like a digital arms race now resembles a coordinated retreat. Cost, complexity, and competition from private providers have all played a role in that shift.

What Comes Next for the UK and CBDCs?

No final decision has been made. The digital pound project is still technically alive, but on hold. The Bank of England CBDC team will continue its research and consultations. However, the momentum has clearly stalled.

Experts say the BoE might choose to regulate stablecoins rather than build its own system. This would allow it to shape the future of money without slowing private sector innovation in payments. In this new reality, stablecoins vs CBDCs isn’t just a technical distinction. It’s a fundamental policy question.

The digital pound once promised to redefine how money works in the UK. Now, it reflects a broader uncertainty about the role of central banks in a digitized financial system. As the Bank of England CBDC enters a phase of reevaluation, the private sector charges ahead. Whether the UK builds or regulates the future of digital finance, one thing is clear: the status quo is changing fast.

Readers’ frequently asked questions

Is the digital pound officially cancelled?

No. The Bank of England has not officially cancelled the digital pound project. However, it has signaled a strategic pause and is reevaluating its necessity, citing public concerns and the evolving financial ecosystem.

Can UK consumers currently use any form of CBDC or digital pound?

No. There is no live CBDC or digital pound available to UK consumers. All activity to date has been limited to research, consultation, and pilot phases. Consumers continue to rely on traditional banking and private fintech alternatives.

What role will the Bank of England play if stablecoins replace the need for a CBDC?

The Bank of England may take on a regulatory role instead of issuing its own digital currency. It could supervise and license stablecoin providers to ensure financial stability and consumer protection, especially if such instruments become widely used.

What Is In It For You? Action items you might want to consider

Monitor the Bank of England’s updates on the digital pound

Although the project is paused, the BoE may resume or reshape its CBDC strategy in the future. Follow official communications, public consultations, and research releases to stay informed about any policy shifts.

Evaluate stablecoin options for digital payments

With no live UK CBDC available, consumers and businesses interested in digital currency applications should explore regulated stablecoins for domestic and cross-border payments. Assess providers based on transparency, licensing, and interoperability with existing systems.

Assess policy impact on fintech investments

Investors and financial analysts should consider the implications of the BoE’s shift for fintech startups and payment service providers. A pullback from public-sector solutions may increase market opportunities for regulated private innovations.

Conflux Taps Offshore Yuan for Global Trade Amid Blockchain 3.0 Upgrade and Rising Chinese Ambitions

Futuristic digital illustration of offshore Yuan stablecoin concept, showing glowing Yuan currency symbols connected by blockchain lines across a modern Asian city skyline and global trade port at sunset.

Chinese Layer 1 blockchain Conflux (CFX) is making waves again. This time, it’s not just for its market performance but for its strategic ambitions. The network recently unveiled a new offshore Yuan stablecoin and a significant Tree-Graph 3.0 blockchain upgrade. These moves have propelled the CFX token into a sharp price rally. And it certainly renewed speculation about China’s evolving blockchain strategy.

Offshore Yuan Stablecoin: A New Tool for Cross-Border Trade

The new stablecoin is pegged to the Chinese Yuan but designed strictly for offshore use. It signals Conflux’s ambition to serve as a bridge between blockchain innovation and global trade settlements. While China maintains restrictions on domestic cryptocurrency use, this offshore Yuan stablecoin targets cross-border commerce. It offers an RMB-denominated alternative outside the traditional banking systems like SWIFT.

This development reflects growing interest in alternative trade settlement solutions. Global financial fragmentation and geopolitical tensions have increased this demand. Hence, Conflux positions itself within this space. It provides infrastructure appealing to those seeking digital yuan alternatives for international transactions.

Blockchain 3.0: Upgrading for Enterprise-Grade Use

At the core of this strategy is Conflux’s Tree-Graph 3.0 upgrade. This latest iteration improves scalability, interoperability, and performance. It addresses challenges for Layer 1 blockchains aiming to support enterprise-level applications. The upgrade underscores Conflux’s commitment to building infrastructure suited for global trade ecosystems, demanding robust, high-throughput infrastructure.

Conflux is focusing on technical evolution through its blockchain upgrades 2025 roadmap. It aims to strengthen its position among Chinese blockchain projects competing for enterprise adoption across Asia and beyond.

China’s Dual Approach to Blockchain: Cautious Domestically, Aggressive Offshore

Observers note that Conflux’s moves reflect a broader Chinese blockchain strategy. Domestic cryptocurrency trading still remains heavily restricted. Yet, Chinese firms are encouraged to explore blockchain’s potential for cross-border applications. These efforts align with China’s goal of internationalizing RMB.

Conflux benefits from this duality. It operates as a public-permissionless blockchain permitted within these offshore gray zones. The offshore Yuan stablecoin fits this narrative. It offers a compliant yet strategic foothold in international markets while avoiding domestic conflicts.

This approach underscores China’s interest in blockchain for trade settlements. It allows testing of digital currency applications abroad while maintaining internal restrictions.

Market Response: From Fundamentals to Frenzied Speculation

The market’s reaction has been swift. The CFX price rally, with gains surpassing 100% in some reports, reflects strong trader sentiment. Many see these developments as bullish indicators of China’s continued blockchain ambitions, and media coverage has amplified this narrative. Phrases like “God candle” and “China crypto play” fuel short-term speculation.

However, analysts offer a note of caution. While fundamentals appear stronger, sustained gains depend on real adoption of the offshore stablecoin. Enterprise use of the upgraded blockchain remains a key factor.

Outlook: Can Conflux Deliver on Its Global Ambitions?

Looking ahead, some key questions emerge. Will businesses adopt the offshore Yuan stablecoin for cross-border trade? Can Conflux CFX secure meaningful partnerships beyond China’s borders? Financial hubs like Hong Kong or Singapore are in focus.

Regulatory clarity, enterprise uptake, and evolving needs for blockchain for trade settlements will shape the project’s future. Conflux is positioning itself at the convergence of technology, finance, and geopolitics. It offers both an infrastructure upgrade and a currency solution fit for shifting global trade dynamics.

Readers’ frequently asked questions

Can I use the offshore Yuan stablecoin for trading or investment?

No, the stablecoin is designed specifically for enterprise-level trade settlements and not for retail trading or investment purposes.

Will the offshore Yuan stablecoin be available globally?

The stablecoin is aimed at international trade use and is not available within mainland China. Access outside of Asia may depend on regulatory approvals in various jurisdictions.

Does this affect the availability of CFX on major crypto exchanges?

No. The offshore Yuan stablecoin is separate from the CFX token, which continues to be traded on major cryptocurrency exchanges as before.

What Is In It For You? Action Items You Might Want to Consider

Track developments around Conflux’s offshore Yuan stablecoin launch

If you are involved in cross-border trade, fintech, or stablecoin adoption, keep an eye on how Conflux progresses from announcement to actual launch. Monitor partnerships, regulatory feedback, and pilot projects that could shape its future use.

Evaluate potential enterprise applications for Conflux 3.0

Enterprises exploring blockchain for settlement solutions should assess how Conflux’s Tree-Graph 3.0 upgrade might align with their needs. Its focus on scalability and interoperability positions it as a possible alternative to more established Layer 1 ecosystems.

Traders and investors should observe how the CFX token behaves following the current market reaction. Evaluate whether future price movements correlate with genuine milestones—such as the stablecoin’s launch—or remain driven by speculative interest tied to China narratives.

US Stablecoin Law 2025: What Changes for Crypto Compliance and Consumers

Photo-realistic illustration of golden dollar coins, a legal book titled “Stablecoins,” and the US Capitol building in the background, symbolizing US stablecoin regulation and financial compliance.

The United States has taken a decisive step toward regulating digital finance with the signing of the first US stablecoin law, the GENIUS Act. This landmark legislation provides a comprehensive federal framework specifically targeting stablecoins, digital assets pegged to fiat currencies like the US dollar. The law now sets clear expectations for industry participants while introducing enhanced consumer safeguards.

As the crypto industry reacts to this sweeping regulatory shift, here’s what you need to know. We’ll cover the new compliance requirements, market implications, and what changes consumers can expect from new crypto-focused consumer protections.

Why This New US Stablecoin Law Matters

For years, the absence of unified federal guidelines created uncertainty for stablecoin issuers, investors, and consumers. Fragmented state-by-state policies offered little clarity on how stablecoins should operate, often leaving companies to navigate inconsistent oversight. As a result, it exposed consumers to unnecessary risk.

The GENIUS Act ends that uncertainty. By establishing a federal licensing regime and strict operational standards, the law aims to solidify the US position in the global digital finance landscape. It also helps ensure the dollar’s continued dominance in the digital economy.

Key Compliance Requirements for Stablecoin Issuers

Reserve Standards

One of the GENIUS Act’s most critical provisions mandates that all stablecoins must be backed on a 1:1 basis with cash or short-term US Treasuries. This ensures that every token issued can be redeemed for a dollar at any time, thus reducing the risk of sudden depegging events like the infamous Terra/UST collapse.

Segregated Reserves and Transparency

Issuers must maintain segregated reserves held with qualified custodians. They are required to provide monthly public disclosures of reserve holdings. Issuers must also submit to quarterly GAAP-compliant audits. These steps reinforce transparency and trust.

Compliance and Oversight

The law introduces clear stablecoin compliance requirements:

  • Robust AML/KYC programs
  • Reporting obligations to federal regulators
  • Mandatory consumer protection disclosures

Issuers failing to meet these standards risk losing their operating licenses.

Restrictions on Big Tech and Financial Giants

The legislation includes explicit provisions aimed at preventing the concentration of power within a few dominant firms. Tech companies and major financial institutions cannot issue or integrate stablecoins within their platforms. They must create separate, non-leveraged subsidiaries subject to the same compliance rules. This “firewall” seeks to prevent any repeat attempts at global domination of digital money like Facebook’s failed Libra project.

What Consumers Should Expect from the New Law

Enhanced Protections

Consumers will benefit from clearer safeguards against fraud and instability. The new stablecoin law includes provisions to ensure that stablecoins operate with full backing, transparency, and oversight. These safeguards aim to protect consumers and enhance trust in digital finance. This gives users confidence their funds won’t disappear overnight.

Limitations on Yield Products

One notable restriction: stablecoin issuers are prohibited from offering yield or interest-bearing products directly. While this enhances safety, it also limits passive income opportunities for retail users. They will need to seek yield through separate, regulated investment platforms.

No FDIC Insurance

Despite these reforms, stablecoins remain outside traditional banking protections. Consumers should understand that while reserves are safer, these assets do not enjoy FDIC insurance guarantees.

Timeline for Implementation

Under the stablecoin regulation timeline:

  • Regulatory agencies have 180 days to draft and publish detailed rules.
  • Full compliance becomes mandatory 18 months after the law takes effect.
  • Existing issuers have up to three years to transition or exit the market.

Broader Impact on the Crypto Industry

The US’s new stablecoin legislation is already influencing the markets. Crypto prices surged following the law’s passage. Institutional players are preparing to launch compliant stablecoins under the new framework. Analysts see the GENIUS Act as a milestone. It is expected to unlock new growth avenues in digital payments, remittances, and tokenized finance.

By reinforcing stablecoin security measures and creating pathways for regulated innovation, the US positions itself as a leader in shaping the future of digital finance. This move also aligns the US more closely with emerging global standards. Examples include the EU’s MiCA regulation and other frameworks across Asia.

Conclusion: A Safer, Clearer Future for Stablecoins

The US’s new stablecoin law, the GENIUS Act, marks a turning point for both industry participants and consumers. For issuers, the expectations around stablecoin compliance requirements are now crystal clear. For consumers, the law promises enhanced transparency and safeguards. However, it does not offer the high-yield opportunities some once associated with crypto’s Wild West days.

While debates over innovation versus regulation will continue, one thing is certain. Stablecoins now operate under the watchful eye of Washington. The era of unchecked issuance is officially over.

Readers’ frequently asked questions

How does this law affect foreign stablecoin issuers?

Foreign issuers who want to offer stablecoins to US consumers will need to comply with compatibility standards outlined by US regulators. Although there are exemptions available, these are conditional on meeting equivalent regulatory standards abroad. In practice, most major foreign issuers will need to align with US rules or risk exclusion from the American market.

Are stablecoins under this law insured like bank deposits?

No. Stablecoins, even under this law, do not receive FDIC insurance or similar guarantees. Although the law strengthens reserve and transparency requirements, consumers should understand that stablecoins remain distinct from traditional bank accounts in terms of legal protections.

What impact does this have on DeFi and non-custodial wallets?

The law primarily targets fiat-backed stablecoin issuers and does not directly regulate decentralized finance (DeFi) platforms or non-custodial wallets. However, stablecoins issued under these new rules may face limitations on how they can be used in DeFi protocols, especially if those protocols operate without regulatory oversight. Over time, this could push DeFi platforms to clarify their legal standing or risk losing access to compliant stablecoin liquidity.

What is in it for you? Action items you might want to consider

Track stablecoin regulatory compliance developments

Monitor updates from US regulators as they draft implementation rules over the next 180 days. These will clarify the operational details that banks, fintechs, and foreign issuers must follow.

Assess stablecoin issuer readiness and partnerships

If you work in finance, payments, or crypto, evaluate how your partners or providers are aligning with the new licensing, reserve, and audit standards. Consider reassessing integrations with any issuer that lacks a clear path to compliance.

Evaluate DeFi implications and usage risks

Watch how DeFi protocols respond to these regulatory changes. Legal clarity may increase reliance on US-compliant stablecoins, but some DeFi services may face liquidity risks or new regulatory pressures as a result.

BREAKING: House Passes Stablecoin Bill, Sending Landmark Crypto Legislation to Trump’s Desk

A photo-realistic image of a congressional hearing room with a polished wooden desk in the foreground, featuring a stack of legislative documents and a pen. Rows of empty chairs and blurred American flags are visible in the background, symbolizing U.S. legislative action on stablecoin regulation.

The House passes stablecoin bill in a historic move to bring long-awaited clarity to the regulation of digital assets. The GENIUS Act, now approved by the House, will head to President Donald Trump’s desk, expected to be signed into law within days.

The House passed the GENIUS Act after days of procedural chaos, setting the stage for the United States’ first comprehensive federal framework for stablecoin regulation. The legislation mandates that issuers back stablecoins with one-to-one liquid reserves. Further, it imposes strict audit and disclosure requirements and establishes a clear licensing regime for both federal and state-chartered issuers.

Why the House Passing Stablecoin Bill Matters

This vote marks a decisive moment for US crypto legislation. The GENIUS Act can resolve years of uncertainty surrounding stablecoins, digital assets pegged to fiat currencies like the US dollar. The bill is designed to protect consumers, stabilize markets, and provide clarity for both issuers and institutional investors.

The House passed the GENIUS Act with bipartisan support after overcoming internal GOP disputes earlier in the week. The bill’s advancement represents a significant victory for the crypto industry’s push for clear, predictable regulations.

What Else Was Passed

In addition to the GENIUS Act, the House also approved the Crypto Market Infrastructure Bill, a measure clarifying the jurisdiction of the SEC and CFTC over digital assets. This legislation echoes elements of the previously proposed CLARITY Act, formally expanding the CFTC’s authority over crypto commodities. At the same time, it reaffirms the SEC’s oversight of securities-like tokens.

Industry and Market Response

Crypto markets reacted positively to the news. Analysts interpret the fact that the House passed the stablecoin bill as a signal that Congress is now capable of delivering the regulatory clarity the industry has long demanded. However, some caution remains: the effectiveness of these laws will depend on enforcement and implementation timelines.

Next Steps

Once signed by President Trump, the GENIUS Act will create a federal baseline for stablecoin operations. It will require strict compliance with transparency and reserve standards. Meanwhile, the Crypto Market Infrastructure Bill will shape the classification and oversight of digital assets for years to come.

- Advertisement -

FEATURED