Home Blog Page 123

Legislators Race to Lock in Bitcoin Reserve Policy as Trump’s Crypto Shift Gains Traction
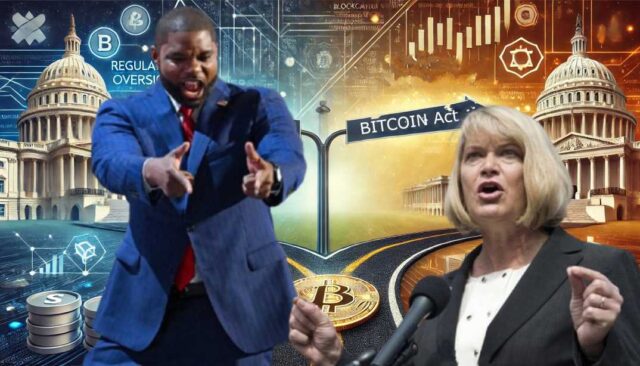
Lawmakers rush to codify Trump's Bitcoin Reserve Policy

In a move that could reshape the U.S. financial landscape, lawmakers are racing to codify President Donald Trump’s Strategic Bitcoin Reserve into law, ensuring the policy remains intact beyond his administration. The initiative, stemming from an executive order signed on March 7, 2025, has sparked heated debate in Congress. Supporters hail it as a necessary step toward securing America’s dominance in digital finance, while critics warn of economic risks tied to Bitcoin’s volatility.

Representative Byron Donalds (R-FL) and Senator Cynthia Lummis (R-WY) are at the heart of the legislative push, both introducing bills making the government’s Bitcoin accumulation a permanent fixture. If successful, the United States could become one of the largest institutional holders of Bitcoin, stockpiling up to 1 million BTC over the next five years.

The Push for a Permanent Bitcoin Reserve

The White House’s executive order directed the Treasury and Commerce Departments to establish a U.S. Strategic Bitcoin Reserve, primarily funded through seized Bitcoin from criminal cases. It also set forth a policy to explore budget-neutral strategies for acquiring additional Bitcoin reserves without using taxpayer funds.

However, the temporary nature of an executive order means that a future administration could overturn the policy. To prevent this, Donalds and Lummis are leading the charge to enshrine the Bitcoin Reserve into federal law.

Donalds, a staunch proponent of cryptocurrency, is preparing a bill restricting any future president from reversing the Bitcoin reserve policy through executive action. His argument is simple: the U.S. must secure its position in the digital economy. Ensuring a long-term BTC stockpile is a crucial part of that strategy.

Lummis, known for her pro-Bitcoin stance, has reintroduced the BITCOIN Act (Bitcoin Investment Trust and Coin Optimization for National Security). If confirmed, it would authorize the U.S. government to purchase and hold up to 1 million BTC over five years. The bill proposes a financing mechanism that relies on re-evaluating gold certificates, avoiding any direct cost to taxpayers. Lummis argues that Bitcoin, like gold, should be treated as a strategic asset. Long-term holdings of strategic assets strengthen the nation’s financial independence.

A Divisive Debate in Washington

The legislative push has divided lawmakers. Supporters frame it as a strategic move to position the U.S. as a leader in digital finance. Opponents raise concerns about financial stability and potential risks of government-controlled Bitcoin holdings.

Supporters argue that Bitcoin, often referred to as digital gold, represents an opportunity for the U.S. to hedge against inflation and reduce reliance on traditional financial systems. By embracing Bitcoin at a national level, they believe the government can drive innovation, attract investment, and reinforce the country’s dominance in global finance.

Critics, however, warn that Bitcoin’s price volatility could threaten national financial stability. Some lawmakers are particularly concerned that the government’s large-scale involvement in Bitcoin markets could distort market behavior. This could have unintended consequences for both retail and institutional investors. Others question whether the government should stockpile an asset that does not generate yield, unlike traditional reserves such as U.S. Treasury bonds or gold-backed securities.

Senator Elizabeth Warren (D-MA), a vocal critic of the crypto industry, has argued that the reserve policy amounts to “reckless financial speculation at the national level” and could expose taxpayers to unnecessary risks. Meanwhile, Federal Reserve officials have expressed concerns over how a government-controlled Bitcoin reserve might impact monetary policy and broader financial stability.

Global and Market Implications

If the legislation passes, the U.S. government could become one of the largest sovereign holders of Bitcoin, sending ripples across the global financial landscape. The move would signal a significant shift in the perception of Bitcoin as a legitimate reserve asset, potentially influencing other governments to follow suit.

Market analysts are divided on how this development could impact Bitcoin prices. Some believe that a structured, long-term accumulation strategy by the U.S. could drive institutional adoption and reduce supply, potentially increasing Bitcoin’s value. Others caution that government involvement in Bitcoin markets introduces regulatory uncertainty that could deter private investors.

A Defining Moment for U.S. Crypto Policy

The Strategic Bitcoin Reserve’s fate now lies in Congress’s hands. If lawmakers codify the policy, the U.S. will cement its role as a Bitcoin powerhouse, integrating digital assets into the national financial strategy for the first time in history.

However, if the push falters amid political resistance, Bitcoin’s future in U.S. federal policy could remain uncertain. It will be subject to shifting administrations and regulatory battles.

As legislative debates unfold, the U.S. finds itself at a crossroads between embracing Bitcoin as a national strategic asset and resisting its full-scale integration into government financial holdings. What happens next could define the country’s role in the global crypto economy for decades to come.

Readers’ frequently asked questions

How does the U.S. government store and secure Bitcoin in the Strategic Bitcoin Reserve?

The security of Bitcoin held by the U.S. government is a critical issue. Improper storage could expose the reserves to theft or cyberattacks. Typically, when governments or large institutions hold cryptocurrency, they rely on cold storage solutions. The Bitcoin is kept offline in hardware wallets or other secure storage mechanisms not connected to the internet.

For the Strategic Bitcoin Reserve, the Treasury Department and other federal agencies will likely use multi-signature wallets, requiring multiple authorized parties to approve transactions. This method prevents unauthorized access and reduces the risk of a single point of failure.

Additionally, the U.S. government has experience handling Bitcoin from previous seizures of criminally obtained cryptocurrency. The U.S. Marshals Service, for instance, has auctioned off seized Bitcoin in the past, which suggests that federal agencies already have some infrastructure in place for securely managing digital assets. The implementation details of the reserve are still being finalized, but robust security protocols will be necessary to protect the holdings.

What happens to the Bitcoin the U.S. government seizes from criminal cases?

Under current procedures, Bitcoin seized in criminal cases is typically sold at government auctions. The proceeds are then deposited into government accounts. However, under the new Strategic Bitcoin Reserve policy, this Bitcoin will be transferred to the national reserve instead of selling on the open market.

This means that instead of liquidating confiscated Bitcoin, the government will retain it as part of the national holdings. The goal is to use these seized assets to help build up the reserve without spending taxpayer money.

If the reserve policy is fully implemented, this shift could significantly increase government-held Bitcoin over time, as federal agencies regularly seize digital assets in criminal investigations. However, the legislation must ensure clear guidelines on how and when seized Bitcoin is transferred to the reserve.

Can a future U.S. president undo the Strategic Bitcoin Reserve?

The simple answer is Yes. President Trump’s executive order only establishes the Strategic Bitcoin Reserve under his administration’s authority. A future president could revoke or modify the order, potentially dismantling the reserve or changing its management.

This is why lawmakers like Representative Byron Donalds and Senator Cynthia Lummis want to codify the policy into federal law. If Congress passes legislation making the reserve a permanent fixture, future administrations will need congressional approval to alter or eliminate it.

However, even if the policy is codified, future lawmakers could still amend or repeal it. The reserve’s long-term stability will depend on continued bipartisan support and how well the initiative performs in economic and financial security objectives.

What Is In It For You? Action Items You Might Want to Consider

Monitor Market Reactions to U.S. Government Bitcoin Accumulation

With the U.S. government actively acquiring Bitcoin, traders should closely watch how this institutional-level demand impacts market liquidity and price trends. If legislation moves forward and the government accumulates BTC on a structured timeline, this could introduce a new long-term price floor. Pay attention to legislative updates, reserve accumulation reports, and any changes in government policy. Such policy news can shift market sentiment.

Position for Potential Volatility Around Policy Decisions

While the Strategic Bitcoin Reserve signals bullish long-term sentiment, political uncertainty could create short-term market swings. If Congress solidifies the reserve policy into law, expect a potential Bitcoin price rally. Conversely, sentiment could temporarily turn bearish if opposition mounts and policies face setbacks. Traders should prepare stop-loss strategies, options hedging, or laddered buy-in points to navigate potential volatility tied to regulatory developments.

Consider the Long-Term Institutional Adoption Trend

Bitcoin’s integration into U.S. national reserves could accelerate mainstream institutional adoption, reinforcing its legitimacy as a financial asset. Other countries or large-scale investors may follow the U.S. if it treats BTC similarly to gold. Traders should evaluate their portfolio allocations with a long-term perspective. Focus on Bitcoin’s role as a strategic asset but stay updated on regulatory shifts that could influence demand.
Stablecoin Showdown: Will the GENIUS Act Propel Crypto Dollars into the U.S. Mainstream?

The GENIUS Act is poised to reshape the stablecoin landscape in the U.S.

Lawmakers took a significant step forward in their push to regulate stablecoins in the U.S. introducing the GENIUS Act. With bipartisan effort, the Senate wants to define the rules for issuers and integrate digital dollars into the traditional financial system. The bill could mark a turning point for stablecoin legitimacy backed by industry players like Circle and a structure balancing federal and state oversight. However, the path forward remains uncertain. Regulatory hardliners remain skeptical and voice concerns about Big Tech potentially entering the market. Will the GENIUS Act unlock a new era of financial innovation, or will regulatory hurdles slow progress?

A Bipartisan Push for Stablecoin Regulation

Introduced by Senators Bill Hagerty (R-TN), Kirsten Gillibrand (D-NY), Cynthia Lummis (R-WY), and Tim Scott (R-SC), the Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act aims to create a comprehensive regulatory framework for stablecoins. The bill would ensure stablecoins are backed by tangible reserves and prevent algorithmic stablecoins from operating in the U.S. Notably, it also wants to enforce strict compliance with anti-money laundering (AML) and sanctions laws.

The legislation would establish a dual regulatory system. Stablecoin issuers with a market capitalization exceeding $10 billion will fall under the direct oversight of the Federal Reserve. Smaller issuers can choose to be regulated at the state level. Proponents see this approach as a compromise between federal control and state-led innovation. It leaves room for competition while enforcing uniform standards across the industry.

Industry Support and Potential Impact on Adoption

Major stablecoin issuers received the GENIUS Act largely positive, particularly Circle, the company behind USDC, one of the most widely used stablecoins. Industry participants argue that regulatory clarity could facilitate the broader adoption of stablecoins in traditional financial markets, making them more accessible for businesses, banks, and consumers.

Many industry leaders believe reducing regulatory uncertainty is essential for integrating stablecoins into mainstream finance. Establishing clear legal guidelines could encourage financial institutions and payment networks to adopt stablecoins, positioning the U.S. as a global leader in digital dollar innovation.

Concerns Over Financial Stability and Big Tech Influence

Despite its industry support, the GENIUS Act has drawn scrutiny from lawmakers and regulatory bodies concerned about its potential implications. Some critics worry that the bill does not sufficiently address risks related to financial stability. They fear large-scale stablecoin issuance could lead to disintermediation in the banking sector. Others argue that the involvement of tech giants – such as Elon Musk’s X (formerly Twitter) – could introduce systemic risks, particularly if companies begin issuing their own stablecoins to compete with government-backed currencies.

Senator Elizabeth Warren has voiced concerns about the possibility of major corporations using stablecoins to bypass traditional financial regulations. Without proper safeguards, we could see Big Tech creating their own currencies, undermining the U.S. dollar and our financial system, she warned.

Democratic lawmakers have also proposed national security amendments to prevent stablecoin issuers from circumventing U.S. sanctions laws. These amendments specifically target foreign-issued stablecoins like Tether (USDT). These have been scrutinized for their potential use in illicit financial activities.

The Road Ahead: Can the GENIUS Act Pass?

The GENIUS Act is currently making its way through legislative review, with the Senate Banking Committee set to vote on the bill. The bipartisan support gives it a strong foundation. Nevertheless, the final version may undergo significant amendments before it reaches the Senate floor.

If passed, the bill could lay the groundwork for a stablecoin-powered financial ecosystem in the U.S., bridging the gap between traditional finance and blockchain-based assets. However, if opposition from regulatory agencies and skeptical lawmakers gains traction, stablecoin regulation may continue to face roadblocks, leaving the industry uncertain.

As the debate unfolds, one question remains at the forefront: Will the GENIUS Act propel stablecoins into the U.S. mainstream, or will regulatory concerns ultimately stall progress? The outcome will shape the future of digital dollars and the broader cryptocurrency landscape for years to come.

Readers’ frequently asked questions

What exactly are stablecoins, and how do they differ from regular cryptocurrencies like Bitcoin?

Stablecoins are cryptocurrencies designed to maintain a stable value by being pegged to a reserve asset, such as the U.S. dollar or gold. Unlike Bitcoin or Ethereum, which experience significant price fluctuations due to market speculation, stablecoins are backed by reserves or algorithms to keep their value consistent. This stability makes them useful for transactions, remittances, and financial services without the risk of price volatility. In the case of the GENIUS Act, the bill aims to regulate stablecoins backed 1:1 with assets like cash or U.S. Treasury bonds, ensuring they remain reliable for everyday use.

Why do lawmakers want to regulate stablecoins, and how does it impact regular users?

Lawmakers are concerned that absent proper oversight, stablecoins could pose risks to financial stability, be used in illicit activities, or even challenge the U.S. dollar’s role in the global economy. Some worry that large corporations starting to issue their own stablecoins could create a parallel financial system outside government control. For regular users, regulation could bring both benefits and challenges. On the positive side, clear legal guidelines could make stablecoins safer and more widely accepted, potentially leading to better integration with traditional banking and payment systems. On the downside, regulation might introduce stricter compliance requirements, limiting who can issue and use stablecoins, which could affect availability and innovation in the crypto space.

How would the GENIUS Act affect stablecoins like USDT (Tether) and USDC (Circle’s stablecoin)?

The GENIUS Act would have a direct impact on stablecoin issuers like Circle and Tether by imposing stricter regulatory standards. USDC, issued by a U.S.-based company and already compliant with regulatory requirements, would likely benefit from clearer legal recognition. It would become more attractive to banks and financial institutions. Tether (USDT), however, could face more scrutiny. An offshore entity issues the coin and the company has been criticized for lacking transparency regarding its reserves. The bill could potentially affect Tether’s use on American crypto exchanges if it includes national security amendments targeting foreign stablecoins that restrict such coins or make them subject to additional compliance measures in the U.S.

What Is In It For You? Action Items You Might Want to Consider

Keep an Eye on Regulatory Developments

The GENIUS Act could be a game-changer for stablecoin adoption in the U.S., but its final shape is still uncertain. Stay updated on how this legislation evolves if you’re actively trading or using stablecoins for payments. A shift in regulatory requirements could impact liquidity, exchange listings, or even restrictions on certain stablecoins like USDT. Follow legislative updates and be ready to adjust your holdings accordingly.

Diversify Your Stablecoin Holdings

While USDC seems well-positioned under the proposed framework, USDT and other offshore stablecoins could face regulatory hurdles. Consider diversifying your stablecoin exposure by holding assets across multiple issuers, including those that comply with U.S. regulations. This way, you mitigate risks if a particular stablecoin faces restrictions or liquidity issues.

Look for Emerging Institutional Opportunities

If the GENIUS Act brings more regulatory clarity, we could see increased adoption of stablecoins in traditional finance. Keep an eye on banks, payment platforms, and fintech companies integrating stablecoins into their services. This could create new trading pairs, higher liquidity, and even yield-generating opportunities in DeFi and centralized platforms. Position yourself early to take advantage of these developments.

BBVA Becomes First Major Spanish Bank to Offer Bitcoin and Ether Trading

BBVA introduces crypto services in Spain

In a landmark move for the Spanish banking sector, BBVA has secured regulatory approval from Spain’s Comisión Nacional del Mercado de Valores (CNMV) to offer Bitcoin (BTC) and Ether (ETH) trading and custody services to its customers. As one of the country’s largest financial institutions, BBVA integrating crypto services into its existing digital banking platform represents a major step toward mainstream banking adoption of digital assets. This move aligns with a broader European trend, where traditional financial institutions are increasingly engaging with cryptocurrencies in response to the European Union’s Markets in Crypto-Assets (MiCA) regulations.

With BBVA’s approval, Spain joins the growing list of European nations where banks are offering direct crypto services. But beyond regulatory compliance, this shift signals an emerging competition between legacy financial institutions and crypto-native platforms like Binance and Coinbase. As BBVA opens its doors to retail investors looking for a secure and regulated way to trade Bitcoin and Ethereum, the question arises: Can traditional banks successfully challenge crypto-native platforms, or will they struggle to keep up?

BBVA’s Crypto Offering: A Secure Alternative to Exchanges?

BBVA will integrate the new service into its existing mobile banking app. It allows customers to trade and store Bitcoin and Ether alongside their traditional financial assets. Unlike centralized crypto exchanges, often facing regulatory scrutiny and security concerns, BBVA’s offering operates within the regulated banking framework. That could give it an edge in compliance and security.

The bank has emphasized that its custody solution will not rely on third parties. BBVA will retain full control over the safeguarding of customers’ crypto holdings. This approach contrasts with many crypto exchanges, where security breaches and withdrawal suspensions have raised concerns in recent years. By offering direct custody, BBVA aims to reassure investors wary of the risks associated with unregulated or loosely regulated platforms.

Moreover, BBVA gained experience in Switzerland and Turkey, where it launched similar crypto trading services in 2021 and 2023 respectively. This suggests that the bank is well-versed in handling digital assets, positioning it ahead of other traditional financial institutions in Spain that have yet to take concrete steps toward cryptocurrency adoption.

Competition Between Banks and Crypto-Native Platforms

BBVA’s foray into cryptocurrency services is more than just an isolated banking initiative. It is a direct challenge to crypto-native platforms that have traditionally dominated the space. While exchanges like Binance, Coinbase, and Kraken have long provided users with the ability to trade and store crypto, banks have generally remained on the sidelines, largely due to regulatory uncertainty and risk aversion.

However, with MiCA standardizing crypto regulations across Europe, traditional financial institutions are now entering the market. They offer crypto services within the framework of established banking regulations. This shift presents a new competitive landscape:

  • Regulated vs. Unregulated Services – While crypto exchanges face ongoing legal battles and compliance challenges, BBVA’s offering comes with full regulatory approval. It provides a level of security and consumer protection that some exchanges lack.
  • Integrated Banking vs. Standalone Crypto Platforms – Unlike standalone exchanges, BBVA’s service is part of a multi-asset banking platform. Customers can manage their crypto alongside fiat accounts, loans, and investments in a single interface.
  • Trust Factor – Despite their popularity, crypto-native platforms still struggle with public perception issues, particularly after events like the FTX collapse and other major exchange failures. BBVA’s established reputation as a major financial institution could make it a preferred choice for risk-averse investors.

However, traditional banks also face key disadvantages compared to crypto-native platforms. While BBVA offers Bitcoin and Ether, many exchanges provide access to thousands of cryptocurrencies, decentralized finance (DeFi) services, staking, and lending products. Banks are unlikely to match these features in the short term. Additionally, banks may impose higher fees and tighter restrictions than exchanges known for low-cost trading and flexibility.

What This Means for the Future of Crypto in Banking

BBVA’s entry into the cryptocurrency market signals that mainstream banks take digital assets seriously. While traditional financial institutions once dismissed crypto as a niche or speculative market, today they see it as a growing sector with increasing institutional and retail demand.

This trend could have long-term implications:

  • Greater Adoption – If major banks continue integrating crypto services, digital assets will become more accessible to the general public. That will reduce reliance on third-party exchanges.
  • Regulatory Legitimacy – With banks offering crypto within the framework of financial regulations, governments may be more inclined to support industry growth, instead of imposing restrictive bans or crackdowns.
  • Potential for Expansion – While BBVA currently offers only Bitcoin and Ether, this move could open the door to additional crypto assets, further bridging the gap between traditional and digital finance.

Still, challenges remain. The volatility of crypto markets, regulatory risks, and the pace of innovation in DeFi and Web3 could test how effectively banks can adapt to the evolving digital asset landscape. While BBVA made the first move in Spain, its success will depend on whether other major banks follow suit. It will also hinge on whether crypto-native platforms evolve to maintain their competitive edge.

For now, BBVA’s initiative represents a significant milestone in converging traditional banking and digital finance. As regulatory clarity increases and institutional adoption grows, the financial industry may soon see more banks embracing crypto. They will redefine how cryptocurrencies are accessed, stored, and traded in the years ahead.

BBVA’s approval to offer Bitcoin and Ether trading marks a turning point in Spain’s financial sector, reflecting a broader European shift toward regulated cryptocurrency adoption. As traditional banks compete with crypto-native platforms, the industry faces a new era of financial innovation. Digital assets are no longer confined to specialized exchanges but will become an integral part of mainstream banking. Whether this trend strengthens traditional institutions or disrupts their dominance remains to be seen. However, one thing is clear: crypto is here to stay, and the banking sector is taking notice.

Readers’ frequently asked questions

How does BBVA’s crypto service differ from using an exchange like Binance or Coinbase?

BBVA’s crypto service offers a regulated, bank-integrated way to trade and store Bitcoin and Ether, differing significantly from platforms like Binance and Coinbase. The key advantage of BBVA’s service is that it operates within the Spanish banking system under regulatory oversight. Funds and transactions benefit from consumer protections that crypto exchanges do not always provide. Additionally, BBVA directly manages the custody of customers’ crypto assets. The bank ensures that they are stored within its own infrastructure rather than relying on third-party custodians.

On the other hand, exchanges like Binance and Coinbase provide access to a much wider range of cryptocurrencies beyond just Bitcoin and Ether. They also offer additional services like staking, lending, and decentralized finance (DeFi) features. Traditional banks like BBVA are unlikely to incorporate these anytime soon. Another major difference is fees and flexibility. Crypto exchanges often offer lower trading fees and fewer restrictions on deposits and withdrawals. Banks typically impose stricter policies to align with financial regulations.

BBVA’s service might be an attractive option for users who prioritize security and regulation. However, those who want access to a broader range of crypto assets and financial services may still prefer exchanges.

Can BBVA freeze or block my crypto transactions like a regular bank account?

Yes, since BBVA is a regulated financial institution, it will follow anti-money laundering (AML) and financial crime regulations, similar to how traditional bank accounts operate. This means that transactions flagged as suspicious, e.g. large transfers without clear origins, transactions linked to sanctioned entities, or movements that trigger fraud alerts, could be reviewed, delayed, or even blocked by the bank.

This is a key difference between using a bank for crypto transactions versus a decentralized exchange (DEX). On decentralized platforms, users have full control over their assets without interference. Still, this comes with the risk of scams, hacks, and lack of recourse in case of fraud. With BBVA, customers get added security and regulatory protection, but they also have to comply with the bank’s policies, which could limit how freely they can move their assets.

Will BBVA eventually add more cryptocurrencies, or will it stick to Bitcoin and Ether?

For now, BBVA is only offering Bitcoin (BTC) and Ether (ETH), likely because these are the most widely recognized and regulated cryptocurrencies. These two assets also have the most established market demand and financial institutions view them as safer than smaller, more volatile altcoins.

Whether BBVA expands its offerings depends on regulatory clarity and market demand. With the European Union’s MiCA regulation setting clearer rules for digital assets, there is a possibility that banks will start offering more cryptocurrencies in the future. However, banks tend to be risk-averse, meaning they will likely focus on assets with strong institutional backing and regulatory approval.

In contrast, crypto-native exchanges will continue to offer a much broader selection of tokens, including altcoins, stablecoins, and DeFi assets. For users interested in trading a wider range of cryptocurrencies, banks may not be the best option in the near future.

What Is In It For You? Action Items You Might Want to Consider

Explore Regulated Crypto Trading for Added Security

If you’re concerned about the risks associated with unregulated crypto exchanges, BBVA’s bank-backed trading service could be worth exploring. Unlike traditional crypto exchanges, a regulated financial institution like BBVA offers secure custody, compliance with banking laws, and consumer protections. If you prefer to keep your crypto within a familiar, regulated banking environment, this could be a safer alternative to centralized exchanges. Remember, though, that you might face stricter transaction monitoring and higher fees compared to crypto-native platforms.

Diversify Your Crypto Holdings Across Platforms

BBVA’s new service is a game-changer for mainstream adoption. However, it only supports Bitcoin and Ether, limiting your options if you’re interested in altcoins, DeFi, or staking opportunities. A smart move could be diversifying your portfolio across multiple platforms. Use BBVA for secure BTC and ETH holdings, and keep your altcoin and DeFi positions in a trusted exchange or self-custody wallet. This way, you get the best of both worlds; the security of a regulated bank and the flexibility of crypto-native platforms.

BBVA’s entry into crypto signals a growing trend of traditional banks integrating digital assets. As more banks follow suit, expect new financial products like crypto-backed loans, savings accounts, and expanded custody services. To stay ahead, keep an eye on how banks interact with crypto regulations. Are they introducing new services beyond just trading? If traditional finance continues moving toward crypto, early adopters who position themselves wisely could benefit from new institutional-grade investment opportunities.

The Digital Currency Cold War: How the U.S. and EU Are Battling for Monetary Supremacy

A monetary Cold War ensues with the digital euro and the US dollar competing for dominance in the currency markets.

The world is witnessing a new kind of arms race. A war that isn’t fought with tanks or tariffs but with digital currencies. As the European Union (EU) accelerates its push for a digital euro, the United States is taking a different route. It embraces Bitcoin reserves and dollar-backed stablecoins. With President Trump’s renewed focus on digital assets, EU policymakers fear that U.S. crypto dominance could undermine the euro’s global position. Is this the start of a monetary Cold War, and what are the stakes for the future of decentralized finance?

United States: Strategic Bitcoin Reserve

In a significant policy shift, President Donald Trump signed an executive order establishing a Strategic Bitcoin Reserve. Initially funded by approximately $17 billion worth of Bitcoin acquired through legal seizures, this reserve aims to bolster America’s leadership in the cryptocurrency domain. The administration has likened this initiative to creating a “digital Fort Knox,” underscoring its strategic importance. The executive order also mandates budget-neutral strategies for acquiring additional Bitcoin, ensuring no burden on taxpayers.

This move aligns with the administration’s broader objective to position the United States as the “crypto capital of the world.” By integrating Bitcoin into its strategic reserves, the U.S. acknowledges the growing significance of digital assets in the global financial system. This policy pivot represents a departure from previous skepticism towards cryptocurrencies, signaling a more embracing stance towards digital innovation.

European Union: The Race for a Digital Euro

In contrast, the EU is advancing plans to introduce a central bank digital currency (CBDC), known as the digital euro. The European Central Bank (ECB) has explored this initiative since 2020. It wants to modernize the eurozone’s financial infrastructure and enhance monetary sovereignty. The digital euro is envisioned to complement cash, providing a secure and efficient electronic means of payment.

Unlike the U.S. strategy, which leans towards private-sector-led crypto innovation, the EU’s approach to digital currencies remains highly centralized and regulatory-driven. The ECB is concerned about retaining control over monetary policy. It wants to ensure transaction privacy and avoid dependency on non-EU digital payment systems. However, technical setbacks, including a recent ECB system outage, have raised doubts about its readiness to deploy a functional CBDC.

EU Concerns: U.S. Crypto Dominance as a Threat to Monetary Sovereignty

EU officials have expressed apprehension regarding the U.S.’s pro-cryptocurrency policies. They perceive the establishment of a U.S. Strategic Bitcoin Reserve as a potential threat to the eurozone’s monetary sovereignty and financial stability.

One of the biggest concerns is the growing dominance of dollar-backed stablecoins in global transactions. EU policymakers fear the euro could lose relevance in global finance if the world increasingly relies on stablecoins like USDT and USDC for trade, investment, and cross-border payments.

Pierre Gramegna, Managing Director of the European Stability Mechanism, recently stated that the U.S. administration’s favorable stance toward cryptocurrencies could challenge Europe’s monetary sovereignty. If dollar-backed digital assets continue to gain traction, the ECB may struggle to enforce monetary policies effectively.

In response, European officials are pushing for a more aggressive regulatory framework for stablecoins and digital assets, to ensure that euro-backed alternatives gain traction within the region. However, with the digital euro still in development and legislative hurdles delaying its rollout, EU policymakers are running out of time.

Geopolitical Implications: The Digital Currency Cold War Begins

The divergent strategies of the U.S. and the EU in the realm of digital currencies underscore a broader geopolitical contest for financial supremacy in the digital age.

The U.S.’s proactive accumulation of Bitcoin as a strategic asset signals a long-term commitment to decentralized finance. At the same time, its encouragement of dollar-pegged stablecoins reinforces the U.S. dollar’s dominance in global transactions. Conversely, the EU’s pursuit of a digital euro represents an effort to assert monetary sovereignty and limit exposure to non-EU payment systems.

This emerging “digital currency cold war” will shape the future of financial power. If the U.S. succeeds in cementing Bitcoin and stablecoins as dominant assets, the EU may struggle to position the digital euro as a viable alternative. On the other hand, if the ECB can launch a well-regulated and widely adopted digital euro, it may counterbalance the U.S.’s growing crypto influence.

As both economic powerhouses navigate this rapidly evolving digital finance landscape, their policies will influence the trajectory of digital currency adoption, regulation, and integration into the global financial system. The stakes are high, and the outcome of this digital currency Cold War could reshape the balance of financial power for decades to come.

Readers’ frequently asked questions

What is a Strategic Bitcoin Reserve, and how does it function?

A Strategic Bitcoin Reserve is a government-controlled holding of Bitcoin, similar to how central banks hold gold or foreign currency reserves. The United States has established such a reserve through an executive order, funding it with Bitcoin acquired through legal seizures. Unlike traditional reserves, managed through centralized monetary policies, Bitcoin reserves must account for price volatility and require secure storage methods.

The reserve does not function as a national currency but serves as a strategic asset. Its purpose is to strengthen the country’s financial position in digital assets, particularly as cryptocurrencies become more integrated into global markets. The U.S. government could use the Bitcoin reserve for financial stability measures, trade backing, or market influence. However, its effectiveness depends on managing risks associated with Bitcoin’s fluctuating value. Unlike fiat reserves, Bitcoin is decentralized and outside the direct control of central banks. Its role in government holdings would be unique and potentially disruptive to traditional financial systems.

How do stablecoins like USDT and USDC work, and why do they matter in global finance?

Stablecoins are digital assets designed to maintain a fixed value by being pegged to a reserve asset, most commonly the U.S. dollar. The issuing company backs each unit of stablecoin with an equivalent amount of real-world assets held by the issuer, such as cash or government securities. This peg ensures that stablecoins remain relatively stable compared to cryptocurrencies like Bitcoin, which experience price fluctuations.

Their role in global finance is growing because they offer an efficient way to conduct cross-border transactions. Often they are faster and cheaper than traditional banking methods. Stablecoins are widely used in cryptocurrency markets for trading, decentralized finance (DeFi) applications, and as a digital alternative to fiat currency in international transfers. Since they are dollar-backed, their increasing adoption strengthens the dollar’s role in digital transactions. This has raised concerns within the European Union. They believe more reliance on U.S. dollar-pegged stablecoins could weaken the euro’s relevance in global finance, especially if the digital euro is not widely adopted.

What are the key differences between a central bank digital currency (CBDC) like the digital euro and cryptocurrencies like Bitcoin?

A central bank digital currency (CBDC) such as the digital euro is issued and controlled by a central bank, making it a direct liability of the government, similar to physical cash. In contrast, Bitcoin operates on a decentralized network, meaning no single authority controls its issuance or transactions.

The digital euro would function as an electronic version of fiat money. The European Central Bank maintains control over monetary policy and financial stability. It will be regulated, with built-in compliance measures to track transactions. That differs from Bitcoin, which relies on an open, transparent blockchain where transactions can be traced but users remain pseudonymous.

Bitcoin’s supply is fixed at 21 million coins, making it deflationary and resistant to monetary manipulation. Just like traditional fiat currencies, the digital euro will not have a supply cap and will be adjusted according to economic needs. Investors often view Bitcoin as a store of value, similar to digital gold. In contrast, the digital euro will facilitate daily transactions within the European financial system. The key distinction is that a CBDC is fully centralized and government-controlled, while Bitcoin remains independent of any single entity.

What Is In It For You? Action Items You Might Want to Consider

With the U.S. government formally establishing a Strategic Bitcoin Reserve, institutional interest in Bitcoin is likely to grow. Traders should monitor on-chain data and wallet movements from known government holdings, as any significant Bitcoin accumulation or liquidation by the U.S. could create volatility in the market. A strong buy-and-hold strategy by institutions and governments could further solidify Bitcoin’s role as a long-term store of value, making it crucial for traders to adjust their risk exposure accordingly.

Watch for Stablecoin Regulations in the EU and Their Market Impact

The European Union’s growing concerns over dollar-backed stablecoins could lead to tighter regulations impacting liquidity for crypto traders. If restrictions are imposed on USDT or USDC within the eurozone, market dynamics on European exchanges may shift, affecting arbitrage opportunities and trading volumes. Traders should stay informed about regulatory updates and prepare to diversify stablecoin holdings. Explore euro-backed alternatives or decentralized stablecoins that may remain unaffected by government restrictions.

Trade Around Digital Euro Developments and Potential Market Reactions

The digital euro’s rollout is still in development. However, key announcements from the ECB could trigger market reactions – especially in euro-denominated crypto pairs and DeFi projects with European exposure. If the ECB signals an accelerated timeline or stricter monetary controls over private digital assets, traders should anticipate potential liquidity shifts. Prepare for volatility in euro-related trading pairs. Monitoring central bank statements and ECB policy updates can help traders position themselves ahead of major moves in the European crypto market.

Deutsche Börse Backs Institutional Crypto Custody

Deutsche Börse’s Clearstream crypto custody launches in April 2025

April 2025 will mark a pivotal moment for institutional crypto adoption in Europe. Deutsche Börse’s Clearstream launches its highly anticipated cryptocurrency custody service. The financial infrastructure giant, a key player in Europe’s securities settlement industry, will provide custody and settlement services for Bitcoin (BTC) and Ethereum (ETH), catering to over 2,500 institutional clients.

This move signifies one of the strongest endorsements yet from traditional finance, bringing digital assets further into the mainstream investment landscape. With regulatory clarity improving under the European Union’s Markets in Crypto-Assets (MiCA) regulation, will this initiative finally establish Bitcoin and Ethereum as legitimate asset classes within institutional portfolios?

A Legacy Institution Bridges the Crypto Gap

Deutsche Börse’s Clearstream plays a critical role in European financial markets, facilitating post-trade services for securities, derivatives, and investment funds. Its decision to integrate cryptocurrency custody underscores the growing institutional demand for digital assets. It recognizes that Bitcoin and Ethereum are no longer niche speculative instruments but emerging components of a diversified investment strategy.

The service will be operated in partnership with Crypto Finance AG. This Swiss subsidiary of Deutsche Börse will function as the sub-custodian. The collaboration ensures that institutional investors gain exposure to digital assets within a regulated, secure, and institutionally compliant framework. It removes a long-standing barrier to crypto adoption among traditional financial firms.

“We are integrating digital assets into the existing post-trading landscape, ensuring secure access for institutional investors,” Clearstream’s representatives stated.

Why This Move Matters for Bitcoin and Ethereum

Clearstream’s entrance into the crypto custody space represents a significant shift in institutional perception toward Bitcoin and Ethereum. Historically, large-scale financial firms have maintained a cautious approach to cryptocurrencies, citing concerns over regulatory uncertainty, custody risks, and market volatility.

However, with MiCA regulations in full effect, Europe now offers a more transparent regulatory framework for digital assets than the U.S. and other global markets. By ensuring compliance with MiCA, Clearstream’s initiative provides institutions with a trusted, regulated gateway to Bitcoin and Ethereum, addressing concerns about security and transparency.

Furthermore, institutional custody solutions are crucial for enabling broader participation in crypto markets. Traditional finance operates under stringent custodial requirements, and until now, crypto lacked the robust infrastructure necessary to meet these standards. Clearstream’s integration of crypto custody into its existing securities settlement network provides an added layer of legitimacy and stability, potentially paving the way for larger capital inflows into Bitcoin and Ethereum.

A Competitive Crypto Custody Landscape

Clearstream’s move comes as major financial institutions worldwide continue exploring crypto custody. Competitors such as Bank of New York Mellon, State Street, and Fidelity Digital Assets have already introduced institutional-grade digital asset custody solutions. However, Clearstream’s direct integration into Europe’s traditional post-trading ecosystem gives it a unique advantage in onboarding regulated institutional investors.

Moreover, unlike traditional crypto custodians primarily serving hedge funds and high-net-worth individuals, Clearstream’s client base includes global banks, pension funds, and large asset managers. These are investors traditionally hesitant to engage with crypto due to compliance challenges.

What’s Next?

Clearstream’s initial offering will focus solely on Bitcoin and Ethereum, the two most established digital assets with the strongest regulatory and market infrastructure. However, industry experts speculate that future expansions could include additional cryptocurrencies, staking services, and tokenized securities.

As MiCA’s full implementation unfolds, institutions may feel increasingly comfortable engaging with digital assets. This should lead to greater liquidity, improved market stability, and further integration between crypto and traditional finance.

With Deutsche Börse’s Clearstream officially backing Bitcoin and Ethereum, the question is no longer whether institutions will adopt crypto – but rather, how soon and to what extent.

Readers’ frequently asked questions

What exactly does “crypto custody” mean, and why do institutions need it?

Crypto custody refers to a service that securely holds digital assets, such as Bitcoin and Ethereum, on behalf of investors. Unlike personal crypto wallets managed by individuals themselves, institutional custody solutions can meet the strict security and regulatory requirements of large financial entities, such as banks, pension funds, and asset managers.

For institutions, custody is essential because they operate under strict compliance rules that require third-party custodians to safeguard assets. Traditional financial markets already use custody services for securities like stocks and bonds, ensuring that assets are stored safely and that transactions are executed securely. Clearstream’s new service integrates crypto custody into a familiar institutional framework. They make it easier for large investors to enter the digital asset space without the need to navigate the complexities of private key management or on-chain security risks.

Will retail investors be able to use Clearstream’s crypto custody service?

No, Clearstream’s custody service is exclusively for institutional clients. It is for banks, asset managers, and financial institutions requiring regulated and secure access to digital assets. This service is not intended for individual retail investors who buy and hold crypto on personal exchanges or wallets.

However, the presence of institutional custody solutions can indirectly benefit retail investors. When more institutions enter the crypto market, liquidity increases, and buying and selling assets will be easier at fair market prices. Additionally, regulated custody options like Clearstream’s could encourage financial firms to develop crypto-based investment products, such as exchange-traded funds (ETFs) or structured financial products. Retail investors might access these through brokerage accounts.

How does this move impact the regulatory environment for crypto in Europe?

Clearstream’s entry into the crypto custody market is a strong signal that European regulatory conditions are maturing. The service will comply with the Markets in Crypto-Assets (MiCA) regulation, a new EU framework that established clear legal guidelines for digital assets. MiCA establishes rules for custodians, exchanges, and crypto-related financial products, aiming to make the market safer and more transparent.

This development could encourage other European financial institutions to launch their own crypto-related services. Increased competition would further legitimize the space. Additionally, it contrasts with the regulatory uncertainty in the U.S., where institutions still face unclear guidelines from the SEC regarding crypto custody. As a result, Europe could emerge as a leader in institutional crypto adoption, attracting capital and innovation in the sector.

What Is In It For You? Action Items You Might Want to Consider

With Deutsche Börse’s Clearstream integrating Bitcoin and Ethereum custody, institutional demand for these assets could increase. Watch for signals such as rising BTC and ETH inflows into institutional wallets, new investment products (ETFs, structured products), or news about major funds allocating capital to crypto. If institutional adoption picks up, it could drive long-term price appreciation—a factor worth considering in your trading strategy.

Monitor the Impact of MiCA on Market Liquidity

Europe’s Markets in Crypto-Assets (MiCA) regulation is shaping a more structured crypto market. With Clearstream’s entry, expect greater regulatory clarity, which could bring more liquidity and stability to European crypto exchanges. As liquidity improves, spreads tighten, and slippage decreases, making it easier to enter and exit trades at optimal prices. Consider incorporating European trading venues into your strategy as regulated platforms gain more traction.

Watch for Potential Bitcoin and Ethereum Price Reactions in Q2 2025

Clearstream’s crypto custody service launches in April 2025 – a timeframe that could align with institutional positioning and pre-launch accumulation. Leading up to this, traders should track market sentiment, news from European financial institutions, and any early indications of institutional inflows. If traditional finance embraces Bitcoin and Ethereum at scale, this could trigger a sustained bullish trend, making early positioning a key advantage.

Stay alert, monitor institutional activity, and be prepared to adjust your trading approach as crypto further integrates into traditional finance.

- Advertisement -

FEATURED