Home Blog Page 16

Tether Freezes $131M in USDT Linked to Iran’s Central Bank
TL;DR

  • Tether froze $131 million in USDT tied to four wallets linked to Iran’s central bank
  • The action follows an OFAC update and builds on earlier freezes totaling nearly $475 million
  • Funds remain visible onchain but unusable, highlighting issuer-level control over stablecoins

Tether has frozen $131 million in USDT held across four wallets linked to the Central Bank of Iran. The restrictions followed a July 14 update to the US Treasury’s sanctions list. OFAC added the wallet addresses to the bank’s existing entry.

This freeze linked to Iran shows how much control an issuer retains over tokens like USDT moving on a public blockchain. Though the tokens remain visible in the wallets and US authorities did not seize them, their holders can no longer transfer or redeem the affected USDT.

OFAC added four wallets to an existing designation

The Treasury’s Office of Foreign Assets Control, or OFAC, has sanctioned the Central Bank of Iran since 2019. Its July 14 update added four more cryptocurrency addresses as identifiers connected to the bank. It’s not a new designation.

All four addresses operate on TRON, a blockchain widely used for moving USDT. Publishing them allows exchanges, custodians and compliance services to screen transactions involving the wallets.

Independent on-chain analyst Specter also traced the four wallets to both the Central Bank of Iran and activity linked to the Islamic Revolutionary Guard Corps (IRGC) before Treasury’s public confirmation. This attribution comes from Specter’s own blockchain analysis. OFAC’s official designation cites only the Central Bank of Iran.

Chainalysis reported on July 15 that the addresses had received more than $165 million in stablecoins. According to its onchain analysis, Tether froze the $131 million that remained accessible when the restrictions took effect. Some funds had already moved elsewhere.

Chainalysis also traced earlier funding to an institutional liquidity provider and an Asia-based payment processor. It did not publicly identify either business, leaving an important part of the transaction route unresolved.

How Tether can make USDT unusable

USDT transactions appear on public blockchains, but Tether issues and administers the token. Its smart contracts include controls that can prevent designated addresses from sending or redeeming their balances.

That mechanism does not erase transactions or remove a balance from a wallet, so it remains visible onchain. But it locks the balance. The holder can no longer use the USDT for transactions. Freezing USDT linked to Iran doesn’t mean that Tether or any other authority took control or ownership of the balances. Asset seizures would require a separate legal process.

Almost $475 million has now been blocked

The latest $131 million is not the first freeze involving addresses attributed to Iran’s central bank. The action brings the total Tether has blocked to almost $475 million across wallets identified by OFAC as belonging to the institution. That total includes roughly $344 million frozen previously in April, which was tied to the same underlying OFAC blockade against the Central Bank of Iran. Last month OFAC also sanctioned major Iranian crypto exchanges, which the Central Bank had reportedly used to move funds in and out of stablecoins, which indicates a broader enforcement pattern beyond wallet freezes.

OFAC has cautioned that the wallet identifiers it publishes may not represent all addresses linked to a designated entity. In this case, the four TRON wallets disclosed in the July update may not capture the full set of addresses tied to Iran’s central bank, leaving open the possibility of additional, undisclosed wallets. Separate blockchain analysis points to a larger overall footprint: Elliptic estimates that Iran’s central bank has accumulated at least $507 million in USDT in total, used to support the rial. The gap between Elliptic’s estimate and the $475 million frozen so far reinforces OFAC’s own caveat that unidentified wallets may still be out there.

The next question is whether US authorities pursue seizure or forfeiture proceedings against the frozen balances. Investigators have not disclosed how much money moved before the restrictions. They may also identify additional wallets linked to the central bank. It has not transferred those funds to the US government, and it does not cover every crypto wallet associated with Iran or its central bank.

Where issuer control meets crypto’s original premise

Iran has faced restrictions on access to the global banking system for years, and stablecoins have offered a workaround. Dollar-linked value and international liquidity without a traditional correspondent bank. This action shows the limits of that workaround.

Crypto’s founding pitch was self-custody: control your own keys, and no bank, government, or company can touch your money. “Not your keys, not your coins” became the shorthand. The risk was always framed as someone else holding your wallet.

Now we see a version of the risk nobody built that phrase for. Nobody took the keys. Nobody seized the wallets. The Central Bank of Iran still controls those four addresses, and the tokens are still sitting there, visible on TRON, exactly where they were. Tether didn’t need the keys at all. It froze the token at the contract level, the same mechanism it has always held over USDT.

It’s less a break-in than a wall built at the exit. The wallet still opens. The tokens still exist. They just can’t go anywhere.

That distinction is what draws the comparison to central bank digital currencies, where a central authority holds that same freezing power over its own currency by design. No, this was not a purely internal decision on Tether’s part. The freeze followed a public OFAC designation, an external and published trigger. But for someone holding a centrally issued stablecoin, the practical experience, funds visible, funds unusable, looks a lot like what critics warn a CBDC could do.
CrispyBull Awards 2026 Recognize Bitso, Coinbase and Circle with Regional Honors

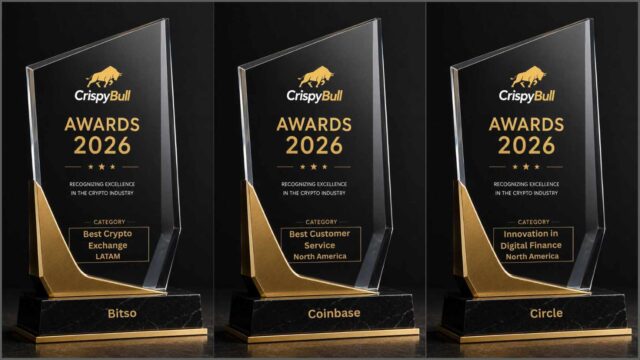
CrispyBull Awards 2026 recognizing Bitso, Coinbase and Circle as regional winners for crypto exchange, customer service and digital finance innovation.

The CrispyBull Awards 2026 continue with another group of regional winners, recognizing companies that have distinguished themselves through market leadership, customer experience and financial innovation.

Following the announcement of the first award recipients earlier this year, CrispyBull is now recognizing three organizations that have made a measurable impact within their respective regions and categories.

The latest winners are:

  • Best Crypto Exchange LATAM 2026 — Bitso
  • Best Customer Service North America 2026 — Coinbase
  • Innovation in Digital Finance North America 2026 — Circle

Each award recipient was evaluated based on product quality, customer experience, market reputation, regulatory standing, innovation and long-term contribution to the digital asset industry.

As with every category, these awards focus on consistent performance over time, not just short-term success.

Best Crypto Exchange LATAM 2026 — Bitso

Latin America has become one of the world’s fastest-growing cryptocurrency markets. Economic uncertainty, inflation and increasing demand for efficient cross-border payments have accelerated crypto adoption across the region.

Within that landscape, Bitso has established itself as one of the most influential exchanges serving Latin American users.

Founded in Mexico, the company has expanded across multiple markets while building a reputation for reliability, regulatory engagement and products tailored to local financial needs.

Instead of copying the playbook of global exchanges, Bitso has concentrated on addressing the specific financial challenges faced across the region. Its platform supports local currencies across several countries and offers accessible on-ramps and off-ramps. It has already become an important infrastructure provider for cross-border payments throughout Latin America.

The company has also invested heavily in compliance and operational resilience while expanding services retail customers and institutional clients alike.

The CrispyBull editorial team believes Bitso represents the strongest combination of regional expertise, customer trust and practical utility in the Latin American market today.

Best Customer Service North America 2026 — Coinbase

Excellent customer support has become one of the defining characteristics of successful digital asset platforms.

As cryptocurrency adoption expands beyond early adopters, users increasingly expect the same level of service they receive from established financial institutions.

Coinbase has invested significantly in improving that experience.

While no large exchange is immune from support challenges during periods of rapid growth, Coinbase has spent recent years strengthening customer assistance through expanded support channels, enhanced account recovery processes, clearer educational resources and improved security tools.

The company has also continued to introduce features to help customers better protect their accounts, manage transactions and resolve issues more efficiently.

Customer service extends beyond responding to support tickets. It includes product design, transparency, security communication and the overall experience users encounter throughout their relationship with a platform. Across these areas, Coinbase has demonstrated consistent progress while serving one of the largest customer bases in North America.

The CrispyBull Awards recognize organizations that continue improving. Coinbase’s hits that mark with its ongoing investment in customer experience.

Innovation in Digital Finance North America 2026 — Circle

Innovation in financial technology is not always defined by launching the most visible consumer product. Sometimes it comes from building the infrastructure that enables the broader digital economy.

Circle has become one of the most influential companies operating in that space. The company has played a central role in advancing regulated stablecoin infrastructure through USDC while developing payment, settlement and financial services that connect traditional finance with blockchain technology.

As governments, banks and financial institutions continue exploring tokenized money and digital payments, Circle has positioned itself as one of the companies helping shape that transition.

Its work extends beyond issuing a stablecoin. Circle has consistently focused on compliance, transparency and institutional-grade infrastructure while expanding services that support businesses, developers and financial institutions.

During the past year, the company has continued strengthening its role within regulated digital finance, reinforcing its position as an important bridge between traditional financial systems and blockchain-based payments.

The CrispyBull editorial team believes Circle’s long-term contribution to regulated digital finance and payment infrastructure distinguishes it from its peers.

Recognizing excellence across global markets

One of the goals of the CrispyBull Awards is to acknowledge that excellence often looks different across regions.

Markets mature at different speeds. They operate under different regulatory environments and serve users with different financial needs. Regional awards allow companies to be evaluated within the context of the markets they serve instead of a one-size-fits-all global comparison.

This year’s regional winners illustrate that diversity.

Bitso has become an essential part of Latin America’s crypto ecosystem by addressing practical financial challenges unique to the region.

Coinbase continues raising expectations for customer experience within one of the world’s largest digital asset markets.

Circle is helping define the infrastructure that could support the next generation of digital finance.

Although they operate in different segments of the industry, each company has demonstrated a sustained commitment to improving how individuals and businesses interact with digital assets.

More CrispyBull Awards winners will follow

The CrispyBull Awards 2026 will continue throughout the year as additional regional and global winners are announced across multiple categories.

Nominations for the 2026 awards will remain open until July 31, 2026, after which the editorial team will finalize evaluations for the remaining categories.

The awards aim to recognize organizations that have delivered meaningful value to users while contributing to the continued development of the cryptocurrency and digital finance industries. Further winners will be revealed as the evaluation process progresses.

Japan Passes Crypto Law That Reshapes Market Oversight

TL;DR

  • Japan has passed a law moving crypto into its financial-markets framework, but it is not yet in force.
  • The reform introduces insider-trading rules, disclosures, and stronger enforcement for crypto markets.
  • Key details, including implementation rules and timelines, will determine how the law works in practice.

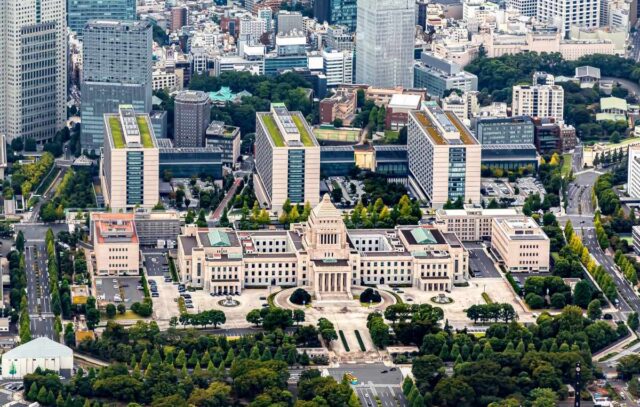
Japan’s parliament has passed legislation that will move crypto trading into the country’s financial-markets framework. Exchanges, issuers and other market participants will face rules that look more like those used in traditional financial markets, including disclosure requirements and insider-trading controls.

Technically, Japan’s crypto regulation isn’t in effect yet. The Financial Services Agency still needs to finish the implementing rules and the transition process. Reuters, citing NHK, reported that the government will set an effective date within one year of the law’s promulgation.

The reform comes as crypto use in Japan has grown to more than 13–14 million accounts, bringing retail participation closer to traditional financial markets. It also reflects lessons from past exchange hacks and security incidents. In scale, this marks the most significant overhaul of Japan’s crypto framework since the 2017 Payment Services Act, which itself followed the Mt. Gox collapse.

Crypto moves into Japan’s investment rulebook with new law

The House of Councillors approved the legislation on July 15, completing its passage through parliament after the House of Representatives had approved it on June 11. Passage through both chambers is required to enact legislation in Japan’s Diet system. Japan’s FSA records the measure as enacted on July 15.

Until now, Japan has regulated crypto mainly under the Payment Services Act, reflecting its use in payments and transfers. The new framework moves crypto oversight into the Financial Instruments and Exchange Act, which governs investment markets and financial businesses.

Under the new framework, the FSA will define crypto assets such as Bitcoin and other tokens as a distinct category of financial product, separate from shares and bonds. This allows regulators to apply rules tailored to crypto while using the stronger conduct and enforcement structure of financial-markets law.

The reclassification also clears a legal obstacle that had prevented investment funds from holding crypto, though further rule changes would still be needed before any ETF could launch.

Existing securities firms will need an amended registration before offering regulated crypto services. Current crypto exchanges will also have to adapt to the new registration and compliance framework once the transition details are set.

Insider trading and disclosure rules become central

With crypto now treated more like an investment market, the law introduces a direct ban on insider trading. The rules target people who trade before material non-public information becomes available to the wider market.

For crypto markets, this could include information about a token issuer or an exchange’s decision to list or remove an asset. It may also involve a large planned transaction. The framework also covers people who receive inside information from someone in a privileged position.

Japan’s new law regulating crypto also expands public disclosure duties. If the issuer of a token is identifiable, disclosures may cover the asset’s functions, supply and underlying technology. The regulation will also require certain issuers to publish updates after important events and provide annual information in defined circumstances.

The disclosure process for Bitcoin and similar assets without a conventional issuer will differ from those of a company or centrally issued token. The FSA materials must account for those differences as it can not impose a single model across all assets.

Penalties and customer protections get stronger

Alongside trading rules, the law also tightens enforcement and increases the maximum punishment for operating an unregistered crypto trading business in Japan. The prison term rises from three years to ten years. The maximum fine for an individual increases from 3 million yen to 10 million yen.

Regulators will also gain stronger tools against unfair trading. Crypto-related insider dealing, market manipulation and misleading conduct can fall within surveillance, financial-penalty and investigative processes used for investment markets.

Customer protection is another focus. Trading businesses will need compensation reserves for certain losses caused by unauthorized outflows of customer assets. This requirement specifically follows experiences from past exchange hacks and security breaches. The detailed method for calculating those reserves remains unresolved and will depend on implementing standards.

Together, these measures shift the emphasis from treating exchanges mainly as payment-service operators to supervising them as investment-market businesses. Yet the law does not eliminate crypto’s technical risks or guarantee compensation after every loss.

The overhaul isn’t finished yet

Japan’s new law reclassifies crypto, but key pieces are still unresolved.

A companion tax proposal would cut Japan’s crypto tax rate from as high as 55% to a flat 20%, likely starting around 2028, but the Diet has not passed it. Regulators are also weighing whether investment funds should be allowed to hold crypto directly, a step the Tokyo Stock Exchange operator says could open the door to ETF listings as early as 2027.

Those developments are moving on separate tracks. Their timing will depend in part on how quickly this law is implemented.

The FSA still needs to publish secondary rules, define registration and disclosure standards, and set the start date for the new regime. Exchanges, issuers and investors are waiting for that timetable before the next phase can begin.

UK and US Align on Stablecoin Standards and Safeguards

TL;DR

  • The UK-US joint stablecoin statement sets shared standards for backing, redemption and holder protection across both markets.
  • The agreement signals policy alignment between two major financial systems.
  • Broader Taskforce recommendations outline future cooperation on tokenised assets and regulatory coordination.

The UK and US have agreed on shared principles for stablecoins used across their financial markets. The governments want stronger coordination on backing assets, redemptions and protections for holders if an issuer fails.

The UK-US joint statment on stablecoin, published on July 14, 2026, gives regulators and companies a clearer policy direction. However, it does not create mutual recognition of stablecoins or automatic access to both markets. Each country will continue to apply its own laws and regulatory process when approving issuers and grant access.

The agreement sets a common regulatory baseline

HM Treasury and the US Treasury released the joint statement on July 14. It forms part of the Transatlantic Taskforce for Markets of the Future, which the two governments established in September 2025. The statement was released alongside a broader 10-point set of Taskforce recommendations, and stems in part from that document. While the recommendations establish the wider policy agenda, the joint statement focuses specifically on stablecoins.

The statement says stablecoins presented as money should have backing of at least one-to-one. That backing should consist of high-quality, liquid assets, although each country will define which assets qualify under its own framework.

The governments also support segregating reserve assets from an issuer’s own funds. In practical terms, this aims to stop an issuer from treating customer backing as ordinary corporate money. Regulated issuers should also provide timely redemption and disclose the legal rights attached to their tokens.

If an issuer becomes insolvent, holders should have a clear and protected claim on the reserves. The statement supports giving that claim priority over other creditors, subject to the laws of each jurisdiction.

Cross-border access remains a future step

The most significant goal is a formal pathway for stablecoins issued in one country to reach the other country’s market. Though the UK-US stablecoin statement says the governments intend to explore that pathway, no access mechanism has been approved yet.

The two countries maintain different regulatory structures. The UK splits responsibility among the Financial Conduct Authority, the Bank of England and HM Treasury. The US framework involves federal legislation and several regulators, with implementing rules still developing.

The joint position seeks comparable outcomes for comparable risks. It does not require identical rules. Therefore, reserve standards, supervision and the treatment of systemically important issuers may still differ.

Right now, existing tokens can’t operate freely on both sides of the Atlantic. The UK doesn’t automatically recognise US-regulated issuers, and UK-regulated issuers can’t access the US market without separate approval.

Tokenised markets are part of the wider plan

Stablecoins are only one part of the Taskforce’s wider recommendations document. That document outlines a plan for the two governments to engage a private-sector group for one year to test cross-border uses of tokenised assets and share technical practices. However, officials still need to decide the group’s structure, participants and specific use cases. The recommendations also say the joint statement will not replace or predetermine domestic regulatory processes.

The same recommendations document tasks regulators including the FCA, Bank of England, CFTC and SEC with seeking common approaches in selected areas. These include when a tokenised securities transaction becomes legally final. They will also examine whether stablecoins or tokenised money-market funds can serve as collateral at central counterparties, which stand between buyers and sellers to manage counterparty risk.

The work could reduce friction for companies operating in both markets. Still, common principles must become detailed rules before firms can rely on them in live transactions.

The next test is practical market access

The joint statement narrows some of the policy distance between the UK and the US, two major financial centres. But it leaves the harder questions for later: which reserve assets qualify, how regulators will vet issuers from across the Atlantic, and what happens when a stablecoin becomes too big to fail quietly.

That’s the gap between a policy statement and a market. Until a concrete access mechanism exists, or domestic rules catch up with these principles, a UK-regulated stablecoin still can’t sell itself as fit for the US market, and vice versa.

CFTC Steps In After Kalshi Already Cancelled Michigan Trades

TL;DR

  • The CFTC ordered Kalshi to honor previously executed Michigan trades despite a state directive to cancel them.
  • Kalshi had already unwound those trades under a self-certified rule before the CFTC intervened and blocked that rule.
  • The dispute highlights an unresolved conflict between federal derivatives oversight and state gambling enforcement.

The US Commodity Futures Trading Commission (CFTC) has ordered Kalshi to honor open trades involving Michigan residents. The regulator also blocked an emergency rule the prediction-market platform had used to unwind those same positions before the CFTC could act on it.

The decision puts the federal regulator in direct conflict with a Michigan court that wanted the trades voided, cancelled and refunded. However, the CFTC’s order does not overturn the state court’s decision or settle whether Kalshi may offer new sports-related contracts in Michigan.

How the dispute led to the unwind

Michigan Attorney General Dana Nessel sued Kalshi in March, alleging that its sports event contracts amount to unlicensed online gambling. In contrast, Kalshi describes the products as federally regulated derivatives.

On June 25, a federal judge returned the case to state court after finding that Michigan’s claims did not belong in federal court. The ruling rejected Kalshi’s argument that federal commodities law completely displaced the state’s causes of action.

On June 29, an Ingham County judge issued a temporary restraining order. It prohibited Kalshi from offering or facilitating products classified as internet sports betting for people in Michigan. The court also required state-compliant geolocation controls.

The court later instructed Kalshi to close certain positions held by Michigan traders. In July 6 correspondence, it clarified that those positions had to be voided, cancelled and refunded.

Kalshi’s rule filing and the executed unwind

In response, Kalshi filed an emergency rule with the CFTC on July 12. As a designated contract market, the company can self-certify rule changes. That means these rules take effect immediately upon filing without prior approval, subject to later review. The proposed rule would have liquidated the affected positions at their current market value, with Kalshi covering any shortfall relative to customers’ original costs.

Kalshi proceeded to unwind and refund the affected Michigan trades under that self-certified rule in order to comply with the court’s directive. The company later said it faced potential contempt exposure under the court’s order if it failed to act.

The CFTC steps in after the fact

On July 14, the CFTC stayed that emergency rule. It then used separate emergency authority to direct Kalshi to fulfill the positions through its normal process, effectively requiring the platform to restore trades it had already cancelled. Kalshi’s Head of Enforcement, Robert DeNault, said the company “already acted and unwound the trades, as the Michigan court order required us to do,” describing an “impossible position” between conflicting state and federal directives.

The regulator argued that cancelling executed trades could weaken confidence across derivatives markets. Traders need to know that a completed transaction will not be removed later because another authority objects to the product.

That concern sits at the center of the CFTC Kalshi order. The Commission said even a limited forced liquidation could distort prices and affect related positions. It also warned that allowing individual states to unwind federally regulated trades could create different outcomes for traders based on location.

Kalshi is a designated contract market (DCM) supervised by the CFTC. The agency treats its event contracts as swaps under federal commodities law. On that basis, the Commission says it has exclusive authority over those transactions.

For now, the order stays Kalshi’s emergency rule while the CFTC reviews it. The applicable process gives the Commission 90 days for that review and includes a 30-day public-comment period. Still, the separate direction to fulfill the trades applies during the dispute.

The jurisdiction question remains unsettled

Michigan takes a different position. The state says sports-related contracts offered without its approval violate state gambling laws, even when they trade on a federally registered market.

That disagreement reaches beyond one set of open positions. The CFTC says it has filed cases against nine states to defend its jurisdiction. Meanwhile, states and Native American tribes argue that platforms should not use federal derivatives regulation to bypass local gambling rules.

However, the remand did not decide the entire jurisdictional dispute. The federal judge noted that a state court can still consider federal-law defenses. As a result, the central question about the balance between CFTC authority and state gambling enforcement remains open.

What the order changes for traders

Kalshi told Reuters it was reviewing the CFTC’s decision and weighing its next steps.

For Michigan users, the order settles the fate of trades already made, but little else. It doesn’t authorize new sports contracts in the state: the requirement to geofence Michigan out of new sports event contracts remains in place under the June 29 order, untouched by the CFTC’s intervention. Kalshi still has until Aug. 12 to implement state-compliant geofencing, after which non-compliance triggers daily fines rising from $120,000 to $500,000.

So, the effect of this CFTC order is narrower than many headlines suggests: Kalshi must keep honoring trades that were executed before the state ordered them cancelled, nothing more.

- Advertisement -

FEATURED