For more than a decade, Gibraltar has sought to position itself as a jurisdiction willing to embrace emerging technologies while maintaining a strong regulatory framework. From becoming one of the first jurisdictions to regulate distributed ledger technology (DLT) providers in 2018, to the recent introduction of digital asset legislation, Gibraltar has consistently attempted to bridge traditional finance with the digital economy.
Its latest initiative may prove to be one of its most significant yet.
In April 2026, the Government of Gibraltar announced landmark legislation enabling the issuance of tokenised fund shares. The proposed amendments to the Protected Cell Companies Act would allow certain regulated investment funds to issue shares in digital token form, maintain shareholder registers on blockchain infrastructure and transfer ownership through smart contracts and cryptographic signatures.
Although initially limited to Protected Cell Companies operating as Experienced Investor Funds and subject to approval by the Gibraltar Financial Services Commission (GFSC), the legislation represents far more than a technical adjustment to company law. It signals Gibraltar’s intention to become a leading jurisdiction for the tokenisation of real-world assets.
What exactly is a tokenised share?
In simple terms, tokenisation is the process of converting ownership rights in an asset into a digital token recorded on a blockchain.
Instead of holding a traditional paper share certificate or relying solely on a centralised share register maintained by an administrator, investors hold a digital token representing their ownership interest. That token can potentially be transferred instantly, verified automatically and programmed with embedded compliance rules.
Importantly, Gibraltar’s legislation does not create a new type of share.
Rather, it confirms that a tokenised share carries exactly the same rights and obligations as an ordinary share of the same class. The token merely becomes the digital representation of ownership. Under the proposed law, a share token is expressly recognised as a valid share certificate, while smart contracts and cryptographic signatures are granted full legal effect.
This legal certainty addresses one of the biggest obstacles that has prevented institutional adoption of tokenisation in many jurisdictions.
Why does this matter?
For years, tokenisation has been widely discussed within the blockchain community, yet relatively few projects have achieved meaningful commercial adoption.
The reason is simple. Technology alone is insufficient. Investors need legal certainty, regulators require oversight mechanisms and service providers need clarity on custody, transfers and shareholder rights.
The new Gibraltar framework addresses these concerns by requiring prior GFSC approval before tokenised shares may be issued. It also introduces requirements relating to cybersecurity standards, investor eligibility, custody arrangements and disclosure of risks.
This creates a regulated environment in which innovation can occur without sacrificing investor protection.
Benefits for businesses and fund managers
The most obvious beneficiaries are investment funds.
Traditional fund administration remains heavily dependent on intermediaries, manual reconciliation processes and multiple record-keeping systems.
Tokenisation could streamline many of these functions. Transfers between investors could be completed within minutes rather than days. Dividend distributions may eventually be automated through smart contracts. Fund administrators may reduce operational costs associated with maintaining shareholder registers. Subscription and redemption processes could become more efficient.
For international fund managers, Gibraltar may offer an attractive jurisdiction from which to launch innovative investment products aimed at sophisticated investors seeking exposure to digital assets and blockchain-enabled financial infrastructure.
Private equity and venture capital managers may also benefit.
Imagine a fund investing in early-stage technology companies. Instead of investors waiting many years for liquidity, tokenised interests could potentially facilitate transfers between eligible investors, subject to regulatory restrictions. Family offices represent another interesting opportunity: Many wealthy families utilise Protected Cell Companies to segregate assets and manage investments efficiently. Tokenised ownership interests could simplify succession planning, facilitate transfers between family members and provide greater transparency regarding ownership structures.
Opportunities beyond investment funds
While the legislation currently focuses on Experienced Investor Funds, its broader implications should not be underestimated.
If successful, Gibraltar may eventually expand tokenisation to other corporate structures and asset classes.
Potential future applications include:
Real estate ownership interests
Renewable energy projects
Infrastructure investments
Art and collectibles
Revenue-sharing arrangements
Private company shares
Tokenisation may allow businesses to raise capital from a wider pool of investors while reducing administrative burdens.
A technology company seeking £5 million in growth capital, for example, might one day issue regulated tokenised shares to accredited investors around the world.
Similarly, property developers could divide ownership of large projects into smaller digital units, making investments more accessible to investors who would otherwise be unable to participate.
Challenges remain
Despite the enthusiasm surrounding tokenisation, expectations should remain realistic. The legislation does not automatically create liquid secondary markets. Owning a tokenised share does not necessarily mean an investor will find a buyer immediately. Market infrastructure, trading venues and custody solutions still need to evolve. Cybersecurity risks must also be carefully managed.
Unlike traditional share registers maintained by a single administrator, blockchain-based systems depend on secure private key management and resilient smart contract coding. Errors in programming or failures in custody arrangements could expose investors to losses.
Regulators worldwide are still grappling with questions surrounding taxation, cross-border recognition and anti-money laundering controls in tokenised environments.
Gibraltar’s advantage lies in its agility and willingness to legislate quickly, but maintaining that lead will require continued innovation and engagement with industry participants.
Viewed in isolation, tokenised shares may appear to be a niche development relevant only to blockchain enthusiasts. Viewed strategically, however, they fit into a much larger picture.
Gibraltar has long relied on specialist financial services, online gaming and niche regulatory expertise to compete internationally despite its small size.
Tokenisation offers an opportunity to build upon that reputation.
For entrepreneurs and investors looking for a jurisdiction where digital finance can operate within a recognised legal framework, Gibraltar’s latest initiative sends a clear message: the Rock intends not merely to participate in the future of finance, but to help shape it.
Whether tokenised shares become mainstream remains uncertain. What is certain, however, is that Gibraltar has once again demonstrated its willingness to move ahead of larger jurisdictions and provide businesses with a regulatory laboratory for the next generation of financial products.
Japan's stablecoin market is entering a new phase as banks, fintech firms, and blockchain companies roll out regulated digital currencies under one of the world's most developed legal frameworks.
TL;DR
SBI Group and Startale Group have launched JPYSC, Japan’s first trust-bank-backed yen stablecoin.
The launch expands Japan’s regulated stablecoin ecosystem, where different issuers operate under distinct legal frameworks.
As banks and fintech firms introduce new digital currencies, Japan is positioning itself as a leader in regulated blockchain-based payments.
SBI Group and Singapore-based blockchain infrastructure company Startale Group have launched JPYSC, introducing Japan’s first trust-bank-backed yen stablecoin. The announcement highlights how Japan’s regulated stablecoin market is rapidly expanding under one of the world’s earliest dedicated legal frameworks for fiat-backed digital assets.
This launch shows that Japan’s stablecoin market is evolving beyond a single issuer. Banks, trust institutions, and fintech firms are adopting different regulatory models for payments, settlements, and tokenized financial services.
JPYSC Adds a New Regulatory Model
JPYSC isn’t Japan’s first regulated stablecoin. That distinction belongs to JPYC, which became the country’s first legally recognized yen-backed stablecoin under the fund-transfer framework in October 2025.
Instead, JPYSC is the first trust-bank-backed yen stablecoin, issued through SBI Shinsei Trust Bank under the country’s trust banking framework. The structure allows for larger-value transactions than the fund-transfer model, which remains subject to a 1 million yen transfer cap. At launch, JPYSC is only available to clients of SBI VC Trade. Transfers to external wallets have not yet been enabled.
Japan’s Stablecoin Market Is Growing
Japan’s ecosystem has expanded steadily since its dedicated legal framework took effect in June 2023, establishing rules for stablecoins issued by banks, trust companies, and licensed fund-transfer businesses.
JPYC was the first project to launch under that framework. JPYSC now introduces a separate trust-bank model aimed primarily at institutional settlement and tokenized financial assets.
The market is also attracting international issuers. Ripple’s RLUSD, a US dollar-backed stablecoin, has been approved for distribution in Japan through SBI. It gives businesses access to a regulated foreign-issued stablecoin alongside domestic yen-backed alternatives.
Meanwhile, Mitsubishi UFJ Financial Group, Sumitomo Mitsui Financial Group, and Mizuho Financial Group are jointly developing a yen-backed stablecoin project. The consortium targets live transactions by the end of Japan’s fiscal 2026 in March 2027.
Japan’s stablecoin projects aren’t competing directly with global dollar-backed stablecoins such as USDT and USDC. They are largely focused on regulated payments, digital settlements, and tokenized financial assets.
The country’s legal framework has encouraged financial institutions to experiment with blockchain-based payment infrastructure while maintaining oversight of reserves, redemption, and consumer protection. Different licensing models also allow issuers to target specific use cases instead of competing within a single market segment.
As a result, Japan’s stablecoin ecosystem is becoming increasingly specialized. Trust-bank issuers, fintech firms, and traditional banks each serve different parts of the market.
The launch of JPYSC signals that Japan is entering a new phase of stablecoin development. The discussion centers alot on which models are best suited for retail payments, institutional settlements, and tokenized financial markets.
With additional projects expected from Japan’s largest banks and broader adoption of tokenized assets, Japan’s stablecoin market is shifting from regulatory experimentation toward real-world financial infrastructure.
Law enforcement groups, advocacy organizations, and crypto industry stakeholders are debating whether provisions in the CLARITY Act strike the right balance between innovation and financial crime safeguards.
Alt Text
TL;DR
The CLARITY Act is facing opposition from law enforcement groups, Catholic organizations, and anti-trafficking advocates raising concerns over Section 604.
Critics argue the provision could create gaps in anti-money laundering oversight for some decentralized finance participants.
The debate arrives as the bill advances through the Senate process, adding new uncertainty to its legislative path.
Just as supporters of this major U.S. crypto market structure bill appeared to be gaining momentum, a new wave of criticism has emerged. The opposition to the CLARITY Act has expanded in recent days as law enforcement organizations, Catholic groups, and anti-trafficking advocates raise concerns about provisions they believe could weaken safeguards against illicit financial activity.
The timing is notable. After clearing the Senate Banking Committee in a 15-9 vote in May, the legislation was placed on the Senate legislative calendar on June 1. This was an important procedural step before potential floor consideration. However, lawmakers still face additional negotiations over the Senate’s version of the bill and its eventual reconciliation with House-passed legislation. Supporters have pushed for congressional action before the July 4 recess. This growing criticism could now complicate efforts to keep the bill moving forward.
Critics Focus on Section 604
Much of the debate centers on Section 604, a provision that addresses certain participants in decentralized finance, or DeFi. Critics argue the language could exempt some blockchain developers and infrastructure providers from compliance requirements that help authorities monitor suspicious financial activity.
Law enforcement groups and advocacy organizations have warned that such provisions and DeFi exemptions could create gaps in oversight. It would effectively make it more difficult to investigate money laundering, sanctions evasion, human trafficking, and other financial crimes. Several organizations have urged lawmakers to revise the language before advancing the bill further.
Supporters of the legislation reject those claims. They argue that the provision simply clarifies which actors should be subject to financial regulations. It does not eliminate existing anti-money laundering protections.
An Expanding Coalition of Opponents
The latest concerns have attracted attention because they come from a diverse group of organizations rather than traditional crypto skeptics alone.
Catholic advocacy groups have joined law enforcement associations and anti-trafficking organizations in questioning whether the legislation adequately protects against illicit financial activity. Their objections have shifted part of the debate away from innovation and regulatory clarity toward public safety and enforcement concerns.
The growing coalition has given lawmakers additional issues to consider as the bill enters a critical stage of the legislative process.
Supporters Say Regulatory Clarity Remains Essential
Industry advocates continue to argue that the United States needs a clearer framework for digital assets. They say years of regulatory uncertainty have created confusion for developers, investors, and businesses operating in the sector.
Supporters also contend that critics are mischaracterizing the bill’s treatment of decentralized technologies. In their view, software developers and blockchain infrastructure providers should not automatically be regulated as financial intermediaries when they do not control customer assets or directly process transactions.
As a result, the debate increasingly centers on how decentralized systems should fit within existing regulatory structures. It’s much less about whether crypto markets need clearer rules.
The expanding opposition to the CLARITY Act arrives at a sensitive moment for supporters. Placing the bill on the Senate calendar was a significant step forward, but Senate leadership has not yet scheduled floor consideration of the legislation.
That leaves lawmakers balancing competing priorities from industry participants, enforcement officials, advocacy groups, and policy experts. Any effort to revise disputed provisions could slow the process and potentially reopen negotiations over key sections of the bill.
For supporters, the challenge is no longer simply advancing the legislation through committee. It is convincing senators that the framework can support innovation while preserving effective safeguards against financial crime.
Whether the concerns surrounding Section 604 lead to amendments or remain a point of political debate, the opposition movement to the CLARITY Act has introduced a new obstacle just as the bill appeared to be moving closer to Senate action.
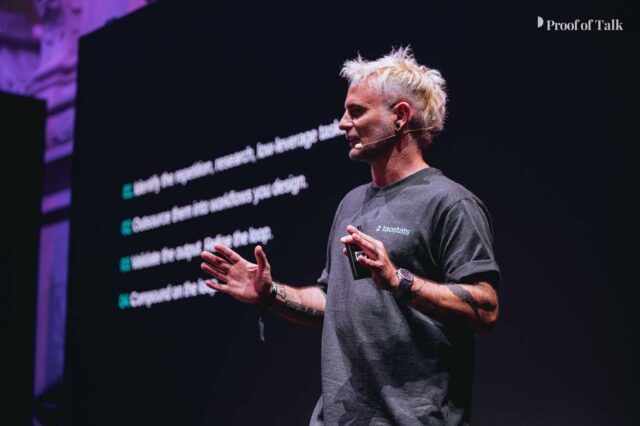
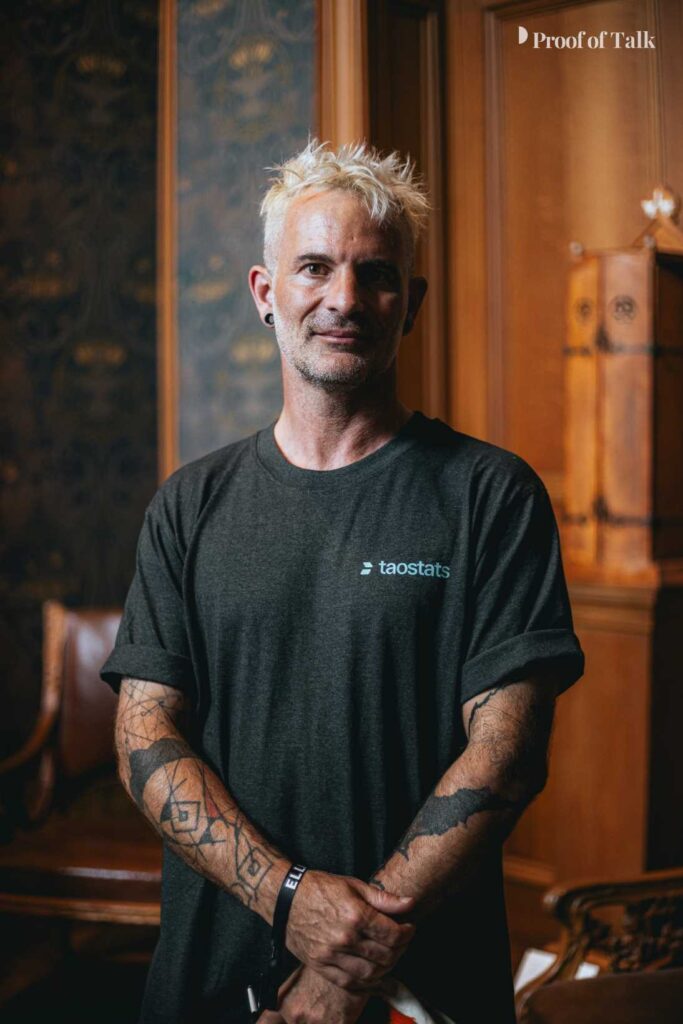
Marcus "Mog" Graichen on stage at Proof of Talk 2026, Paris.
Photo: Flora Metayer.
We are sitting at Proof of Talk in Paris, a summit drawing an increasingly institutional crowd to the question of what decentralized finance and AI become at scale. The room outside is full of asset managers, sovereign wealth fund representatives, and policy people from three continents. And Marcus Graichen, known to virtually everyone in the Bittensor ecosystem simply as Mog, and the founder of Taostats, the network’s leading analytics platform, is explaining what it was like to update an HTML page every morning at nine o’clock.”
“We started as one man making an HTML site,” he says, without any particular sense that this is an unusual origin story for someone whose platform now processes the financial activity of one of the fastest-growing decentralized AI networks in the world. “I wasn’t seeking venture capital funding for that. It was just a hobby project.”
Mog is not what most institutional investors expect when they sit down with a leading infrastructure founder in this space. He knows it, and he seems to find it mildly amusing. “They always leave a little surprised,” he says. “I’m not sure I’m the standard persona that’s often put in front of these people.”
He is a multimedia graduate. He spent four years in Zanzibar running the digital operations of a professional kiteboarding company: websites, photography, marketing, coaching. He comes from two decades in web development and online publishing, not from machine learning or cryptography. And it turns out that background is precisely why Taostats exists, and why it works.
It Started With a Spreadsheet
Mog’s entry into Bittensor was through the front door that most serious participants use: he invested. In the early days of the network, there was a single subnet performing a task. Not particularly well, but well enough to demonstrate that the underlying architecture was sound. Returns were variable, so Mog kept spreadsheets, as he always had.
The problem was that getting the data to fill those spreadsheets required pulling it directly from the chain. It was technically demanding, and delivered nothing a normal person could read at a glance. The Discord channels weren’t much better.
“So initially, I just shared a spreadsheet with some extra columns of data that I thought related to actual funding and percentage APY and changes in that acquisition of funds,” he explains. “TaoStats formed in that sense that it was a shared visualization of the incentive layer of the network.”
That phrase “shared visualization of the incentive layer” is a precise description of something that the network was missing at the time. It had no public-facing interface. Participation required comfort with command lines and raw data outputs. Mog built the thing he personally needed, shared it, and watched other people need it too.
The Translation Problem
As the platform grew from spreadsheet to website, the second challenge came into focus: explaining what Bittensor was to people who had no machine learning background whatsoever. This is where Mog’s instinct for translation, honed across years of explaining digital businesses to clients and readers, found its purpose.
“It was early days of ChatGPT,” he says. “I used to say: when you ask ChatGPT a question, it’s like having one university professor in front of you, asking him a question and getting a response back, and that’s your response. What Bittensor was doing was filling a room full of a hundred professors and then asking that question to all of them, and then grading those answers, and then giving you back the best, however many you wanted, the top ten, the top fifty.”
It is, still, one of the clearest explanations of decentralized AI inference in plain language. “And people say: oh, I get that. That’s an amazing concept.”
Building Without a Cheque
The funding story of Taostats is unusual enough that it deserves to be told plainly, because it runs against almost every convention of how technology infrastructure gets built.
There was no seed round. There was no Series A. There was, for a period, a validator naming service. Mog spotted early that validators were about to compete for delegated stake, and that being identifiable would matter. He charged a modest fee, calibrated to what validators were earning, and when anyone questioned it, he had a ready answer drawn from his publishing background.
“I ran a female kitesurfing magazine online,” he says, “and there were women making startup bikini brands who will pay five thousand dollars for a month to get their product in front of a few hundred potential customers who might actually click through. You are looking at attracting thousands, if not tens of thousands, hundreds of thousands, millions of delegation. I’m asking for a very small amount.”
When staking went live, something unexpected happened. A couple of early miners who no longer wanted to run infrastructure joined as partners. Their collective stake pushed the Taostats validator into the top tier. And then, because Taostats was the thing everyone in the ecosystem visited every day, delegators started directing their stake there too.
“I actually felt guilt for this. I don’t deserve this. I shouldn’t have this.”
Instead of taking the runway and moving on, he went back to building. Subnets. API access. Education. Always managing the business carefully enough to survive a bear market. Always reinvesting rather than extracting. Jacob Steeves, the co-founder of Bittensor, kept telling him what to build next.
Turning Down DCG
This philosophy extended to equity conversations. There were approaches from people whose names would have looked impressive on a cap table. One of them was Barry Silbert of DCG.
“He said: we would like to support you. We don’t want to get involved. We love what you’re doing, but we’d like a stake in this.” Mog took the conversation seriously, went away and worked on the business structure that would make Taostats ready for that kind of partner. He came back, and turned it down.
“I can’t lie. All I would use your money for is to buy TAO. Which actually would have been a fantastic choice at the time. But I couldn’t do that. I’m not just taking your money to buy TAO. We don’t need it.”
His standing advice to founders in the ecosystem reflects what he lived: “Avoid equity until you really need it. Because the longer you hold onto your hundred percent, the more you have on the table to offer when it does come time. And also, take equity from those that are going to add value to your business.”
As of the day we speak in Paris, Taostats has still never taken on equity. “I feel like I know what I would need from a partner. We haven’t found that yet.”
What Institutional Investors Get Wrong
Photo: THOMAS_FRANCIUS
Grayscale has launched an ETF around Bittensor. Asset managers are arriving. The summit we are at exists precisely because these conversations are no longer hypothetical. So what does Mog see when they sit down across from him?
“It’s not a misreading,” he says carefully. “It’s a confusion. A confusion of allocation of capital.”
The confusion, specifically, is that institutional investors arrive asking for the VIP line, the preferential channel to acquire tokens. They assume the conversation is about token acquisition, when the actual question is more fundamental: are you investing in a business, a product, a founder, or a token? And are you bringing anything with you beyond capital?
“One of the most important things you can do as an investor is put money into something that you can add value to,” Mog says. “When people come to us and say, we’ve got an OTC, do you want to sell us OTC? And I say, well, what benefit is there for me to give you my tokens, either at a discount or at face value from my owner treasury, if you’re not adding something to it? For me, it’s a marketing cost. Are you helping me? Are you putting my name out there? Are you bringing in expertise and value?”
It is an inversion of the usual dynamic, the founder questioning the investor rather than the other way around. But it reflects something distinctive about how Bittensor’s ecosystem has developed: accountability runs in both directions.
The $30,000-a-Month Problem That Built a Business
Some of the most interesting companies get started because the founder couldn’t solve their own cost problem any other way.
Taostats was spending around $30,000 a month on RPC infrastructure, the technical layer that allows any platform to query a blockchain and retrieve data. Initially from third-party providers, then in-house, but the costs kept climbing as the platform scaled. Even with talented infrastructure developers on the team, there was an honest internal acknowledgment: there are people out there who can do this better than us.
“They said: we should outsource this,” Mog recalls. “But rather than outsourcing it to a third-party provider who’s basically charging what we are, if we build a subnet out of this, we incentivize people to do this better.”
How Competition Prices a Commodity
That became Blockmachine, a Bittensor subnet focused on decentralized RPC infrastructure. The mechanism it introduced was novel: miners set their own prices. So Taostats set its own internally-run miners as the baseline price to compete against. Then they would buy from the most competitive, fastest, and most reliable, according to scoring metrics.
“What we did was set up and ran the initial miners at the same cost that we had been supplying ourselves in-house. We said: we’re not going to compete, but we are going to provide the same infrastructure to ourselves. You’ve got a baseline to compete against.”
The result, he says, was immediate and striking. Miners competed the price down to a fraction of the baseline within weeks of launch.
“You can see how much money we saved as a company.”
The broader point here is about what Bittensor’s incentive structure does to a market. The top miner does not sit pretty. If they are not being challenged, they will raise their prices until competition arrives and forces them back down. The system reaches equilibrium because those most capable of delivering will price the commodity instead of a central authority setting rates.
“Rather than a centralized provider setting the pricing to a single vendor,” Mog says, “it’s the capability underneath that’s being priced.”
Blockmachine is now at the stage of onboarding a scaled marketing and business development team. The pitch to any developer currently using one of the existing RPC providers is almost comically simple: swap the URL, pay less, and if it doesn’t work, swap back.
The Thin Line Between Permissionless and Accountable
The interview had been going for some time when we arrived at the question that sits underneath every conversation about decentralized systems and institutional adoption. If one entity controls a large share of staked tokens on a supposedly decentralized network, at what point does the word “decentralized” stop meaning anything?
Mog gently corrected the framing. The concentration I had identified was in the top validator, Taobot, which had accumulated stake primarily because it charges a zero percent fee. Its returns are fractionally better for delegators who are not paying attention to what their stake is funding. Taostats, by comparison, takes a small percentage to fund its team and infrastructure. Taobot is not a single whale; it is the result of an information gap.
“To the uneducated, who are just looking at returns and don’t necessarily see the value of staking to someone who’s actively trying to build the value of their investment; they say, well, that’s making me half a percent more. I’ll go on them.”
But the deeper question, once corrected, was still worth asking: where is the real line between decentralized and centralized on this network? Mog’s answer was the most direct of the conversation, and he acknowledged without prompting that it places him on one side of a live debate within the ecosystem.
“I believe that permissionless protocols require a level of accountability and responsibility.”
The Case for Centralisation at the Edges
His argument is this: the base layer of Bittensor, the ability to mine, validate, create a subnet , is and should remain completely permissionless. Financial barriers exist, but there is no exclusivity gating. The cost of participation moves with demand, reaches equilibrium, and is governed by code rather than committees.
But the layer above that, the operator layer, the businesses being built on top, cannot be permissionless if they are going to sell to enterprises. Procurement requires invoices. Service level agreements require someone to call when things break. Enterprise buyers need legal accountability.
“That layer is centralized. It’s a company that has fiat payment rails, that is processing funds, that is making decisions, that is paying developers. And I think that’s the thin line that Bittensor walks on very, very well to keep one side completely decentralized and permissionless, and the other side not so much.”
On validation specifically, he acknowledged the controversy directly. The trend in Bittensor subnets is toward the owner-validator model. The person or company that created the subnet handles validation of its outputs instead of distributing that function across a decentralized set of validators. To some in the ecosystem, this feels like centralization by another name. Mog’s view is that it is specialization by necessity.
“The natural transition is that that person knows how to verify and validate their commodity better than anyone else. Having to support a distributed set group of people whose specialty is not that commodity actually harms their ability to iterate and develop and push out advancements.”
However, he notes that governance mechanisms are being developed to give distributed validators recourse if they disagree with how a subnet is being operated.
The Halving That Barely Registered
In December 2025, Bittensor underwent its first halving. Daily token emissions reduced from 7,200 TAO to 3,600, mirroring the mechanism Bitcoin uses to manage supply. In the months before it happened, there was significant anxiety in the ecosystem about what it would mean for miners and validators whose economics depended on those emissions.
I asked Mog if the halving had produced any meaningful exits from the network.
“In a word: no.”
Alphanomics: The Real Test
The reason is a piece of architecture that most outside observers missed. Eight months before the halving, in April 2025, Bittensor had launched dTAO. This new emissions model gave every individual subnet its own alpha token, with its own supply of 21 million and its own halving schedule, separate from TAO’s. Under dTAO, subnets earn in their own alpha tokens, and pay miners and validators in alpha. The TAO halving reduced TAO emissions, but it did not touch alpha emissions.
“Until there is an alpha halvening for any given subnet, there is zero effect on how much miners are being paid.”
What the halving did affect, Mog explains, was liquidity; specifically the depth of each subnet’s liquidity pool, which is fed by both alpha and TAO. Immediately after the halving, with less TAO flowing into pools, smaller amounts of capital could move prices more easily. But liquidity builds over time, particularly in popular subnets with strong emissions.
He coined a word for the economic framework subnets will need to develop before their own alpha halving arrives: alphanomics. Blockmachine is already there. It takes payment in fiat, USDC, or TAO for real services rendered, and pays miners directly from that revenue. Emissions are optional.
“If you turned off emissions, as long as we can still use the incentive mechanism to see who we owe money to and it’s on the chain — we pay those miners and it’s all there. It’s already a business that would be in no way affected by an alpha halvening.”
His view on subnets that are not there yet is unambiguous: “If they haven’t got there by their first halvening, they need to question their position within the network.”
The Plumbing Problem
The final question was the summit’s own question: what is still missing before institutional capital can flow into this space without hesitation?
Mog’s answer did not focus on technical complexity or regulatory clarity in the way many founders do. He went straight to something more mundane, and more intractable.
It’s a board-governed balance sheet that makes it as fluid to take money out as it’s put in.
The problem is not getting money into crypto. The problem is getting it back out. Anyone who has tried to move substantial profits from crypto back into the traditional banking system knows this. The rails going out are unreliable, slow, and often hostile. Institutional investors who manage fiat-denominated portfolios and answer to boards cannot participate in markets where the exit is uncertain.
“I remember sitting down with the finance minister in Dubai last year discussing this, how Dubai tried to push this forward. It’s that ability for people with very large fiat balance sheets to be able to move into crypto and then move out again. And it’s the out part.”
A Low Tolerance of Bullshit
On the question of the ecosystem’s culture, whether the unpredictability and occasional dishonesty of crypto markets is itself a deterrent, Mog is clear-eyed but not apologetic. He sees it as an honest reflection of human nature. And he believes that network-level design can progressively make the worst behaviors impossible, if not always immediately.
What he is proud of, in the network he has spent years helping to build, is something harder to quantify: a culture that is intolerant of extraction for its own sake.
“There are no meme coins. There is no extractive, pointless DeFi just for the sake of DeFi. The people governing this network have skin in the game. Not just monetary, but emotional and intellectual skin in the game. Around real use cases, not around hype. There’ll always be hype, but maybe that’s marketing. You can build a chocolate bar company and still have some hype marketing. But there’s a low tolerance of bullshit. And that’s a very nice place to be.”
There’s a low tolerance of bullshit. And that’s a very nice place to be.
We had been talking for well over an hour. As Mog stood to leave, he offered a final observation that seemed, in retrospect, to be the thesis of the entire conversation.
“I don’t do short answers.”
He doesn’t. And in a space that is often characterized by confident brevity and oversimplification, that is not a small thing.
Bitget's new Stock+ feature allows eligible users to access U.S. stocks and ETFs through crypto-funded accounts, reflecting the growing convergence of digital assets and traditional finance.
TL;DR
Bitget has launched Stock+, expanding stock trading on the platform with access to more than 10,000 U.S.-listed stocks and ETFs.
Users’ crypto assets are converted into USDC, transferred to a securities sub-account to purchase real shares through licensed U.S. brokers.
The launch reflects a broader push by crypto platforms into traditional finance and multi-asset investing.
Crypto exchange Bitget expands further into traditional finance with the launch of Stock+, also referred to as Bitget US Stocks, a new feature under its Stocks 2.0 ecosystem. Bitget now allows users to buy and hold real U.S. stocks directly from their crypto accounts.
The new offering enables eligible users to purchase shares from a universe of over 10,000 U.S.-listed stocks and ETFs. Users’ crypto assets are converted into USDC, transferred to a securities sub-account, and used to purchase shares denominated in USD. The launch marks a significant step in Bitget’s expansion beyond digital assets into traditional financial markets.
As exchanges compete to attract and retain users, many are adding investment products that have traditionally been available only through brokers. The convergence between cryptocurrency platforms and conventional financial markets is growing.
Bringing Stocks to Crypto Users
Through Stock+, Bitget is extending stock trading access to users who already manage their portfolios through the exchange. Users can buy stocks directly with assets held in their Bitget accounts, eliminating the need to convert crypto into fiat or transfer funds to a separate brokerage. Fractional shares are available starting from 0.0001 of a share.
Trades are executed through licensed U.S. brokers RQD Clearing and Atomic Vaults Securities, with orders routed to Nasdaq, the NYSE, and compliant market makers. Users gain full ownership of the underlying shares, including cash dividends, stock dividends, and voting rights. Shareholder rights are exercised through standard brokerage arrangements, consistent with how most retail brokers operate.
According to the company, the product will simplify access to traditional markets while reducing friction between crypto investing and stock ownership. The service operates under Parsa Financial Services, a Bitget Group entity licensed in South Africa by the Financial Sector Conduct Authority, working in partnership with the U.S. brokers. ROD Clearing provides independent custody for user stock assets, which segragates them strictly from Bitget’s own funds.
The service is available to users globally, except those in compliance-restricted jurisdictions. Bitget has not published a comprehensive list of excluded countries.
Stock+ is distinct from Bitget’s rToken products, which were launched in early June 2026 as part of the same Stocks 2.0 initiative. rTokens are on-chain tokens that track the price of U.S. stocks. They represent tokenized beneficial ownership, backed 1:1 by shares held in custody by a licensed broker. In contrast, Stock+ provides ownership of actual shares held in a traditional brokerage sub-account, with shareholder rights administered through standard brokerage arrangements.
Bitget says its rToken suite has listed over 500 U.S. stocks and ETFs, including SpaceX, Tesla, and NVIDIA. Assets under management exceed $50 million. Those figures are self-reported and have not been independently verified.
Exchanges Push Beyond Digital Assets
Bitget’s expansion comes at a time when crypto exchanges are increasingly exploring products linked to traditional finance.
Industry participants have spent the past year introducing services tied to equities, exchange-traded funds, and other real-world assets. The strategy reflects growing demand from users who want access to multiple asset classes through a single account. Coinbase has sought SEC approval for tokenized stock trading. Kraken has pursued regulatory clearance for a 24/7 tokenized equity platform. The NYSE has filed to trade tokenized securities as interest in tokenized equities continues to grow.
For exchanges, diversification can also create new revenue streams. It reduces reliance on cryptocurrency trading volumes, which often fluctuate alongside market conditions.
For retail users, the main appeal is convenience and access. Investors who already hold digital assets can gain exposure to over 10,000 U.S. stocks and ETFs without navigating multiple platforms or funding processes. The product also removes pattern day trader restrictions that apply to U.S. retail brokerage accounts, allowing unlimited day trading.
Stock+ supports inbound transfers of existing U.S. stock holdings from participating brokers, allowing users to consolidate equity positions alongside their crypto. Outbound transfers, moving shares from Bitget to another broker, are not currently supported.
To celebrate the launch, trading fees start from 0.1%, with a 50% promotional discount available through August 31, 2026.
As competition among exchanges intensifies, Bitget’s move into stock trading could encourage more platforms to combine crypto and traditional investments. For now, the launch represents another step toward a more integrated financial landscape where users can manage multiple types of investments from a single platform.