Home Blog Page 45

Offshore Banking & Crypto Off-Ramping: Marcin Lewandowski at NBX Warsaw | Relocatify

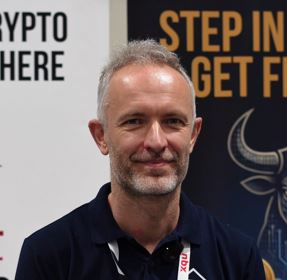
Marcin Lewandowski representing Relocatify at NBX 2026 in Warsaw.

At Next Block Expo 2026 in Warsaw, Marcin Lewandowski introduced Relocatify ’s latest utility: offshore banking in Cambodia. This service helps the crypto community off-ramp crypto into USD seamlessly. Cambodia is ideal because the USD is a native currency there. These accounts remain invisible to the EU and global authorities. Relocatify provides non-EU status cards, including Visa, Mastercard, and Union Pay. These cards ensure financial privacy by hiding the owner’s identity. Users can spend money globally like an Asian tourist.

Buy Phuket Property with Crypto: Piotr Depta at NBX Warsaw | Emerald Shores

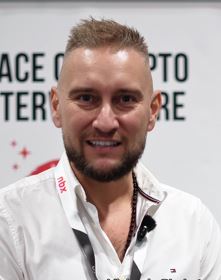
Piotr Depta representing Emerald Shores at NBX 2026 in Warsaw

We spoke with Piotr Depta of Emerald Shores at Next Block Expo 2026 in Warsaw, where he highlighted the growing opportunity to invest in the Phuket, Thailand real estate market. While most transactions currently rely on fiat, Emerald Shores’ primary focus is on enabling clients to purchase luxury villas and houses specifically using cryptocurrency.

Gemini (GEMI) Hit With Shareholder Lawsuit Over Alleged IPO Misstatements

TL;DR

  • Gemini (GEMI) is facing a shareholder lawsuit over alleged misleading IPO disclosures.
  • Investors claim the company failed to disclose a strategy shift toward prediction markets and restructuring.
  • The case follows a sharp post-IPO stock decline and rising concerns about Gemini’s business model.

Gemini Space Station (GEMI) is facing a lawsuit from shareholders who claim they were misled during the firm’s public debut. The lawsuit alleges that key risks and strategic shifts were not properly disclosed ahead of GEMI’s September 2025 IPO.

The proposed class action, filed in a U.S. federal court, targets Gemini Space Station and certain executives. Plaintiffs argue that the company presented an overly optimistic picture of its crypto platform and international growth plans, even as they were already preparing for a significant operational pivot internally.

GEMI shareholder lawsuit targets IPO disclosures

At the center of the complaint is the claim that Gemini failed to disclose a planned shift in business focus. According to filings cited across multiple reports, the company moved toward prediction markets and away from parts of its core crypto exchange operations shortly after going public.

Investors argue this transition was not adequately communicated in IPO materials. They claim the omission created a mismatch between what shareholders believed they were investing in and the company’s actual direction.

The lawsuit also points to additional undisclosed pressures, including declining user engagement and increasing competition across crypto trading platforms.

Strategy shift followed by restructuring

The controversy intensified after Gemini announced a series of operational changes in early 2026. These included workforce reductions, a pullback from several international markets, and the departure of senior executives.

The management framed the restructuring as a step toward long-term efficiency. Shareholders, however, believe it reflects deeper issues that should have been disclosed earlier.

The lawsuit specifically links these moves to a broader strategic reset that investors say contradicts the GEMI’s IPO narrative.

Stock decline amplifies investor losses

The legal action comes amid a steep drop in Gemini’s share price. The stock debuted at around $28 per share. It has since fallen below $7 on several occasions, erasing a significant portion of its market value.

This decline has become central to the case against GEMI. Plaintiffs argue that once the company’s true operational direction became clearer, the market reacted quickly, leading to substantial investor losses.

Analyst commentary cited in coverage from financial outlets also points to ongoing concerns around profitability, user growth, and competitive positioning.

Financial pressure and business outlook

Adding to the pressure, Gemini reported a substantial net loss for 2025. The company has defended its strategy, stating that a stronger focus on the U.S. market and new product categories such as prediction markets could improve long-term performance.

However, the gap between that forward-looking narrative and earlier IPO messaging is now under scrutiny. Multiple law firms have since issued notices encouraging affected investors to join the case. The deadlines to apply as lead plaintiff are set for May 2026.

Broader implications for crypto listings

The GEMI shareholder lawsuit highlights a recurring issue in crypto-related public listings. Companies operating in rapidly evolving markets often adjust strategy quickly. However, public investors expect clearer disclosure of those risks at the time of listing.

For newer entrants to public markets, this case may reinforce the need for tighter alignment between IPO messaging and internal planning. It also underscores how quickly sentiment can shift when operational changes follow a listing too closely.

The outcome of the case remains uncertain. For now, it adds to growing scrutiny around how crypto firms present their business models to mainstream investors.

Developers Targeted in OpenClaw Wallet Theft Scam on GitHub

TL;DR

  • Attackers used OpenClaw branding on GitHub to trick users into connecting wallets to phishing sites.
  • The scam relied on fake token incentives and user-approved permissions to enable fund theft.
  • The incident highlights growing risks at the intersection of AI platforms and crypto wallet security.

A phishing campaign exploiting the growing visibility of OpenClaw is raising new concerns about how quickly emerging AI platforms can become targets for crypto-related attacks. The theft campaign uses fake token incentives and GitHub-based social engineering to trick OpenClaw users into connecting their wallets to malicious infrastructure.

This approach mirrors a familiar pattern in crypto scams. But the use of developer platforms and AI branding marks a clear shift in targeting strategy.

GitHub phishing campaign targets developers

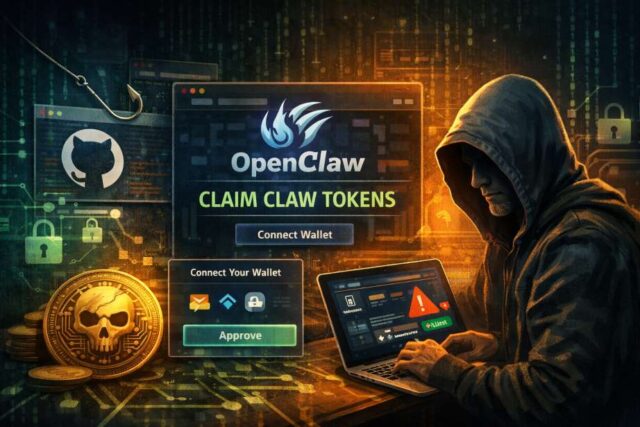
At the center of the incident is a coordinated effort to impersonate OpenClaw across GitHub. Attackers used fake accounts to post issue comments and engage with users who interacted with OpenClaw repositories, directing them to phishing pages designed to steal funds from connected crypto wallets.

Victims were offered up to $5,000 in “CLAW” tokens. The message then linked to a cloned OpenClaw-style website. Once there, users were prompted to connect their wallets to claim the tokens. Approving access exposes permissions that allow attackers to execute transactions without further interaction and drain the crypto wallet.

This is a simple setup, exploiting user trust with a classic fake token scam. It works because it looks legitimate.

How the OpenClaw wallet theft scam works

Technically, the mechanism is straightforward and relies on user-approved wallet permissions, not direct system compromise.

Analysis of the phishing infrastructure revealed obfuscated JavaScript designed to hide its function. In several cases, a script labeled “eleven.js” handled wallet interaction logic.

Once a wallet connection is initiated, the script can request approvals or trigger transactions that enable asset transfers. Some versions even clear browser storage to remove traces of the interaction.

This is not a sophisticated exploit. It does not need to be. The attack succeeds if the user approves the request.

At the time of reporting, no confirmed financial losses were publicly documented. Still, the infrastructure was active and ready to be used.

No official token, but repeated crypto bait

OpenClaw is not a crypto project and does not have an official token. Project leadership has repeatedly warned that any “CLAW” token is not legitimate.

Even so, attackers continue to reuse the same narrative. The promise of early rewards taps into familiar crypto behavior, where users expect incentives tied to new platforms.

This gap between official messaging and user expectations is a key security risk for OpenClaw users because it gives attackers a reliable entry point.

The tactic is not new. The delivery method is.

Why AI agent ecosystems are becoming a new risk layer

More broadly, the incident exposes growing concerns about how AI agent ecosystems can create new crypto-related security risks. Separate research has identified hundreds of potentially malicious third-party tools within the OpenClaw ecosystem.

These tools can interact with wallets, APIs, and external systems. That expands the attack surface significantly.

The phishing campaign itself operates outside the platform. But the pattern is consistent. Rapid ecosystem growth is outpacing security controls.

For users, the risk is no longer isolated to exchanges or DeFi apps. It now extends into experimental tools and automation layers.

What this means for crypto users

The incident highlights a shift in how crypto scams are delivered. Attackers exploit OpenClaw’s branding, pushing users to wallet approvals that expose them to theft. Bad actors no longer rely solely on email or social media. They are embedding themselves inside developer environments and trusted platforms where people are more likely to engage and less likely to question legitimacy.

But the core rule remains unchanged. Wallet connection requests carry real risk. A single approval on a malicious interface can lead to irreversible loss. As AI platforms continue to integrate with blockchain tools, that risk will only grow. The boundary between experimentation and financial exposure is getting thinner.

In this environment, a wallet approval is not a minor action. It is a direct financial risk.

SEC and CFTC Define Digital Commodities in Landmark Crypto Guidance

TL;DR

  • The SEC and the CFTC released joint guidance defining digital commodities and clarifying how securities laws apply to crypto assets.
  • The regulators cited 16 cryptocurrencies, including Bitcoin, Ethereum, Solana, and XRP, as examples of assets that function as digital commodities.
  • The framework states that most crypto assets are not securities themselves, though certain transactions involving them may still qualify as investment contracts.

The SEC and the CFTC introduced a joint digital commodities framework this week, marking one of the most significant regulatory developments in U.S. crypto market history.

Together, the U.S. Securities and Exchange Commission (SEC) and the U.S. Commodity Futures Trading Commission (CFTC) issued new guidance clarifying how federal securities laws apply to digital assets. The interpretation states that most cryptocurrencies are not securities by themselves. It also introduces a formal classification system for different types of crypto assets.

The framework aims to resolve years of regulatory uncertainty that shaped the industry since the rise of cryptocurrencies in the late 2010s.

A New Framework for Crypto Assets

At its core, the guidance introduces a taxonomy separating digital assets into several categories based on their economic function and use within blockchain networks.

Among the most important categories is digital commodities. It refers to crypto assets that function primarily as decentralized network tokens rather than investment contracts tied to a centralized issuer.

According to regulators, the digital commodities classification includes tokens that power decentralized networks, enable transactions, or provide access to blockchain-based services without representing ownership in a company or profit-sharing arrangement.

This distinction matters because securities fall under the SEC’s jurisdiction, while the CFTC generally oversees commodity-like assets in derivatives markets.

The 16 Crypto Assets Named as Digital Commodities

As part of the guidance, regulators cited 16 tokens as examples of digital commodities. These include some of the largest cryptocurrencies by market capitalization.

Examples mentioned include Bitcoin, Ethereum, Solana, Cardano, Avalanche, Polkadot, Chainlink, Dogecoin, Shiba Inu, Stellar, Tezos, Litecoin, Hedera, Bitcoin Cash, Aptos, and XRP.


Regulators noted that they selected these assets partly because they already underlie futures contracts traded on CFTC-regulated exchanges. However, the agencies stressed that a crypto asset does not need an active futures market to qualify as a digital commodity.

Through these examples, the regulators intended to illustrate how they may evaluate other tokens. They don’t equal a complete list.

Assets vs. Transactions Under Securities Law

One of the most important elements of the guidance is the distinction between a crypto asset itself and the method it is offered or distributed.

Even if a token qualifies as a digital commodity, certain transactions involving that token may still represent securities offerings. For example, if a project sells tokens to investors with promises of future profit based on managerial efforts, that arrangement could still be considered an investment contract under U.S. law.

This clarification reflects the long-standing legal framework established by the Howey Test. It determines whether a transaction qualifies as a securities offering.

The new SEC-CFTC digital commodities guidance attempts to explain how this principle applies to blockchain-based assets without automatically classifying the tokens themselves as securities.

Why the Guidance Matters for the Crypto Industry

For years, uncertainty around U.S. crypto regulation has been a major concern for developers, investors, and exchanges. Companies have often struggled to determine whether a token launch or platform feature might trigger securities law obligations.

The joint interpretation from the SEC and CFTC signals a shift toward a more structured regulatory framework. By introducing clearer categories for crypto assets, regulators are attempting to move away from the case-by-case enforcement approach that has dominated the industry.

Market participants hope the clarification will reduce legal risks for blockchain developers and encourage innovation within the United States.

However, the guidance does not fully resolve all regulatory questions. Future rulemaking, court decisions, and potential legislation from Congress may still shape how digital asset markets evolve in the coming years.

For now, the introduction of a formal digital commodity category represents a significant milestone in the ongoing effort to define how cryptocurrencies fit within the U.S. financial regulatory system.

- Advertisement -

FEATURED