Home Blog Page 68

KlarnaUSD Takes Aim at $120 Billion in Cross-Border Fees
TL;DR

  • KlarnaUSD is Klarna’s new dollar-backed stablecoin, designed to move money across borders faster than traditional banking rails.
  • Built on the Tempo blockchain, it enables near-instant, low-cost settlement for merchant payments and BNPL flows.
  • Klarna’s scale and banking license give it a credible path to bring stablecoin-based settlement into everyday commerce.

Global commerce moves roughly $23.5 trillion across borders every year, yet the payments infrastructure remains costly and inefficient. The complex web of correspondent banks, card networks, acquirers, FX brokers, and compliance layers extracts an estimated $120 billion in fees annually from these transactions. But often they deliver slow settlement times and opaque pricing. The new KlarnaUSD stablecoin aims to disrupt this costly ecosystem. Klarna will provide a dollar-backed digital asset that settles transactions faster and cheaper than legacy payment networks.

Klarna’s push into stablecoins is not a superficial move. It is a strategic attempt to shift substantial payment volume away from traditional rails toward programmable, low-latency blockchain-based infrastructure. Success could reshape how merchants, consumers, and global e-commerce platforms transfer funds on a massive scale.

KlarnaUSD: A Simple Concept With Significant Implications

Klarna’s stablecoin is designed for real-world use cases, such as retail checkout, merchant settlement, remittances, and supplier payments. The fully dollar-backed token is issued via Stripe’s stablecoin infrastructure built for regulated institutions. It runs on Tempo, a blockchain developed by Stripe and Paradigm that prioritizes high throughput, rapid finality, and extremely low fees, all tailored for payment settlements rather than speculation. KlarnaUSD is currently live on testnet, allowing early integrations and testing, with a mainnet launch planned for 2026.

Klarna enters this market with a unique profile:

  • It processes over $110 billion in annual gross merchandise volume (GMV).
  • It serves 114 million customers globally.
  • It operates as a licensed European bank, funding a majority of its credit book through deposits.

This blend of scale, regulation, and deeply integrated distribution positions the KlarnaUSD stablecoin as a mass-market settlement instrument beyond typical crypto projects.

Why Cross-Border Payments Are the Focus

Cross-border payments, and cross-border commerce more broadly, suffer from fragmentation, delays, and layered fees as transactions pass through multiple intermediaries:
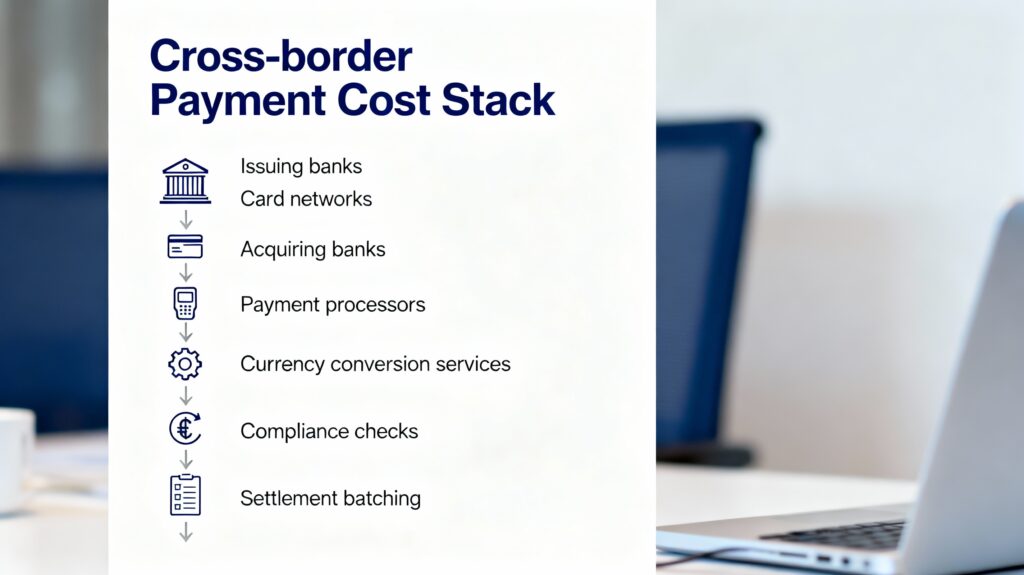
Each participant levies fees and adds latency. This cost structure burdens merchants operating with thin margins or serving sensitive, price-conscious regions.

Stablecoins like KlarnaUSD can reduce this burden by eliminating redundant intermediary hops and substantially lowering FX markups in many corridors. Additionally, programmable settlement collapses payment cycles from days to near-instant flows. It reduces working capital needs and improves liquidity which are key pain points for cross-border commerce.

Riding a Growing Stablecoin Wave

Stablecoins already process tens of trillions in annual volume, with estimates ranging from $18 trillion to upwards of $28 trillion depending on measurement methodology. Corporate stablecoin adoption is fastest in Latin America, Asia-Pacific, and MENA regions, where stablecoins overtly outperform traditional bank transfers on speed and cost.

KlarnaUSD launches into this vibrant market, building on a rapidly expanding curve of stablecoin adoption reshaping global payment behavior.

Tempo Blockchain: Focused on Payments

Unlike blockchains optimized for trading or DeFi, Tempo prioritizes payment needs. It offers seconds-level finality, transaction fees in fractions of a cent, and integrates directly with Stripe’s merchant ecosystem. This allows merchants to accept stablecoin payments and settle instantly without managing wallets, keys, or exposure to decentralized finance complexities.

Tempo’s design contrasts sharply with card networks, which focus on authorization and consumer protections. However, they cannot offer true real-time, frictionless global settlement. Klarna aims to present merchants with a credible, cost-effective alternative to the prevailing costly interchange, FX, and acquirer fee stack dominating global retail commerce.

Klarna’s Broader Business Transformation

Klarna’s stablecoin initiative aligns tightly with its existing Buy Now, Pay Later (BNPL) business. Klarna funds roughly 95% of its credit book through customer deposits, but its U.S. operations are limited by dependencies on partner institutions holding dollars. A dollar-backed stablecoin enables:

  • Instant merchant settlement
  • Faster BNPL credit disbursements
  • Enhanced liquidity management across regions
  • Lower FX exposure and costs in cross-border transactions

Ultimately, Klarna anticipates BNPL could settle through real-time stablecoin flows, shrinking the lag between purchase, merchant payout, and internal reconciliation. That would represent a clear advantage over BNPL competitors still tied to slower legacy rails.

Adoption Outlook: Impact If KlarnaUSD Scales

  • Merchant adoption via Stripe’s extensive distribution allows merchants to improve economics without altering their front-end user experience.
  • Consumer benefits include faster refunds, faster cross-border checkouts, and fewer hidden FX fees, all while abstracting blockchain complexities behind Klarna’s app.
  • BNPL infrastructure efficiency gains from quicker settlement cycles, freeing capital and enabling operational agility.

Regulatory and Competitive Landscape

The U.S. GENIUS Act, adopted in 2025, lays a comprehensive regulatory framework for stablecoins, mandating permitted issuers to hold 1:1 USD reserves with strict disclosure and liquidity requirements. The EU’s MiCA regulation imposes transaction volume caps and criteria on non-euro stablecoins, applying to dollar-backed e-money tokens used as currency substitutes.

Klarna’s status as a licensed, regulated European bank situates it uniquely among stablecoin issuers, distinct from unregulated crypto startups. Competitors like PayPal USD , Société Générale’s EURCV, and Circle’s USDC are extending the stablecoin settlement category, signaling increased institutional adoption.

A New Phase in the Payments Race

The launch of KlarnaUSD reflects a broader trend where major incumbents with real customers and financial infrastructure shift toward blockchain rails for payments. Klarna’s effort is not about speculative assets but redirecting meaningful global payment flows away from expensive intermediaries toward near-instant digital settlement.

Whether Klarna can scale its stablecoin will depend on regulation, merchant incentives, and Tempo’s performance at scale. But the direction is clear: the payments ecosystem is evolving to operate more like the internet—fast, cheap, and borderless, eliminating unnecessary bottlenecks.

If Klarna succeeds, it won’t merely save costs; it will alter the fundamental logic of how money moves across borders worldwide.
Revolut’s $75B Surge and the Polygon Engine Behind Its Zero-Fee Remittance Boom

TL;DR

  • Revolut’s new $75B valuation is driven by the rapid success of its Polygon-powered stablecoin payments and zero-fee remittance infrastructure.
  • The company has already processed $690M–$775M through USDC/USDT transfers on Polygon, cutting costs and outpacing traditional remittance rails.
  • Stablecoins are becoming the backbone of Revolut’s cross-border strategy, replacing legacy payment infrastructure with faster, cheaper, programmable settlement.

Revolut’s newest funding round pushed the company to a whopping $75B valuation. It is now placed among the most valuable fintechs on the planet. Investors aren’t rewarding another neobank with a polished interface. In fact, they’re betting on a company that quietly rebuilt its payments infrastructure. And the reason is clear: the Revolut Polygon integration has become one of the most successful product roll-outs in the company’s history.

Revolut’s use of stablecoins is no longer a mere side feature. It is reshaping the company’s economics, accelerating user growth, and positioning Revolut as Europe’s leading crypto-enabled fintech.

Revolut’s New Engine: Polygon-Powered Stablecoin Payments

Revolut has integrated Polygon as its core settlement layer for stablecoin flows. This includes USDC and USDT payments across the UK and EEA, enabling users to send value globally with near-zero friction. Revolut’s stablecoin payment infrastructure uses Polygon’s low-cost, high-throughput network to deliver instant settlement.

Users can now send Polygon USDC transfers and Polygon USDT payments at a cost low enough for Revolut to absorb the fees entirely. The result is a payments experience faster and cheaper than traditional rails. On top of that, it can scale without relying on legacy card networks or correspondent banks.

For Revolut, this shift is strategic. Stablecoins provide a programmable, globally interoperable backbone that fits the company’s ambition to become a universal financial platform.

$690M–$775M Processed: Adoption That Outpaced Expectations

As per various reports, Revolut has already processed well over $690M through Polygon-based stablecoin transfers. Variations in reported numbers reflect different reporting dates, but the trend is unmistakable: demand for Revolut crypto integration is accelerating.

These flows increasingly feed into Revolut’s broader ecosystem: remittances, trading services, and business accounts. Customers aren’t just using the feature once; they are truly adopting Revolut international payments as a routine alternative to bank wires and card-based transfers.

Polygon’s efficiency has enabled Revolut to scale payment volumes without scaling operational costs. Hence, the company benefits from a competitive advantage over legacy remittance providers.

The Zero-Fee Remittance Strategy

Revolut’s introduction of zero-fee remittances is a clear attempt to undercut traditional operators. Thanks to Polygon’s low transaction costs, the company can absorb the fees and still offer an extremely fast experience.

This is where Revolut zero-fee remittances become a core differentiator. The company has effectively created a stablecoin remittance corridor between the UK and EEA, bypassing the FX markups and network fees that banks rely on.

The strategy is simple: near-instant settlement, zero service fees, and transparent pricing. Users respond to this value proposition, particularly in cross-border contexts where traditional fees are still high.

How Stablecoins Became a Profit Center

Revolut is not monetizing remittances directly. Instead, it is monetizing everything surrounding them. By leaning on low-cost stablecoin transfers, Revolut reduces backend expenses and increases payment velocity.

This shift supports a broader fintech stablecoin strategy, where stablecoins reduce structural operating costs and improve capital efficiency. Revolut then earns revenue on the higher-margin parts of the stack: trading, liquidity flows, premium tiers, staking, and treasury functions.

The success of the Revolut Polygon integration is therefore not just a technical achievement. It is part of a business model that scales faster and more profitably than conventional neobanking.

Why Polygon Fits Revolut’s Long-Term Plan

Polygon offers predictably low fees, fast finality, and an ecosystem mature enough for enterprise integrations. These traits make it a strong match for Revolut’s ambitions.

The Polygon payments network allows Revolut to roll out advanced features such as staking, instant settlement, and multi-asset support without navigating the constraints of traditional banking infrastructure. This aligns with broader trends in fintech crypto adoption, where stablecoin rails are increasingly seen as the next evolution in global payments.

Polygon also gives Revolut room to expand across markets, assets, and business use cases. The expansion won’t require fundamental reengineering its backend.

Revolut vs PayPal, Coinbase, and Wise

Revolut is now competing across three categories at once:

  • Against PayPal: faster processing and cheaper cross-border crypto payments.
  • Against Coinbase: integrated financial services bundled with crypto.
  • Against Wise: lower remittance costs through superior settlement infrastructure.

Through this approach, Revolut is effectively building a parallel settlement system that bypasses legacy rails and uses stablecoins as the default transport layer. So, this is not a cosmetic addition but a significant change in the economics of money movement.

The Revenue Mix Behind the $75B Valuation

The company’s $75B valuation reflects more than user growth. Investors are rewarding Revolut for building a scalable payments engine. Revenue increasingly comes from:

  • trading commissions
  • crypto liquidity flows
  • staking services
  • stablecoin settlement for remittances
  • premium financial tiers
  • business accounts using USDC or USDT

These lines grow faster and at better margins than traditional banking services. The Polygon integration has become a multiplier across Revolut’s entire financial stack.

What Comes Next: Expansion of Stablecoin-Powered Payments

Revolut is now positioned to expand this model across new corridors. As more regions adopt stablecoin-friendly regulations, the company can deploy its infrastructure with minimal friction. Remittance routes into LATAM, MENA, and Asia are natural next steps, alongside support for additional stablecoins. More advanced treasury and settlement tools for businesses are also on the table, and deeper integration with trading and on-chain liquidity may follow.

Having built the rails, Revolut is now turning stablecoins into the backbone of its cross-border financial system.

Naver in Talks to Acquire Upbit Operator Dunamu in KRW 20T Deal, Reshaping Korea’s Fintech Market

Upbit Suspension Threat: 700K KYC Violations Spark Regulatory Crackdown

TL;DR

  • Naver Financial is in talks to acquire Dunamu, Upbit’s operator, in a KRW 20T stock-swap merger deal.
  • The merger would combine Naver’s fintech services with Korea’s largest crypto exchange, creating the first real challenger to Kakao.
  • Strong Upbit profits and Dunamu’s scale support the deal, which could also revive Dunamu’s Nasdaq ambitions.

Naver Financial is in advanced discussions to acquire Dunamu, the operator of Korea’s largest cryptocurrency exchange Upbit. The potential stock-swap deal is estimated at around KRW 20 trillion. If finalized, the transaction would merge Naver’s payments and digital-banking ecosystem with the country’s dominant crypto-trading platform, creating one of the most influential fintech conglomerates in South Korea.

Reports from Korean and industry media describe the Naver–Dunamu merger as a potential turning point in the country’s financial technology sector. Naver is seeking a stronger role in digital finance to compete more directly with Kakao. At the same time, Dunamu would gain the institutional scale and governance advantages of a major technology parent company.

Inside the Proposed KRW 20T Stock-Swap Deal

Sources indicate the negotiations center on a stock-swap structure rather than a cash acquisition. That would allow Naver Financial to integrate Dunamu without immediate liquidity pressure. The talks remain ongoing, but several outlets report that Naver’s board has already scheduled internal reviews of the proposed acquisition.

For Naver, the deal would deepen its foothold in payments, wealth, and digital financial services. For Upbit operator Dunamu, the merger offers an opportunity to operate within a larger corporate framework. This isn’t a minor factor as competition intensifies across the Korean fintech market and as regulatory expectations rise.

A Merger That Could Reshape Korea’s Fintech Market

If completed, the merger would link Naver’s fintech businesses with Upbit’s dominant role in the local crypto market. Analysts say such a merger could significantly strengthen Korea’s position as a regional fintech hub and accelerate consolidation in a market increasingly defined by super-apps and integrated financial ecosystems.

Contextualizing Kakao’s Role

The potential merger also shifts the competitive balance with Kakao, which currently leads Korea’s consumer fintech market through KakaoPay and the fully digital Kakao Bank. Kakao’s dominance in everyday payments and mobile banking has long positioned it as the country’s default financial super-app. A merged Naver–Dunamu company would become the first rival with comparable reach. The combination brings together Naver’s payments network and Dunamu’s digital-asset operations, positioning the group to compete more directly with Kakao.

If completed, the Naver Dunamu merger would mark one of the most significant restructurings in Korea’s fintech market.

Upbit’s Strong Fundamentals Add Momentum

Dunamu’s financial performance has reinforced the strategic logic behind the merger. The company posted $165 million in Q3 profit, marking 300% year-over-year growth. Upbit remains the dominant exchange in Korea by trading volume and user activity. Dunamu maintains a strong revenue base as the industry prepares for more stringent licensing under the country’s emerging regulatory framework.

These fundamentals make the acquisition more attractive for Naver and help sustain market confidence as negotiations progress.

How the Deal Reopens Dunamu’s Long-Stalled Nasdaq Ambitions

A secondary implication of the merger is the renewed attention on Dunamu’s previously paused plans for a U.S. listing. The company explored a Nasdaq IPO in 2021–2022 before shelving the effort amid regulatory uncertainty and market volatility.

Analysts say a successful integration with Naver Financial would improve governance, transparency, and corporate structure. Such conditions typically strengthen the outlook for companies considering an overseas IPO. While not the central focus of the merger, the transaction could make an eventual Upbit Nasdaq listing technically and reputationally more attainable.

What Comes Next

Naver’s board is expected to continue evaluating the acquisition in the near term. Any final agreement would require regulatory review in Korea, particularly given Upbit’s dominant position in the domestic crypto market. Pending approval, the merger could reshape competitive dynamics across banking, payments, and digital asset services.

If completed, the Naver Financial acquisition of Dunamu would mark one of Korea’s largest fintech deals to date. It seems to usher in a decisive shift toward integrated, large-scale financial platforms capable of competing on both domestic and global stages.

Bitcoin for America: Big Fiscal Claims, Bigger Operational Challenges

TL;DR

  • The Bitcoin for America Act would let Americans pay federal taxes in Bitcoin and route those inflows into a Strategic Bitcoin Reserve.
  • Supporters claim this could strengthen the U.S. balance sheet, but those projections rely on optimistic modeling and assume steady BTC appreciation.
  • The bill is thin on statutory detail and leaves major gaps in custody, compliance, AML screening, revenue stability, and IRS infrastructure—making execution far more complex than the proposal suggests.

Rep. Warren Davidson’s Bitcoin for America Act (H.R.6180) proposes one of the boldest integrations of cryptocurrency into U.S. fiscal policy so far. The bill would let individuals and businesses pay federal taxes in Bitcoin, then route those assets into a long-term Strategic Bitcoin Reserve. Supporters argue that steady “sovereign DCA” could strengthen America’s balance sheet and reduce reliance on inflation-prone debt. Yet the numbers used to justify these claims rely on optimistic modeling. The bill also introduces operational, regulatory, and fiscal complexities that could overwhelm the benefits. Innovative or not, the proposal raises questions about whether the U.S. government can actually run a system like this at scale.

What the Bitcoin for America Act Actually Proposes

At its core, the Bitcoin for America bill makes two major changes. First, it allows taxpayers to send Bitcoin directly to the IRS to settle federal obligations. The valuation would be determined at the time of transfer, and the contribution would count as a non-recognition event. This means taxpayers using appreciated BTC to pay what they owe would not trigger capital gains. For individuals who already calculate their obligations in digital assets, this would help reduce friction and create a clearer framework for how Bitcoin tax payments would work in practice.

The second part of the bill channels all Bitcoin tax payments into a Strategic Bitcoin Reserve. This reserve builds on the Trump administration’s executive order that consolidated seized Bitcoin rather than auctioning it. Under the proposal, the reserve would operate with long holding periods, a strict annual sales cap, and a mandate to treat Bitcoin as a strategic monetary asset. With these rules in place, the bill seeks to create a U.S. Treasury Bitcoin reserve designed to compound over decades, not serve short-term budget needs.

However, one issue stands out immediately: this Bitcoin Act is unusually thin in terms of actionable statutory language. Much of the text reads more like a policy paper than a conventional bill. It offers narrative, justification, and macro-level argument but lacks the detailed amendments and procedural clauses that normally integrate legislation into the U.S. Code. This does not make the proposal unserious. Yet it signals that congressional staff, and likely Treasury and IRS technical teams, would need to rewrite much of it before it could operate as functional law.

The Case for a Fiscal Hedge

Supporters argue that the U.S. balance sheet needs alternatives. Federal deficits remain high, interest expenses continue to rise, and reliance on debt exposes the government to inflation cycles and elevated yields. For this group, Bitcoin’s fixed supply and predictable issuance schedule make it a long-term hedge against monetary debasement.

Much of the enthusiasm comes from modeling by the Bitcoin Policy Institute. Their projections assume that even a small share of taxes, even as little as 1 percent, paid in Bitcoin could accumulate several million BTC over two decades. Because the reserve structure relies on voluntary contributions, the bill avoids the optics and market disruption of direct government buying. It becomes a market-driven reserve mechanism rather than a top-down acquisition program.

These ideas fit into the broader landscape of Bitcoin policy legislation, where lawmakers have tried to integrate digital assets into fiscal planning without aggressive state purchases.

The Gap Between Modeled Upside and Real-World Constraints

The optimistic numbers circulating around the proposal rely on assumptions that may not hold. Many projections treat long-term Bitcoin appreciation as a near certainty and downplay Bitcoin volatility risk. However, they rarely consider the impact of BTC price cycles on tax revenue, which becomes critical if part of federal intake arrives in a volatile asset.

Revenue Volatility

The government relies on stable revenue patterns to budget for spending and emergency actions. If the IRS begins accepting Bitcoin, revenue projections become tied to market cycles. Strong inflows during bull markets could vanish in down cycles. This instability weakens the claim that the reserve strengthens the balance sheet, since the government has almost no control over timing.

Budget Scoring Uncertainty

The Congressional Budget Office evaluates how policies affect revenues and deficits. When taxpayers pay federal taxes in Bitcoin instead of selling BTC for dollars, capital gains tax events disappear. That erases taxable revenue the government would otherwise collect. As a result, budget scoring for cryptocurrency policy becomes unusually difficult. The reserve may gain assets, but Treasury may lose traditional revenue.

Liquidity Mismatch

A long-term reserve cannot support short-term needs. The proposal’s 20-year horizon and strict sales cap limit the government’s ability to use the reserve flexibly. This mismatch means Bitcoin might improve the balance sheet on paper while contributing little to fiscal resilience during downturns.

The Operational Realities the Bill Doesn’t Resolve

Beyond fiscal questions, the bill introduces several practical issues that require major infrastructure upgrades across Treasury and the IRS.

Custody and Security

The government does not operate a scalable system for holding large amounts of digital assets. Creating one would require extensive upgrades in key management, hardware security modules, chain-of-custody processes, and external partnerships. Creating one would require major upgrades in key management, hardware security modules, chain-of-custody processes, and multiple external partnerships. In practice, this is a question of how the Treasury can handle custody and security for digital assets, an area where federal infrastructure is still limited.

AML and Sanctions Compliance

Accepting Bitcoin tax payments means screening UTXOs before acceptance. Tainted coins create legal and operational emergencies. Regulators also need clear protocols for rejected payments. These operational challenges for Bitcoin tax intake in America remain unresolved.

Small-Business Friction

For small businesses, crypto volatility is not an abstraction. If firms calculate quarterly obligations in dollars but pay taxes in Bitcoin, timing becomes critical. Rapid swings can distort liabilities. Some companies would also struggle with tax compliance when handling crypto, especially small businesses that must manage accounting rules, payroll integration, and reconciliation.

Administrative Complexity

IRS systems were not built to process, timestamp, and reconcile digital-asset payments. Integrating these processes into existing frameworks would require extensive changes to IRS cryptocurrency rules and internal workflows. These issues remain separate from broader questions about federal crypto regulation, which still lacks clear long-term direction.

The Political and Strategic Context

The bill sits within a broader GOP effort to position the United States as a leader in digital-asset strategy. It follows earlier proposals from Sen. Lummis and Rep. Donalds that aimed to formalize federal Bitcoin reserves and clarify custody requirements. The Strategic Bitcoin Reserve aligns with this vision and presents the U.S. as competing with other nations in accumulating strategic digital assets.

However, the proposal’s legislative path is uncertain. Even crypto-friendly lawmakers may hesitate to support a bill that relies on volatile revenue flows, introduces administrative burdens, and requires significant new infrastructure. In a divided Congress, advancing a bill that would reshape tax intake is challenging.

Conclusion — Innovation vs Implementation

The Bitcoin for America Act is one of the most ambitious attempts to integrate Bitcoin into sovereign finance. It offers a compelling narrative about long-term reserves, fiscal diversification, and taxpayer optionality. Yet the proposal is thin on statutory detail and heavy on conceptual framing. The gaps between vision and execution remain large. The idea may be directionally interesting, but the real test is whether policymakers can transform this essay-like proposal into a statute that works in practice.

Institutional Outflows, Not Whales, Drove Bitcoin’s Slide Toward $80K

As volatility spiked this week, attention focused on flash crashes and billion-dollar liquidations. But the data shows the downturn started earlier, when spot Bitcoin ETFs came under pressure and recorded their steepest outflows since launch. Issuers became net sellers into a fragile market. This accelerated Bitcoin’s fall before leveraged positions and larger holders added to the cascade. For many traders asking what caused the Bitcoin crash this week, the earliest signals came from fund redemption flows, not technical failures.

Bitcoin’s drop from the mid-$90,000s toward levels near $80,000 looked sudden. But the first cracks appeared when BTC slipped below the approximate cost basis for most 2025 ETF inflows, around $89,600. That shift pushed many institutional investors into negative territory. It triggered a wave of Bitcoin ETF outflows that preceded the sharpest price action. This sequence, structural selling followed by volatility, explains the early pressure more accurately than the liquidation-driven narrative that dominated social media.

The Trigger: ETF Buyers Go Underwater

For most of the year, spot Bitcoin ETFs acted as consistent sources of demand. That dynamic reversed once prices fell through the ETF cohort’s cost basis. Redemptions accelerated as positions turned unprofitable. Issuers responded by reducing exposure, and that institutional BTC selling arrived well before the market’s most violent moves. The speculation whether ETF outflows caused the Bitcoin crash is supported by the timing of events.

The sell pressure hit a market already coping with liquidity thinning. As redemptions rose, order books weakened and normal two-sided trading conditions deteriorated. With market depth shrinking, even moderate selling created a chain reaction. That chain reaction set the stage for broader stress. This is where Bitcoin selling pressure became even more visible.

Record Redemptions Deepen the Sell-Off

November’s data shows Bitcoin ETF redemptions approaching record levels. BlackRock’s flagship product saw its largest single-day outflow since launch. Combined redemptions across issuers neared $3 billion. Because ETF redemptions require issuers to sell or unwind spot BTC exposure, these flows became one of the earliest contributors to the downturn.

These outflows helped shape the broader crypto market sell-off. Volatility rose as market depth weakened. In reaction to the ETF redemptions, Bitcoin’s price struggled to hold support levels. Japan’s shock fiscal stimulus drove yields higher and unsettled global markets. At the same time, U.S. expectations for near-term rate cuts softened, which reduced risk appetite. These macro factors did not initiate the decline but strengthened it.

After Liquidity Thinned, Liquidations Took Over

Once Bitcoin slipped below $90,000, it initiated a liquidation cascade. Stop-loss orders triggered across major venues as leverage unwound. Nearly $1 billion in BTC long positions were liquidated in a 24-hour window. Crypto-wide liquidations exceeded $1.9 billion.

Thin order books on derivatives exchanges magnified the move. Some platforms printed sudden wicks toward the low-$80,000s, which fed questions like why did Bitcoin drop below 90k. The resulting volatility included isolated moves resembling a BTC falls to 80k scenario on certain venues. Spot markets did not fully confirm those levels.

These Bitcoin liquidations were not the cause of the breakdown. They were a consequence of earlier structural selling. Once ETF-driven flows weakened the market, automated systems simply reacted to falling prices.

Whales Reacted to the Decline — They Didn’t Cause It

Whale activity gained attention later, especially after an early-era wallet moved coins for the first time in years. But these transfers occurred after the structural decline was underway. Larger holders reacted to the stress rather than initiating it. The impact of institutional selling on BTC price during the early stages was far greater.

This distinction clarifies the narrative. Whales contributed to volatility, but ETFs influenced direction first.

The New Market Structure: ETF Flows Now Drive Short-Term Direction

This downturn offered a clear view into how Bitcoin behaves in the ETF era. Flows into and out of spot Bitcoin ETFs now influence short-term price trends more directly than miner selling or on-chain metrics. In this case, the earliest and most consequential selling pressure came from ETF issuers responding to investor exits. That shift turned localized weakness into a sustained decline.

As a result, monitoring Bitcoin ETF outflows has become as essential as tracking funding rates or futures open interest. Institutional flows have become a leading indicator of momentum. They will remain central to short-term direction.

Outlook: Stability Depends on Flow Reversal

Markets are now watching whether ETF redemptions stabilize. If outflows slow, BTC may build support in the mid-$80,000s. But if institutional selling persists, the market may remain vulnerable. Thin trading periods could amplify that vulnerability.

The week’s downturn showed that Bitcoin’s slide toward $80,000 began well before liquidations or whale activity dominated the narrative. The earliest shift came from ETF issuers. This means Bitcoin ETF outflows remain the key variable to watch as the market tests its next support zones.

Readers’ frequently asked questions

How can I check current Bitcoin ETF inflows and outflows?

You can track real-time inflow and outflow data for U.S. spot Bitcoin ETFs through ETF issuer dashboards, financial data terminals, and independent aggregators such as Farside Investors, SoSoValue, or Bloomberg ETF flow trackers. These sources update daily or intraday depending on reporting schedules.

Do ETF redemptions always require issuers to sell spot Bitcoin?

Redemptions normally require issuers to either sell spot BTC or unwind equivalent exposure unless the ETF structure allows in-kind redemptions. For U.S. spot Bitcoin ETFs, most redemptions result in actual BTC being removed from custody and offset through on-market selling, which impacts short-term liquidity.

What level do traders consider the next major support if Bitcoin weakens again?

Market participants commonly reference the mid-$80,000 area as initial support, followed by the broader $80,000 zone. Some also watch the April 2025 swing low near $74,000 as a deeper support level if macro or flow-driven pressure continues.

What Is In It For You? Action items you might want to consider

Monitor daily Bitcoin ETF flow data

Tracking inflows and outflows from major spot Bitcoin ETFs can help you identify shifts in institutional demand. Significant redemptions often signal weakening short-term momentum.

Watch liquidity conditions on major exchanges

Reduced market depth increases volatility during large price moves. Monitoring liquidity indicators or exchange order book conditions can provide insight into potential stress points.

Keep an eye on macro signals impacting risk appetite

Changes in interest rate expectations, bond yields, or currency volatility may affect Bitcoin’s ability to maintain support levels. Staying aware of macro trends can help you anticipate pressure on digital assets.

- Advertisement -

FEATURED